1. Real estate developer's properties held benami — Appeal under PBPT Act 1988. (Para 1 , 2 , 3 , 4 , 5 , 6 , 7 )
 Back
Next 


2026 Supreme(Raj) 982
HIGH COURT OF JUDICATURE FOR RAJASTHAN AT JODHPUR
ARUN MONGA, SANDEEP SHAH, JJ.
M/s Alishan Complex Private Limited – Appellant
Versus
The Initiating Officer – Respondent
D.B. Civil Miscellaneous Appeal No. 1595 of 2026
Decided On : 03-08-2026
Important Points
A benami transaction finding cannot be based solely on retracted third-party statements without allowing cross-examination. While Benami and Income-tax proceedings are independent, findings from the latter carry evidentiary weight and must be considered to ensure factual consistency and satisfy principles of natural justice.
Subject
Tax Law - Benami Property Transactions
Act Referred
PROHIBITION OF BENAMI PROPERTY TRANSACTION ACT: S.19(1)(b), S.2(9), S.2(9)(a), S.24, S.24(1), S.24(2), S.24(4)(a)(i), S.26(3), S.27, S.46, S.53, S.60, S.67
INCOME TAX ACT: S.132, S.144, S.147, S.68, S.69
CRIMINAL PROCEDURE CODE: S.164
CONSTITUTION OF INDIA: Art.14, Art.21
INCOME TAX ACT: S.132, S.144, S.147, S.68, S.69
CRIMINAL PROCEDURE CODE: S.164
CONSTITUTION OF INDIA: Art.14, Art.21
Headnote
(A) Prohibition of Benami Property Transactions Act, 1988 - Sections 2(9)(A), 24, and 26 - Income-tax Act, 1961 - Sections 69 and 132(4) - Benami transaction - Determination of beneficial ownership - Evidentiary value of statements recorded under separate statutes - Right to cross-examination - Natural justice - Where a finding is substantially founded on the statement of a third-party witness, especially when such statement is retracted, denial of the opportunity to cross-examine the witness constitutes a serious infirmity and renders the order a nullity (Paras 23.3, 23.4, 25.1) - This is particularly true when the statement is foundational rather than merely corroborative.
(B) Relationship between Income-tax Act and PBPT Act - The two enactments operate in distinct though overlapping spheres - A clearance under Section 69 of the Income-tax Act regarding recorded investment does not per se bar proceedings under the PBPT Act, as the former concerns taxability while the latter concerns real ownership - However, findings returned under Section 69 carry evidentiary value and must be considered to avoid factual incoherence (Paras 21.1, 33.1).
(C) Burden of Proof - The initial burden to establish the twin conditions of a benami transaction—namely, that consideration was provided by another person and the property is held for that person's benefit—lies on the authority asserting the transaction to be benami - The law presumes that the person in whose name the property stands is its real owner (Paras 21.2, 21.5).
Facts of the case:
An appellant company's acquisition of 79 immovable properties was declared benami based on materials seized during a search of a different business group and a statement from a chartered accountant recorded under the Income-tax Act. The company contended that the properties were funded from its own long-standing reserves and through banking channels. Concurrently, the assessing officer under the Income-tax Act, examining the same properties, accepted the source of investment and made no additions under Section 69. The adjudicating authority and tribunal upheld the benami status, relying heavily on the chartered accountant's statement, which had been retracted and was not subjected to cross-examination.
Findings of Court:
The court found that the benami determination rested substantially on a retracted statement without cross-examination, violating the principles of natural justice. It further observed that the subsequent assessment order accepting the source of funds and the company's evidence regarding the vintage of its reserves were not adequately considered by the initiating authority or the tribunal.
Issues: The main issues were whether non-indictment under Section 69 of the Income-tax Act operates as a legal bar to action under the PBPT Act, and whether statements recorded under Section 132 of the Income-tax Act can serve as the basis for a benami opinion without allowing the affected party a right of cross-examination.
Ratio Decidendi: While PBPT and Income-tax proceedings are independent, a retracted statement cannot be the foundation of a confiscatory finding like benami without independent corroboration or testing through cross-examination. The failure to engage with the jurisdictional assessing officer's findings on the same set of facts, and the failure to analyze the company's pre-existing reserves, rendered the proceedings flawed.
Result: Order set aside; matter remanded to the Initiating Officer for fresh determination.
(B) Relationship between Income-tax Act and PBPT Act - The two enactments operate in distinct though overlapping spheres - A clearance under Section 69 of the Income-tax Act regarding recorded investment does not per se bar proceedings under the PBPT Act, as the former concerns taxability while the latter concerns real ownership - However, findings returned under Section 69 carry evidentiary value and must be considered to avoid factual incoherence (Paras 21.1, 33.1).
(C) Burden of Proof - The initial burden to establish the twin conditions of a benami transaction—namely, that consideration was provided by another person and the property is held for that person's benefit—lies on the authority asserting the transaction to be benami - The law presumes that the person in whose name the property stands is its real owner (Paras 21.2, 21.5).
Facts of the case:
An appellant company's acquisition of 79 immovable properties was declared benami based on materials seized during a search of a different business group and a statement from a chartered accountant recorded under the Income-tax Act. The company contended that the properties were funded from its own long-standing reserves and through banking channels. Concurrently, the assessing officer under the Income-tax Act, examining the same properties, accepted the source of investment and made no additions under Section 69. The adjudicating authority and tribunal upheld the benami status, relying heavily on the chartered accountant's statement, which had been retracted and was not subjected to cross-examination.
Findings of Court:
The court found that the benami determination rested substantially on a retracted statement without cross-examination, violating the principles of natural justice. It further observed that the subsequent assessment order accepting the source of funds and the company's evidence regarding the vintage of its reserves were not adequately considered by the initiating authority or the tribunal.
Issues: The main issues were whether non-indictment under Section 69 of the Income-tax Act operates as a legal bar to action under the PBPT Act, and whether statements recorded under Section 132 of the Income-tax Act can serve as the basis for a benami opinion without allowing the affected party a right of cross-examination.
Ratio Decidendi: While PBPT and Income-tax proceedings are independent, a retracted statement cannot be the foundation of a confiscatory finding like benami without independent corroboration or testing through cross-examination. The failure to engage with the jurisdictional assessing officer's findings on the same set of facts, and the failure to analyze the company's pre-existing reserves, rendered the proceedings flawed.
Result: Order set aside; matter remanded to the Initiating Officer for fresh determination.
Legal Category Hierarchy
-
benami property transactions
- proceedings
- definition
- evidence
-
statutory interpretation
- section 69, income-tax act, 1961 (Para 21)
- section 2(9)(a), pbpt act, 1988
- section 24, pbpt act, 1988
- practice and procedure
- income tax
Advocates Appeared:
For the Appellant : Mr. Ashwani Taneja, Mr. Divyansh Dubey, Ms. Divya Bapna
For the Respondent: Mr. K.K. Bissa, Mr. G.S. Chouhan
For the Appellant : Mr. Ashwani Taneja, Mr. Divyansh Dubey, Ms. Divya Bapna
For the Respondent: Mr. K.K. Bissa, Mr. G.S. Chouhan
Table of Contents
2. Appellant argues independent funds and no beneficial owner — Revenue relies on search, statements, and shareholding control. (Para 11 , 17 )
3. Uncross-examined retracted statement cannot sole-found benami finding — IO must consider AO's 69 clearance. (Para 21 , 22 , 23 , 24 , 25 , 26 , 27 , 28 , 29 , 30 , 31 )
4. Orders set aside — Matter remanded to IO to consider assessment order and offer cross-examination. (Para 34 , 35 , 36 )
5. Can a retracted confessional statement be the sole basis for a benami finding?
No, a retracted statement without an opportunity for cross-examination loses evidentiary value and cannot solely sustain a benami finding. (Para 27 )
6. Is denial of cross-examination of a foundational witness a violation of natural justice?
Yes, where an adverse finding is founded on a statement, denying cross-examination despite request is a serious infirmity violating natural justice. (Para 25 )
JUDGMENT :
Arun Monga, J.
INDEX
1. Introductory
2. Facts in chronological order
3. The proceedings below
A. Initiating Officer
B. Adjudicating Officer
C. Appellate Tribunal
4. The case of the appellant
A. Arguments on behalf of the Appellant
B. Further Submissions on behalf of the appellant
C. Case law cited on behalf of the appellant
5. Case of the respondents
A. Arguments on behalf of the respondents
B. Further Submissions of the Respondents
6. Discussion and analysis
A. Issues/ Questions involved
B. The Statutory Framework 33
C. The Material Relied Upon by the Initiating Officer
D. The Assessment Order dated 27.03.2026
E. Legal Position on Untested/Retracted Statement
F. Overlapping/Contradictory Findings of the IO and the AO
G. The Cumulative Infirmities
7. Findings
8. Answers to the questions of law
9. Conclusion/Order
I. INTRODUCTORY:-
1. Appellant company, engaged in the business of real estate development and sale/purchase of the properties, is before us, assailing, inter alia, an order dated 01.04.2026 passed by Appellate Tribunal under Section 46 of the Prohibition of Benami Property Transactions Act, 1988 (PBPT Act for short) whereby the Tribunal affirmed the order dated 30.08.2024 passed by the Adjudicating Authority under Section 26(3) of the PBPT Act holding 79 immovable properties purchased by the appellant to be benami properties.
2. The adjudicating authority (AA- for short) vide its order dated 30.08.2024 in turn upheld the final provisional attachment order dated 28.07.2023 passed under Section 24 (4)(a)(i) of the PBPT Act, 1988. Both these orders have also been impugned herein. Vide its attachment order, the Initiating Officer (IO- for short) prima facie opined that as many as 79 immovable properties purchased by the appellant were benami properties as defined under Section 2(9) of the PBPT Act, 1988. Directions are also sought that as a consequence of quashing the orders, ibid, the provisional attachment of the properties under PBPT Act be revoked and the properties be released in favour of the appellant.
3. The lis in hand, in fact, traces its origin to a search conducted on 16.06.2022 under Section 132 of the Income-tax Act, 1961 in the case of one Maharani Group. The material emerging from that search was treated by the IO as the foundation for initiating proceedings under Section 24 of the PBPT Act against the appellant-company. Pertinently, a finding that the properties are benami may ultimately expose the properties to confiscation under Section 27 of the PBPT Act and may also attract prosecution under Section 53 of the Act, thereby giving the present proceedings a serious civil and penal complexion.
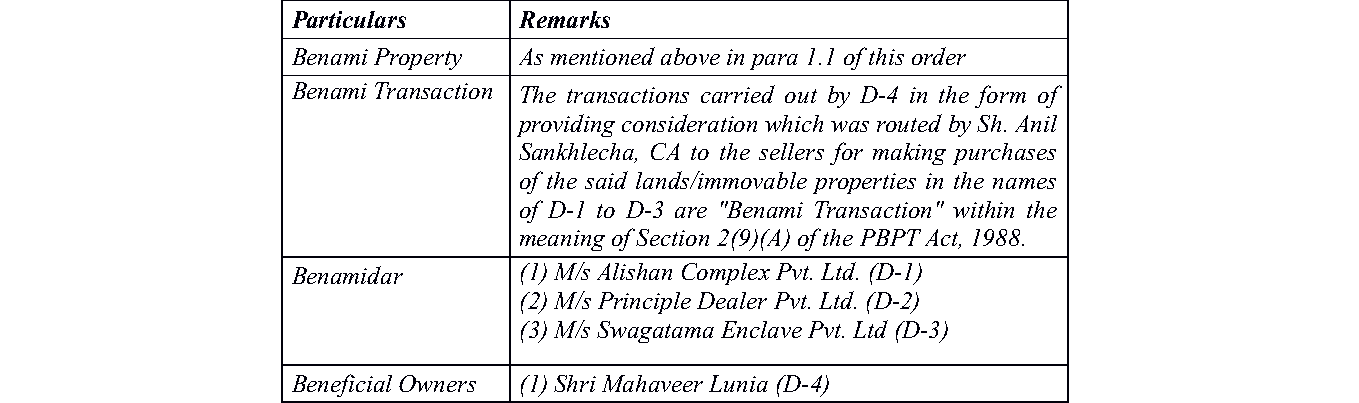
4. The appellant is a private limited company incorporated under the Companies Act, 1956, engaged in real estate development, including development of Special Economic Zones and industrial plazas, and in promoting and developing lands, buildings and townships. In the scheme of the allegations levelled by the Initiating officer under PBPT Act, it has been cast in the role of the benamidar i.e. the name-lender in whose name the subject properties stand.
5. The alleged beneficial owner is one Shri Mahaveer Lunia, founder and principal promoter of the Maharani Group, a Jodhpur-based handicrafts business. His connection with the appellant company is that he holds approximately 8.33% in each of two intermediary holding companies, translating to an indirect interest of roughly 4.17% in the appellant. He became a director of the appellant only on 06.01.2020, a date, it will be seen, that falls after the property purchases in question.
6. The Initiating Officer, the Respondent herein, is the Deputy Commissioner of Income Tax (Benami Prohibition), Benami Prohibition Unit, Jaipur. He functions within the same departmental structure i.e. the Central Board of Direct Taxes, as the Income-Tax authorities whose aassessment findings, in respect of the very same properties, the