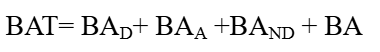1. Execution of an arbitral award — dispute over calculation of input-rate difference and entitlement to post-award interest under Section 31(7)(b), Arbitration and Conciliation Act, 1996. (Para 2 , 3 , 4 , 5 , 6 , 7 , 8 , 9 )
 Back
Next 


2026 Supreme(MP) 742
IN THE HIGH COURT OF MADHYA PRADESH AT JABALPUR
VIVEK RUSIA, PRADEEP MITTAL, JJ.
M/S Shyam Indus Power Solution Private Ltd. – Petitioner
Versus
Madhya Pradesh Madhya Kshetra Vidyut Vitran Co. Ltd. – Respondent
MISC. Petition No. 3672 of 2025 With MISC. Petition No. 1446 of 2025
Decided On : 05-01-2026
Important Points
Post-award interest under Section 31(7)(b) of the Arbitration and Conciliation Act, 1996, may be denied if the award fails to quantify the sum and no delay in payment is established. Calculations during execution must strictly adhere to the formulas and fixed values specified in the award/tender.
Subject
Arbitration - Execution of Award
Act Referred
Headnote
(A) Arbitration and Conciliation Act, 1996 - Sections 31(7)(b), 34, and 36 - Post-award interest - Section 31(7)(b) mandates the imposition of interest on a sum directed to be paid by an arbitration award unless the award otherwise directs interest at some other rate - Purpose is to ensure prompt payment by the award debtor once the award is made - However, where the award does not ascertain or quantify the amount and only declares entitlement as per Tender conditions, and there is no delay on the part of the debtor to make payment, the question of granting post-award interest does not arise. (Paras 23, 24)
(B) Execution of Award - Calculation of amounts - Where the Arbitral Tribunal upholds terms and conditions of a Tender Document for calculation, those formulas must be strictly applied during execution - If the formula specifies a base year tariff and an accepted input rate at the beginning of the distribution period, these remain fixed values and cannot be varied for every revision. (Paras 17, 20, 21)
Facts of the case:
An agreement was executed for the distribution of electricity. A dispute arose regarding the application of the Input Tax Formula, leading to an arbitral award in favor of the decree holder for an Input Rate difference and Capital Expenditure (CAPEX), with interest granted at 9.5% on a specific sum. In execution proceedings, the decree holder claimed a higher Input Rate difference and sought post-award interest at 18% per annum on the CAPEX amount under Section 31(7)(b) of the Arbitration and Conciliation Act, 1996. The executing court rejected the interest claim, holding that it should have been challenged under Section 34 of the Act. Both parties subsequently filed petitions under Article 227 of the Constitution challenging the executing court's order.
Findings of Court:
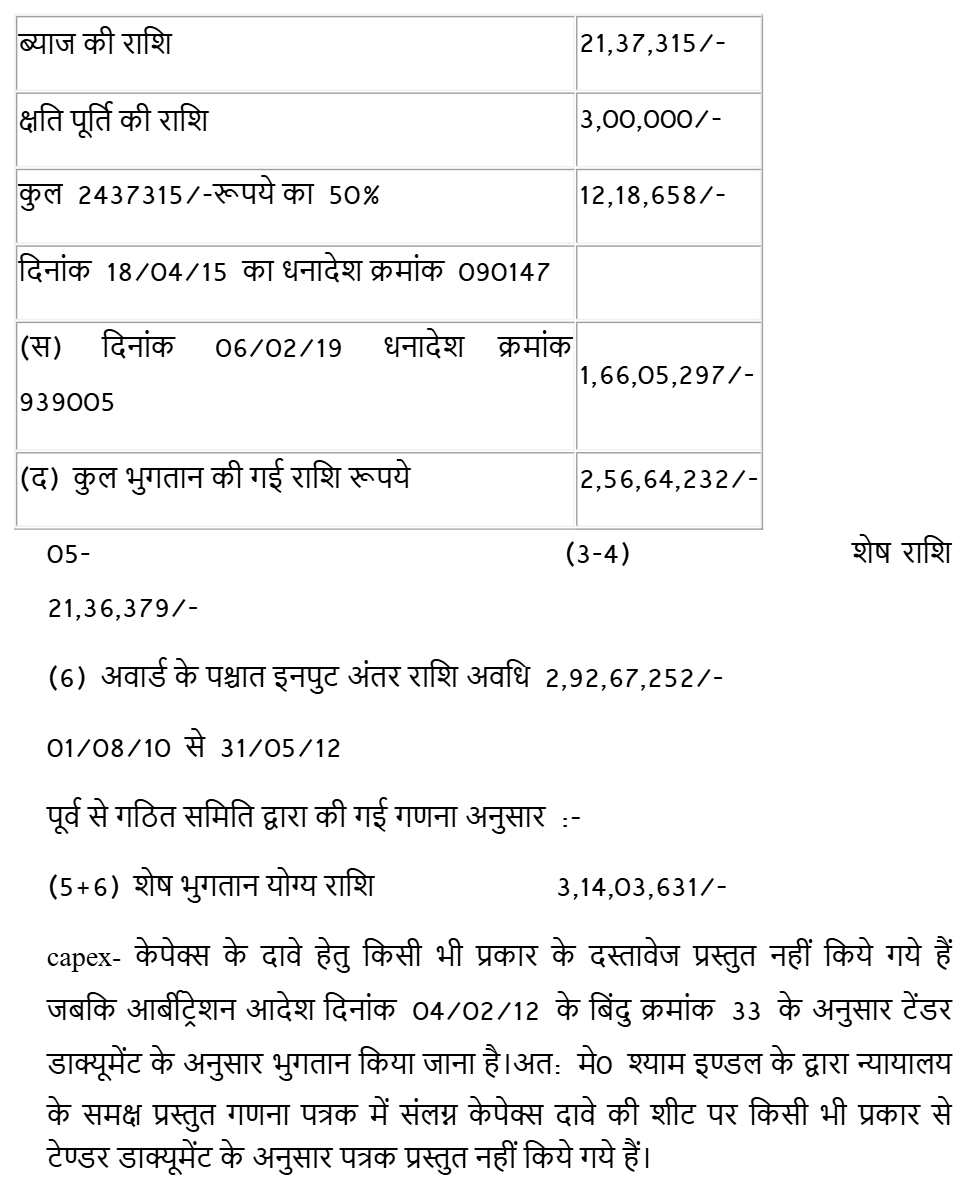
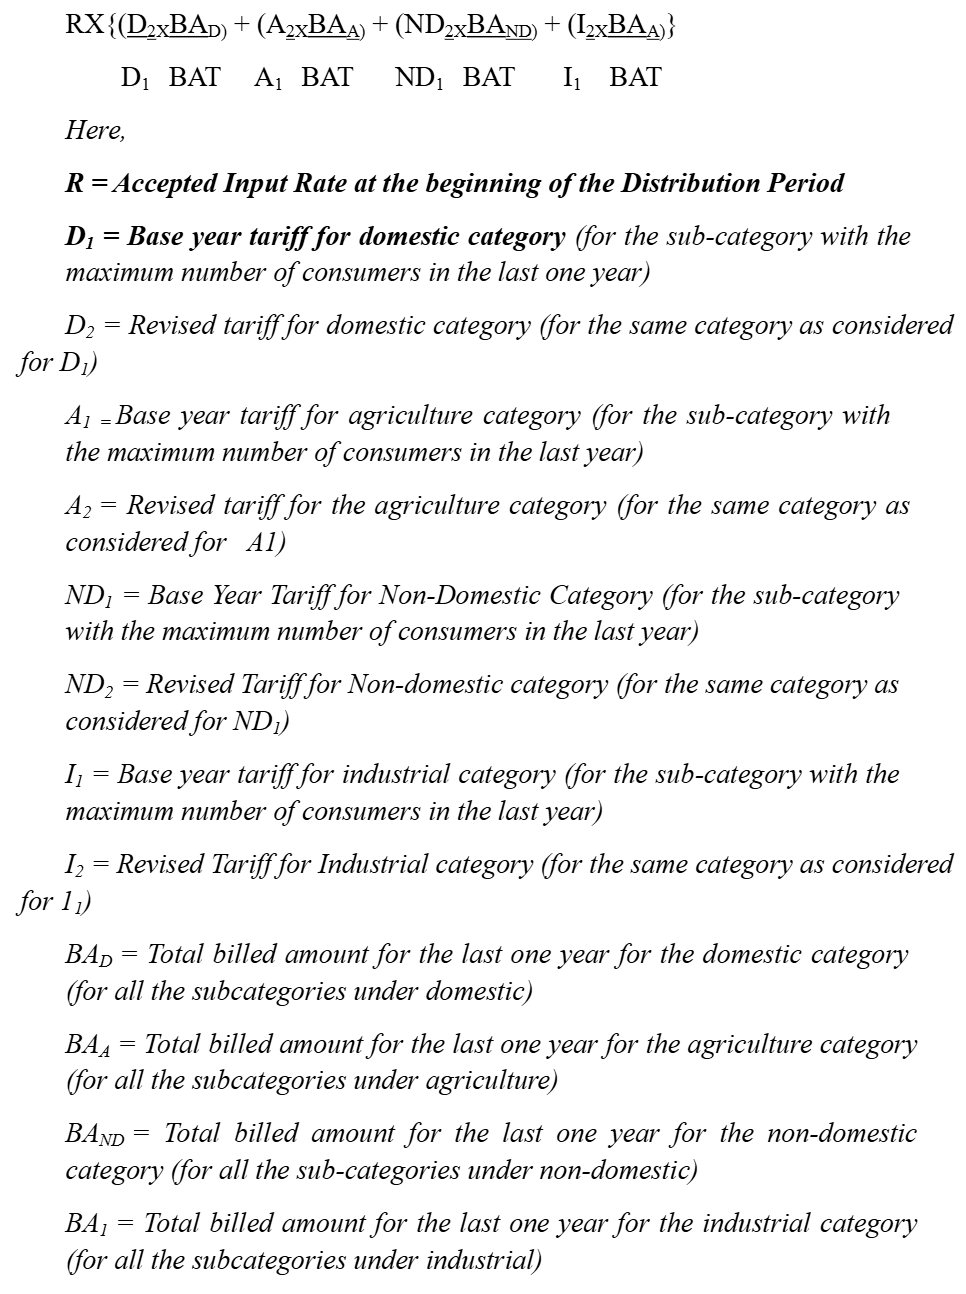
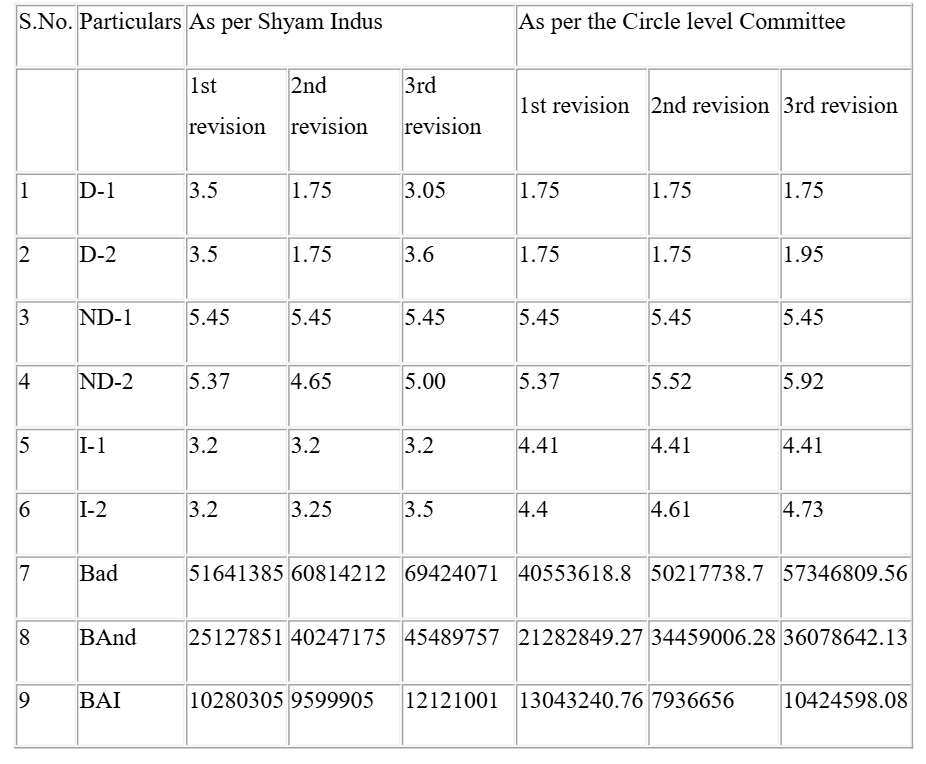
The court found that the Input Rate difference must be calculated using the formula in the Tender Document, where the base year tariff and original input rate are constant, thereby accepting the lower calculation submitted by the judgment debtor. Regarding the CAPEX amount, the court held that since the tribunal did not quantify the sum and there was no delay in payment, post-award interest under Section 31(7)(b) was not applicable.
Issues: 1. Whether the decree holder is entitled to post-award interest under Section 31(7)(b) of the Arbitration and Conciliation Act, 1996 on an unquantified CAPEX amount when the award is silent. 2. Whether the calculation of the Input Rate difference should follow a variable base year or a fixed base year as per the Tender Document.
Ratio Decidendi: The court reasoned that post-award interest is meant to penalize delay; since the CAPEX amount was not quantified by the award but referred to tender conditions, no delay in payment could be attributed to the debtor. Furthermore, the execution of the award must adhere to the tender's formula, which defines the base year and input rate as fixed values from the inception of the distribution period.
Result: Petitions disposed of with a direction that the Commercial Court/Executing Court shall ascertain the amount still payable by the Judgment Debtor as per award passed by the Arbitral Tribunal.
(B) Execution of Award - Calculation of amounts - Where the Arbitral Tribunal upholds terms and conditions of a Tender Document for calculation, those formulas must be strictly applied during execution - If the formula specifies a base year tariff and an accepted input rate at the beginning of the distribution period, these remain fixed values and cannot be varied for every revision. (Paras 17, 20, 21)
Facts of the case:
An agreement was executed for the distribution of electricity. A dispute arose regarding the application of the Input Tax Formula, leading to an arbitral award in favor of the decree holder for an Input Rate difference and Capital Expenditure (CAPEX), with interest granted at 9.5% on a specific sum. In execution proceedings, the decree holder claimed a higher Input Rate difference and sought post-award interest at 18% per annum on the CAPEX amount under Section 31(7)(b) of the Arbitration and Conciliation Act, 1996. The executing court rejected the interest claim, holding that it should have been challenged under Section 34 of the Act. Both parties subsequently filed petitions under Article 227 of the Constitution challenging the executing court's order.
Findings of Court:
The court found that the Input Rate difference must be calculated using the formula in the Tender Document, where the base year tariff and original input rate are constant, thereby accepting the lower calculation submitted by the judgment debtor. Regarding the CAPEX amount, the court held that since the tribunal did not quantify the sum and there was no delay in payment, post-award interest under Section 31(7)(b) was not applicable.
Issues: 1. Whether the decree holder is entitled to post-award interest under Section 31(7)(b) of the Arbitration and Conciliation Act, 1996 on an unquantified CAPEX amount when the award is silent. 2. Whether the calculation of the Input Rate difference should follow a variable base year or a fixed base year as per the Tender Document.
Ratio Decidendi: The court reasoned that post-award interest is meant to penalize delay; since the CAPEX amount was not quantified by the award but referred to tender conditions, no delay in payment could be attributed to the debtor. Furthermore, the execution of the award must adhere to the tender's formula, which defines the base year and input rate as fixed values from the inception of the distribution period.
Result: Petitions disposed of with a direction that the Commercial Court/Executing Court shall ascertain the amount still payable by the Judgment Debtor as per award passed by the Arbitral Tribunal.
Legal Category Hierarchy
- arbitration and conciliation
- electricity law
-
constitutional law
-
supervisory jurisdiction
- article 227 (Para 2)
-
supervisory jurisdiction
Advocates Appeared:
For the Petitioner:Shri Somesh Shukla, Advocate appearing on behalf of Shri Pankaj Kumar Singh, Advocate.
For the Respondents:Shri Bharat Singh with Shri Harpreet Singh Gupta and Shri Manan Agrawal, Advocate.
For the Petitioner:Shri Somesh Shukla, Advocate appearing on behalf of Shri Pankaj Kumar Singh, Advocate.
For the Respondents:Shri Bharat Singh with Shri Harpreet Singh Gupta and Shri Manan Agrawal, Advocate.
Table of Contents
2. Decree holder claims statutory post-award interest and its calculation of input-rate difference; judgment debtor asserts fixed base-year formula and denies interest on CAPEX. (Para 11 , 12 , 13 , 14 , 15 , 16 )
3. Petitions disposed of; executing court directed to ascertain the amount still payable by the judgment debtor under the arbitral award. (Para 25 )
4. Is factor D1 in Clause 35.4.1 of a tender document fixed for every tariff revision when the base year refers to the first year of the distribution period?
Yes. The accepted input rate R and base-year factor D1 remain fixed for the entire distribution period; tariff revisions under the tender formula do not change the base year, and calculation must follow the tender formula upheld by the award. (Para 17 , 18 , 19 , 20 , 21 )
5. If an arbitral award is silent on post-award interest, does Section 31(7)(b) of the Arbitration and Conciliation Act, 1996 mandate interest on sums directed to be paid?
Yes. Section 31(7)(b) mandates post-award interest at 18% per annum (now 2%) on a sum directed to be paid by the award unless the award otherwise directs a different rate; the provision is intended to ensure prompt payment. (Para 22 , 23 , 24 )
6. Can statutory post-award interest under Section 31(7)(b) be claimed on an amount that the arbitral award did not ascertain or quantify?
No. Where the award merely declares entitlement to an unascertained CAPEX amount and the executing court has not quantified it, the judgment debtor cannot be said to have delayed payment, so no statutory post-award interest is payable on that amount. (Para 24 )
ORDER :
Vivek Rusia, J.
M/s Shyam Indus Power Solutions Pvt. Ltd/Decree Holder has filed M.P. No.3672/2025 under Article 227 of the Constitution of India, challenging the order dated 27.03.2024 passed by the VIII Additional District and Sessions Judge, Commercial Court, Bhopal in case No.EX AB 275/2021.
2. The Madhya Pradesh Madhya Kshetra Vidyut Vitaran Co. Ltd. (MPMKVVCL)/Judgment Debtor has also filed M.P. No.1446/2025 under Article 227 of the Constitution of India, being aggrieved by the order dated 27.03.2024 passed by the learned 10th Additional District Judge, Bhopal (M.P.) in EX No.37404/2024.
Facts of the case, in short, are as follows:-
3. The Madhya Pradesh Madhya Kshetra Vidyut Vitaran Co. Ltd. (MPMKVVCL/Judgment Debtor)is a wholly State Government Company registered under the provisions of the Indian Companies Act, 1956, engaged in the activities of distribution and retail supply of electricity and power within the areas covered by the Commissioner, Bhopal, Hoshangabad, Gwalior, and Chambal. The electricity Company invited tender on 27.07.2007 for the distribution of electricity for Chhola Zone of the City Division (North), Bhopal vide Specification No.ACE/CC/05/2007/DP/3437. M/s. Shyam Indus Power Solutions Pvt. Ltd. (hereinafter referred to as Decree Holder) submitted a tender for the above work, and the same was accepted by the MPMKVVCL/Judgment Debtor. An agreement was executed between the MPMKVVCL/Judgment Debtor and Decree Holder on 22.12.2007 for a period of five years from 01.02.2008 to 31.05.2012. During the currency of the contract period, a difference/dispute arose between the parties over the application of the Input Tax Formula.
4. The MPMKVVCL/Judgment Debtor calculated and recovered Input Tax Formula on the basis of terms and conditions of the agreement, whereas M/s. Shyam Indus claimed Input Rate on the basis of the tender documents. In view of the arbitration Clause 21.1.6 in the NIT, arbitration proceedings were commenced before Shri S.K. Dubey, retired Judge of this Court, as Presiding Arbitrator and two other Arbitrators (hereinafter referred to as the Arbitral Tribunal). Decree Holder filed a statement of claims on 04.09.2010, and MPMKVVCL/Judgment Debtor denied the claims by filling written statement.
5. The learned Arbitrator Tribunal passed an award in favour of M/s. Shyam Indus/Decree Holder. The operative part of the arbitral award dated 04.02.2012 is reproduced below:-
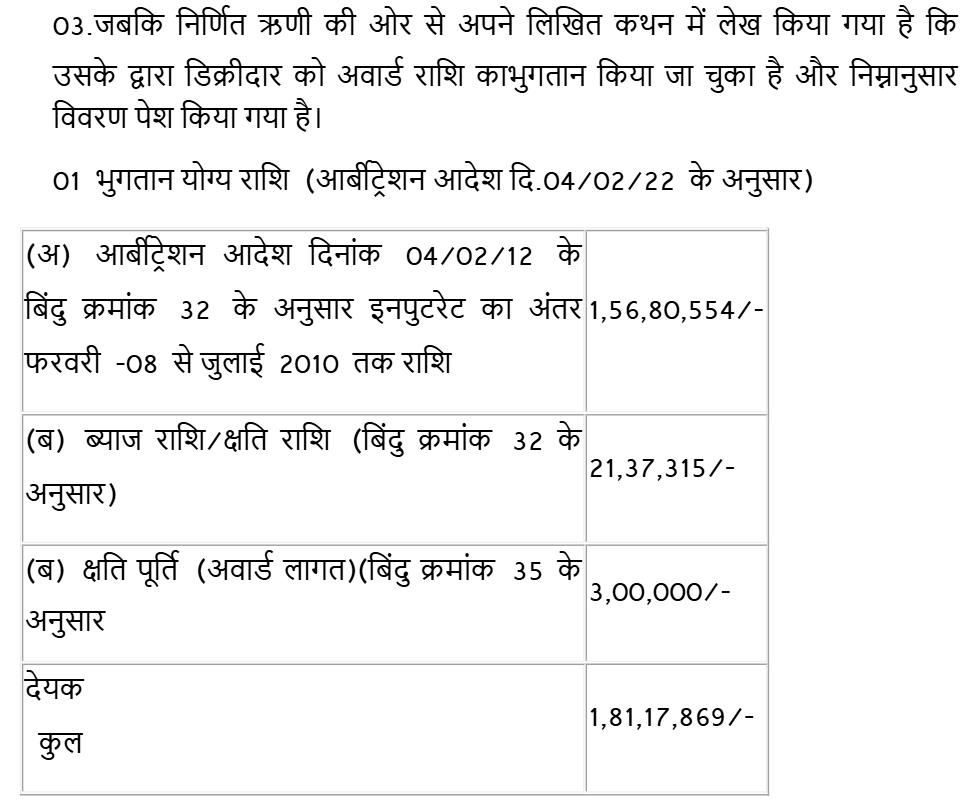
32. As an upshot, the Claimant is entitled to the amount of Rs. 1,56,80,554/ calculated from the inception till 31.07.2010 and interest/losses thereon of Rs. 21,37,315/- and thereafter the difference in realizing the excess amount of the Input Rate on the date of the completion of the period of the Distribution Agreement.
33. The Claimant would also be entitled in the amount of CAPEX the scheme/s as submitted by the Claimant in accordance with the original terms relating to CAPEX as contained in the Tender Document and as such, on expiry of period of contract whatever benefits of the Capital Expenditure would be available on calculation in the manner provided in the Tender Document the claimant would be entitled for the same.
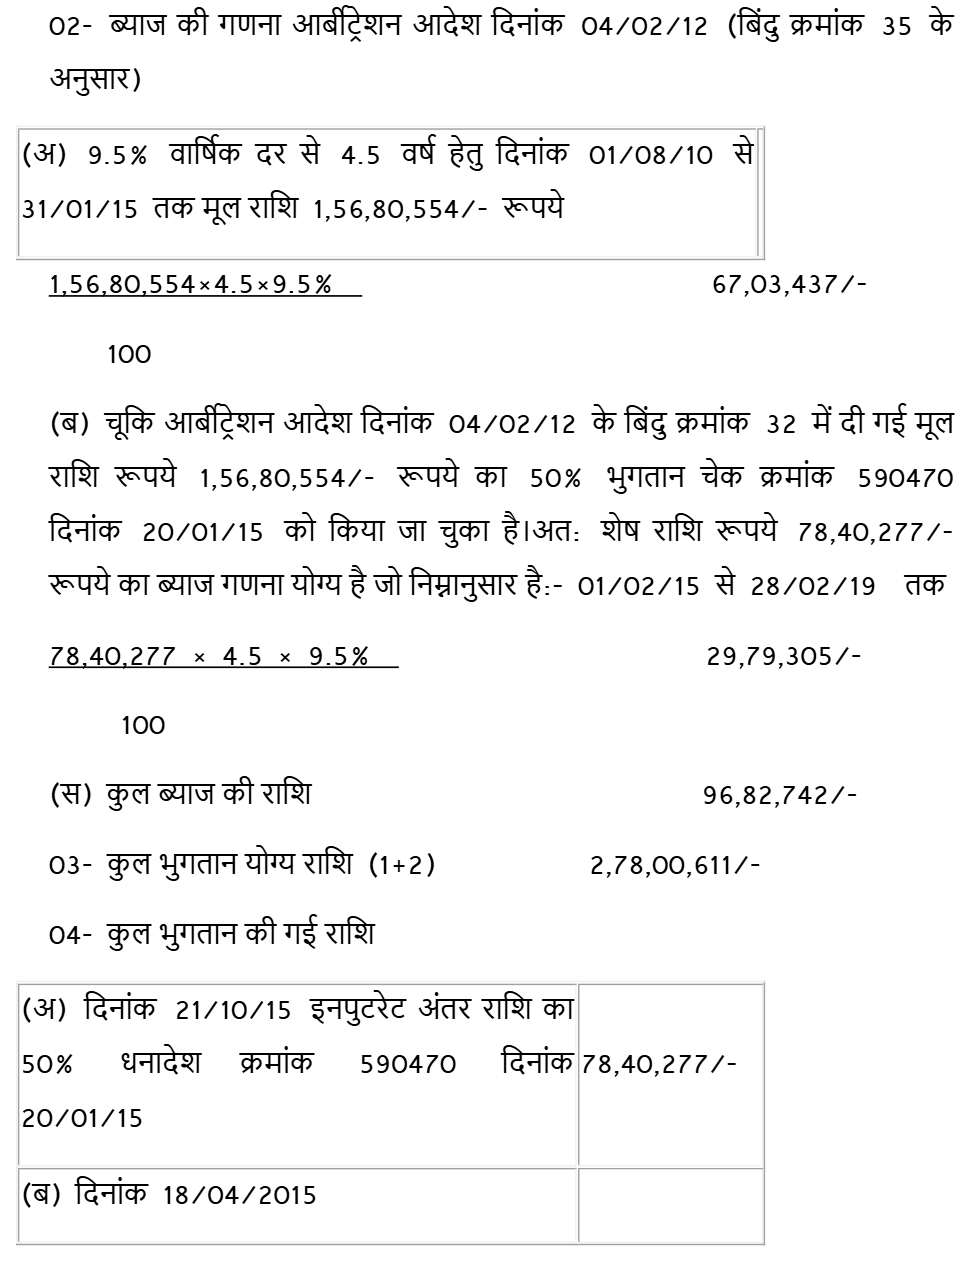
34. As regards interest on the amount so charged in excess, in the circumstances of this case, the Claimant would be entitled to interest 912% per annum on the amount of Rs.1,56,80,554/- from 01.08.2010 till its payment.
6. By the aforesaid award, the learned Arbitrator Tribunal awarded (a) Rs.1,56,80,554/- as an excess amount of Input Rate from date of inception till 31.07.2010, (b) interest/losses thereon of Rs.21,37,315/- (c) difference of the said amount of Input Rate from 01.08.2010 till completion of the period of the Distribution Agreement,(d) CAPEX (Capital Expenditure) in accordance with the original terms relating to CAPEX in the Tender Document on expiry of contract period, (e) the interest @ of 9.5% per annum on the amount of Rs.1,56,80,554/- from 01.08.2010 till its payment and (f) cost of Rs.3,00,0