
 Back


IN THE HIGH COURT OF ANDHRA PRADESH AT AMARAVATI
R Raghunandan Rao, T.C.D.Sekhar, JJ.
Jawaharlal Nehru Technological University Kakinada (Jntuk), Represented By Its Registrar - Petitioner
Versus
The Princiapl Commissioner Of Central Tax - Respondent
W.P.No.23535, 31934 of 2023, 7867 and 26414 of 2025 and W.P.9123 of 2026
Decided On : 27-04-2026
ORDER:
R. Raghunandan Rao, J.
As the issues raised in all these Writ Petitions are common, they are being disposed of, by way of this common order.
2. The petitioners, in all these Writ Petitions are Public Universities, established by the State of Andhra Pradesh, by way of different Acts. All these Universities have suffered orders of assessment, calling upon the petitioners to pay GST on the affiliation fees and No Objection Certificate (NOC) fees received by these Universities, from their affiliated colleges. The details of the orders of assessment etc., are given herein below:S.No. W.P.No. Name of the University Period of Assessment Date of Order of Assessment
| S.No. | W.P No | University | Date Range | Submission Date |
|---|---|---|---|---|
| 1 | W.P 23535 of 2023 | Jawaharlal Nehru Technological University Kakinada (JNTUK) | 01/07/2017 to 31/03/2020 | 06/06/2023 |
| 2 | W.P 31934 of 2023 | Acharya Nagarjuna University | 01/07/2017 to 31/03/2022 | 25/08/2023 |
| 3 | W.P 7867 of 2025 | Adi Kavi Nannayya University | 01/07/2017 to 31/03/2022 | 19/11/2024 |
| 4 | W.P 26414 of 2025 | Vikrama Simhapuri University | 01/04/2019 to 31/03/2025 | 03/09/2025 |
| 5 | W.P 9123 of 2026 | Krishna University | 01/04/2018 to 31/03/2024 | 01/12/2025 |
3. The petitioners have been established under different Acts. The details of these Acts are given below:
| Sl.No. | W.P.No. | Name of the University | The Act under which the University has been established |
|---|---|---|---|
| 1 | W.P 23535 of 2023 | Jawaharlal Nehru Technological University Kakinada (JNTUK) | Jawaharlal Nehru Technologies University act, 2008 |
| 2 | W.P 31934 of 2023 | Acharya Nagarjuna University | Andhra Pradesh Universities Act, 1991 |
| 3 | W.P 7867 of 2025 | Adi Kavi Nannayya University | Andhra Pradesh Universities Act, 1991 |
| 4 | W.P 26414 of 2025 | Vikrama Simhapuri University | Andhra Pradesh Universities Act, 1991 |
| 5 | W.P 9123 of 2026 | Krishna University | Andhra Pradesh Universities Act, 1991 |
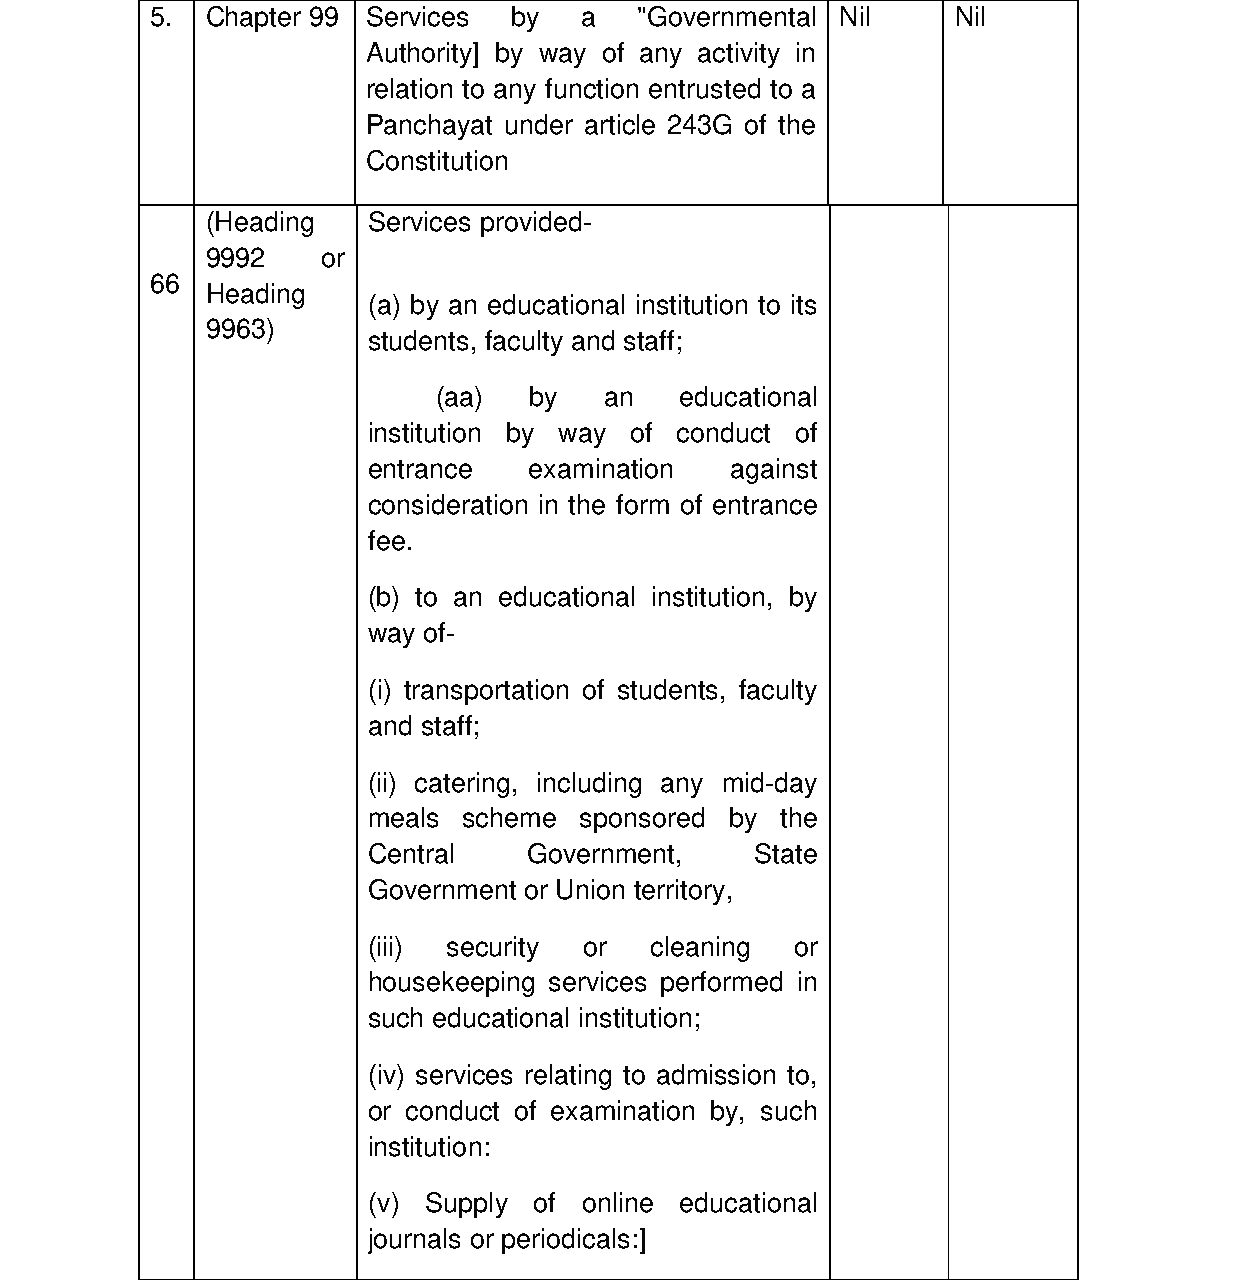
4. The assessing authorities in all these cases have sought to tax the receipt of affiliation fees and N.O.C fees, under the GST Act, on the ground that the fees had been paid for services rendered by the respective Universities and the same is taxable under the GST Act. The petitioners had objected to the said taxation, on the ground that they are universities incorporated under the respective Acts, passed by the Andhra Pradesh State Legislature and the affiliation fee and statutory fee collected by them is in discharge of statutory functions which cannot be treated as supply of services in the course of business activity. The petitioners also took the stand that these fees would fall under Entry No.66 of GST exemption notification No.12 of 2017, dated 28.06.2017, and as such, no GST can be levied on supply of such services. The assessing officers rejected these contentions on the ground that any supply of service, even if it is a supply of service, in pursuance of statutory function, would be taxable, in view of the provisions of the GST Act. The Assessing Officer further held that the petitioners are not entitled to the exemption set out under Entry No.66 of Notification 12 of 2017 on the ground that the supply of service of affiliation and issuance of No Objection Certificates do not fall within the ambit of Entry No.66 of Notification 12 of 2017.
5. Various ancillary issues on the question of whether Section 74 of the GST Act can be invoked, against the petitioners have also been raised. All the aforesaid orders are now under challenge in the present Writ Petitions.
6. Heard Sri C. Raghavan Ramabhadran, Sri Shaik Jeelani Basha, Sri S. Suri Babu, Sri C. Sanjeeva Rao, learned counsel appearing for the Petitioners and Smt. Shanti Chandra, learned Standing Counsel appearing for the Respondent.
7. In order to consider the contentions raised by the petitioners, it would be appropriate that the facts relating to one case be taken up for consideration. Accordingly, the petition in W.P.No.23535 of 2023 is being taken up for consideration. It may also be noted that the contentions raised by the petitioners are essentially the same.
8. Sri C. Raghavan Ramabhadran, the learned counsel appearing fo


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


