
 Back


IN THE HIGH COURT OF ANDHRA PRADESH AT AMARAVATI
R RAGHUNANDAN RAO, T.C.D.SEKHAR, JJ.
M/s. Sangeetha Sudha Mobile World – Petitioner
Versus
State Of Andhra Pradesh, Rep By Its Principal Secretary, Revenue(Ct) Department – Respondent
Writ Petition Nos: 15649, 15672, 15699, 15776, 16520, 22262, 24485, 24731, 26985, 27011, 33706 Of 2018, 6129, 6130, 8186, 8204, 19514, 19534, 20971 Of 2019, 1896 Of 2020, 10859 And 18442 Of 2022
Decided On : 29-04-2026
ORDER :
R. Raghunandan Rao, J.
Heard Sri M.V.J.K.Kumar, the learned counsel for the petitioners and the learned Government Pleader for Commercial Tax appearing for the respondents.
2. As all these writ petitions raised the same issues, they have been disposed of by way of this common order.
3. The petitioners are all manufacturers or dealers in Cell phones and Cell phone equipment. During the period 2011-2012 to 2016-2017, these petitioners had been taxed, under the Andhra Pradesh Value Added Tax Act, 2005 (for short, ‘the APVAT Act’) for the sale of such Cell phones and Cell phone equipments. The details of the assessment as well as the penalties in certain cases and appeals in certain cases are given herein below:
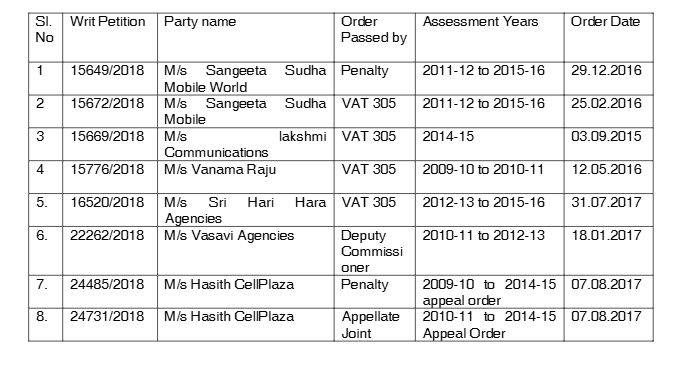
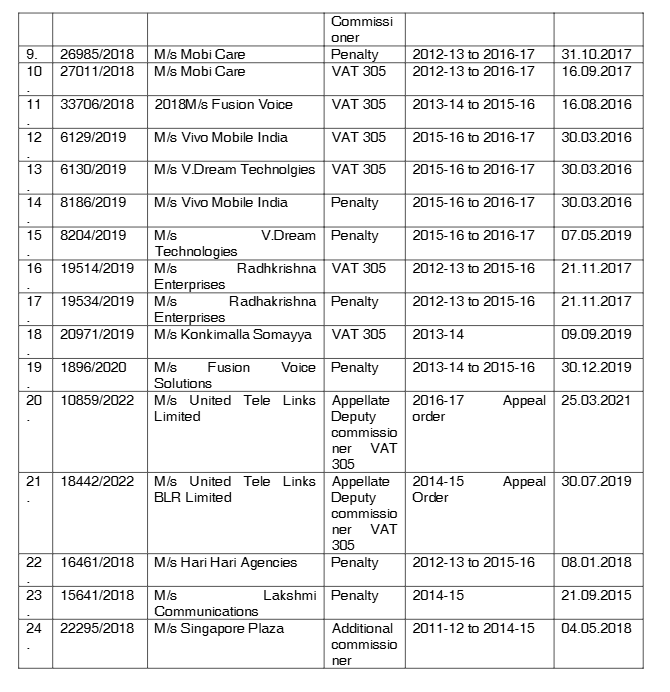
4. In all these cases, the goods which were sold, were Cell phones, Cell phone batteries and Cell phone battery chargers and head phones in some cases. All these good were put together and sold in one unit and a composite price was received for sale of these products. The assessing authorities as well as the Appellate authorities took the view that the sales, made by the petitioners, were sales of three separate goods namely Cell phones, Cell phone batteries and Cell phone chargers and in some cases head phones. On that basis, the authorities sought to levy the Value Added Tax, at different rates for these different products. The petitioners contended that all the said products, which were sold us one component and could not have been bifurcated into separate products and separate rate could not have been levied on the products.
5. As the authorities did not accept these contentions, the petitioners after having suffered orders of assessment, orders of penalty as well as the appellate orders and revisional orders have approached this Court, by way of the above writ petitions.
6. Before going into the contentions raised by either side, it would be necessary to review the facts leading to the present set of writ petitions.
7. The APVAT Act, which was brought into effect from 01.04.2005, stipulated the rate of tax on every product enumerated in the schedules attached to the said Act. There was also a residuary entry in schedule VII fixing a uniform rate of tax, for those which were not enumerated in the goods. Cell phones, were covered under Entry 39 (15 of the Schedule-IV) to the APVAT Act which reads as follows, prior to the amendment.
" (15) Transmission apparatus other than apparatus for radio broadcasting or TV broadcasting, transmission apparatus incorporating reception apparatus, digital still image video cameras "
8. There was a dispute as to whether Cell phone chargers should be treated as being a part of the Cell phones which would require sale of Cell phone battery chargers to be taxed at the same rate as that of Cell phone. This dispute was resolved by the Hon’ble Supreme Court in the case of The state of Punjab and Ors vs. Nokia India Pvt Ltd., AIR 2015 SC 1068. Inthis judgment, the Hon’ble Supreme Court after reviewing the law on the question of what would constitute parts of the main product had held that Cell phone battery charger cannot be treated as part of the Cell phone. Thereafter, on the representation of the various Industry body, the Central Government had issued a office Memorandum, dated 30.11.2015, in which the States were advised to treat the Cell phone batteries and chargers to be the part of the Cell phones and to tax them at one rate. Thereafter, the Government of Andhra Pradesh issued G.O.Ms.No.307, Revenue (CT-II) Department, dated 12.07.2016. By virtue of this G.O., entry 39 (15) of Schedule-IV of the APVAT Act was modified as follows:
Amendment
In Schedule-IV appended to the said Act, in entry 29, for sub-entry (15), the following shall be substituted, namely, -
"(15) Transmission apparatus other than apparatus for radio broadcasting or T.V. broadcasting, transmission apparatus incorporating reception apparatus including Cell phones, Cell Phone Batteries and Cell Phone Battery Chargers, digital s


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


