Back


2026 Supreme(Online)(ATFP) 207
APPELLATE TRIBUNAL FOR FORFEITED PROPERTY
M/s Shantilal Khusaldas & Bros Pvt. Ltd. Shri Arjun A Salgocar v. The Special Director Directorate of Enforcement Mumbai
FPA-FE-69/MUM/2018 FPA-FE-75/MUM/2018
Under FEMA, commission paid by an overseas buyer directly to an overseas agent does not form part of the full export value and is not required to be repatriated, as there is no loss of foreign exchange and no entitlement of the exporter.
Headnote:(A) Foreign Exchange Management Act, 1999 - Sections 7, 8, 42(1) - Foreign Exchange Management (Export of Goods and Services) Regulations, 2000 - Regulations 3, 9, 13 - Customs Act, 1962 - Section 127J - RBI Master Circular on Export of Goods and Services - Non-realisation of export proceeds - Commission paid by overseas buyer to overseas agent - Whether such commission forms part of full export value and requires repatriation - Whether Section 127J bars FEMA proceedings after settlement under Customs Act - Applicability of hearsay evidence - Penalty for alleged contravention - No loss of foreign exchange.
(B) The Tribunal held that commission paid by the overseas buyer directly to the overseas agent, without any payment by the exporter, does not constitute part of the "full export value of goods" under Section 7 of FEMA nor foreign exchange "due or accrued" under Section 8. The exporter has no right to receive or claim such commission. Even if the commission were deemed part of the export value, it would be a permissible deduction and would ultimately be payable to the agent, resulting in no loss of foreign exchange. Accordingly, no contravention arises.
(C) Section 127J of the Customs Act does not prohibit the Directorate of Enforcement from initiating independent proceedings under FEMA based on evidence collected during investigation, as FEMA is a self-contained code. The settlement order under Customs does not bar FEMA proceedings if independent evidence exists.
(D) Statement of a director who had no personal knowledge of transactions occurring before his appointment is hearsay and cannot be relied upon without corroboration. Selective reliance on such statements while ignoring the statement of the director who was actually in charge at the relevant time is unsustainable.
Facts of the case:
The appellant company exported iron ore during 2008-2012. An overseas agent was involved, and the overseas buyer paid commission directly to the agent. The Directorate of Enforcement alleged that this commission should have been included in the declared export value and repatriated to India, and that the company failed to realize full export proceeds. The Adjudicating Authority imposed penalties of Rs. 11 crore on the company and Rs. 1 crore on its director. The Settlement Commission under Customs had earlier passed an order on the same facts. The Tribunal considered appeals against the penalty order.
Findings of Court:
The Tribunal allowed the appeals, setting aside the penalties. It found that the commission amount was not paid by the exporter, nor was the exporter liable to pay it. There was no under-invoicing or loss of foreign exchange. The second charge regarding short realization of export proceeds had already been dropped by the Adjudicating Authority. The evidence relied upon was hearsay and lacked corroboration.
Issues: (i) Whether Section 127J of Customs Act prohibits reopening of proceedings under FEMA on same facts; (ii) Whether parameters for valuation under Customs Act apply to 'full export value' under FEMA; (iii) Whether commission paid by overseas buyer to overseas agent is required to be repatriated by exporter under Sections 7 and 8 of FEMA; (iv) Whether the Master Circular applies when no payment made by exporter; (v) Whether selective reliance on statements of a director with no personal knowledge is valid; (vi) Whether FEMA can be applied extraterritorially to transactions between non-residents; (vii) Whether penalty is disproportionate.
Ratio Decidendi: Under FEMA, only the amount which the exporter has a right to receive or claim constitutes 'full export value' or 'foreign exchange due'. Commission paid by a foreign buyer to a foreign agent, without involvement of the exporter, does not fall within these terms. Even if the commission were routed through India, it would be a permissible deduction and not result in any leakage of foreign exchange. Therefore, there is no contravention of Sections 7 and 8 of FEMA or the Export Regulations. Result : Appeals allowed. Impugned order imposing penalties set aside. Pre-deposit, if any, to be returned.
FINAL ORDER
25.03.2026
Dictated By: Rajesh Malhotra
Present Appeals u/s 19 of the Foreign Exchange Management Act, 1999 are filed by the Appellants against the Order dated 24.07.2018 passed by the Ld. Special Director, Directorate of Enforcement, Mumbai vide which penalties were imposed on the Appellants as under:
i) M/s Shantilal Khusaldas & Bros Pvt. Ltd., ₹ 11 Crore
ii) Shri Arjun Salgaokar, Director ₹ 1 Crore
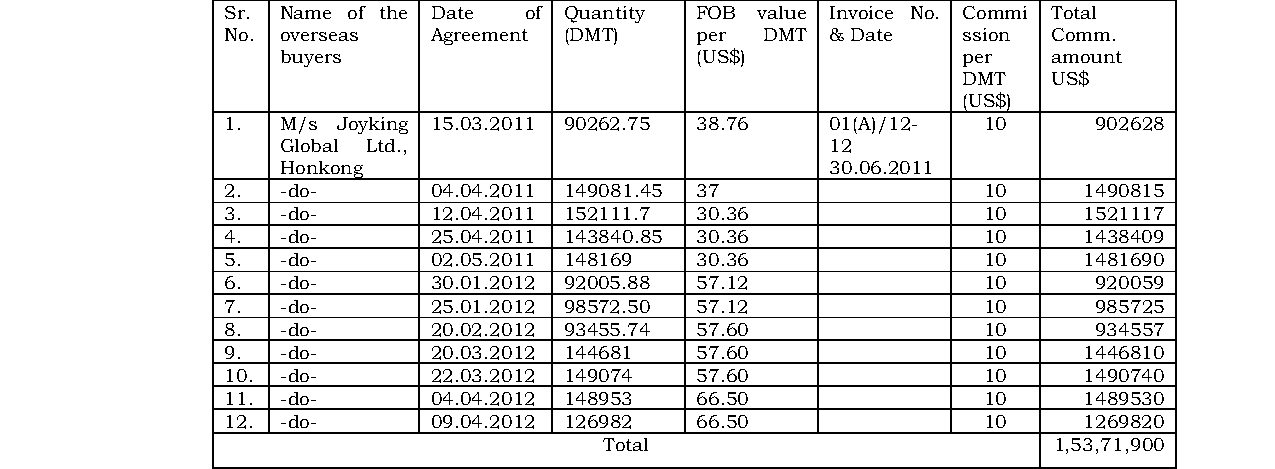
The said penalties were imposed for non-realisation of export proceeds amounting to US $ 1,53,71,900.
2. As per the facts of the case, Show Cause Notice dated 01.06.2017 was issued to the noticee (herein appellants) on the following grounds:
(i) For contravention of the provisions of section 7 & 8 of FEMA 1999 read with paras 3, 9 & 13 of Foreign Exchange Management (Export of Goods and Services) Regulation, 2000, issued in exercise of the powers conferred by clause (a) of sub-section (1) and sub-section (3) of section 7 and sub- section 2 of section 47 of FEMA 1999, against (1) M/s Shantilal Khusaldas & Bros. Pvt. Ltd.(Noticee No.1) to the extent of US$ 1,53,71,900 (Equivalent to Rs. 72,48,34,766/-), for failing to furnish the true and correct material particulars, including the amount representing the full export value of the goods exported, in the relevant export documents covering 12 export consignments and further, failing to take all reasonable steps to realize said export proceeds amounting to US$ 1,53,71,900 which represented the quantum of amount under-invoiced in the exports made by M/s Shantilal Khusaldas & Bros. Pvt. Ltd. which were due to be received by them in India, as being the part of the full export value of the goods, and further for doing or refraining from doing anything, or taking, or refraining from taking any action to ensure the realization of the said amount, being part of the export proceeds within the stipulated period, without the permission of RBI, as per specific details given in the complaint.
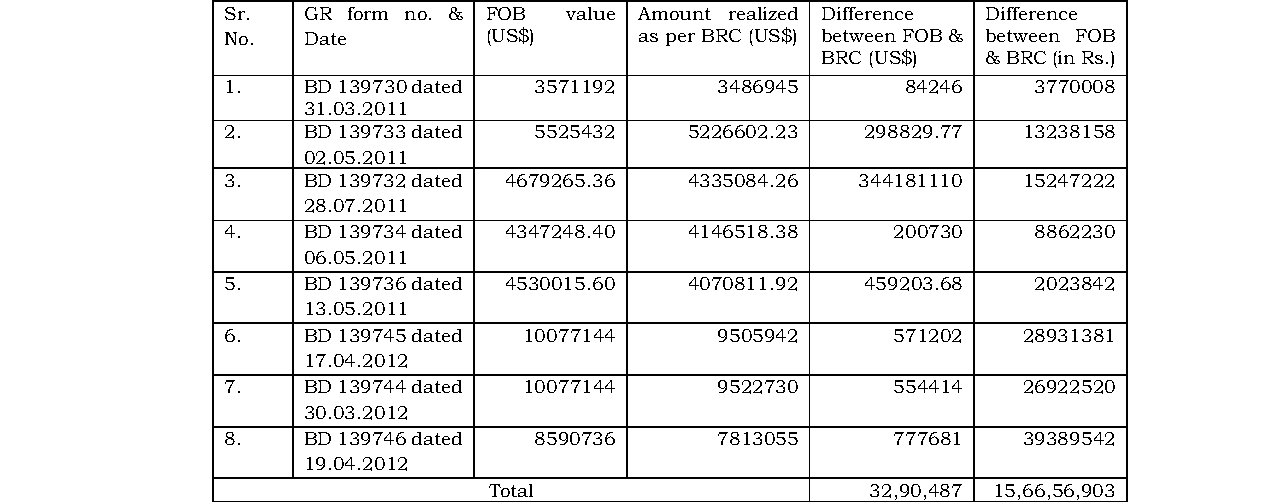
(ii) Contravention of the provisions of section 7 & 8 of FEMA 1999 read with paras 3, 9 & 13 of Foreign Exchange Management (Export of Goods and Services) Regulation, 2000, issued in exercise of the powers conferred by clause (o) of sub-section (1) and sub-section (3) of section 7. sub-section 2 of section 47 of FEMA 1999, against M/s Shantilal Khusaldas & Bros. Pvt. Ltd. (Noticee No.1) Ores Pvt Ltd., for failing to take all reasonable steps to realize the export proceeds amounting to US$ 32,90,487 (Equivalent to Rs 15,66,56,903/-), covered under 8 export consignments and further, doing or refraining from doing anything, or taking, or refraining from taking any action to ensure the realization of the said export proceeds within the stipulated period, without the permission of RBI, as per specific details given in the complaint.
iii) Shri Arjun Salgacar (Noticee No.2), Director of M/s Shantilal Khusaldas & Bros. Pvt. Ltd. being the person in-charge and responsible for the conduct of business of M/s Shantilal Khusaldas & Bros. Pvt. Ltd. was also charged in terms of section 42(1) FEMA for the contraventions alleged against M/s Shantilal Khusaldas & Bros. Pvt. Ltd. Ores Pvt. Ltd., as mentioned at S1.No (i) to (ii) above.
The SCN was issued to the aforesaid noticees by the Adjudicating Authority after taking notice of charges framed in a complaint bearing No. T-3/31-Goa/2015 dated 7.4.2017 filed against them by the complainant under section 16(3) of FEMA 1999. Brief facts of the case, leading to filing of the subject complaint, and the resultant issue of SCN, are given as under:-
FACTS OF THE CASE:
Specific information was received from the Directorate of Revenue Intelligence (DRI) informing that the Noticee Company had been evading custom export duty in their export of iron ore by undervaluing iron ore exported from the Panaji Minor Port, Goa. It was further informed that the DRI, Mumbai had conducted investigation in the matter and on conclusion of the investigation, DRI Mumbai had issued a Show Cause cum Demand