Back


2025 Supreme(Online)(CESTAT) 16
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
SOMESH ARORA, J, SATENDRA VIKRAM SINGH, Technical Member
Gulshan Exim Private Limited – Appellant
Versus
C.C.-Mundra – Respondent
Customs Appeal No. 10098 of 2024|Customs Appeal No. 10099/2024|Customs Appeal No. 10440/2024|Customs Appeal No. 10463/2024|Customs Appeal No. 10464/2024
For the Appellants/Petitioners: Shri Ajay Jain
For the Respondents: Shri Jaspreet Singh Sukhija
Classification of low-nickel austenitic stainless steel contentious; COO discrepancies under trade agreements liberally construed as procedural vs substantive; no extended limitation on importer-provided documents; remanded for fresh determination.
Headnote:(A) Customs Act, 1962 - Sections 111(m), 112(a), 112(b), 114A, 114AA, 117, 28(4), 28(9) - Customs Tariff Act, 1975 - Chapter Headings 7220 9022, 7220 9090 - Notification No. 50/2018-Cus - Classification of cold rolled stainless steel strips (low nickel, high manganese, chromium present) claimed as 'Nickel Chromium Austenitic type' - Department reclassified under 7220 9090 denying exemption, confirmed differential duty, interest, confiscation and penalties - Tribunal observed contentious classification issue involving chemical composition, permitted processes under explanatory notes (annealing, descaling, skin pass), surface finish grades; discrepancy in COO certificates (exporter name mismatch with invoice) requiring scrutiny if procedural or substantive - Invocation of extended period not upheld as SCN based on importer's documents - Matter remanded for fresh determination of classification, COO validity under liberal construction of trade agreement rules, duty/interest sans extended period, and penalties. (Paras 6.1 to 6.9)
(B) Asia-Pacific Trade Agreement Rules, 2006 - Certificate of Origin - Discrepancy between exporter name in COO (column 1) and commercial invoice - Notes require exporter name in invoice to match - Beneficial trade promotion rules warrant liberal construction; remand to assess if mere procedural infraction or substantive lapse denying concessional benefits. (Paras 6.3, 6.4, 6.8)
(C) Classification - Stainless steel - Scope of 'not further worked' under Chapter 72 headings - Includes borrowed processes from explanatory notes (annealing, descaling, pickling, skin pass for 2B finish); permits mechanical working, surface treatments - Exact nature determined by processes undergone, grade, composition beyond party/department proposals. (Para 6.6)
Facts of the case:
Importers filed appeals against orders reclassifying imported cold rolled stainless steel coils/strips (J-3 grade, low nickel ~1%, high manganese, chromium ~13%) from 7220 9022 to 7220 9090, denying 45% exemption, confirming duty/interest/penalties/confiscation; some COO rejected for exporter name mismatch (China manufacturer vs Hong Kong supplier).
Findings of Court:
Classification contentious requiring examination of composition, grade, permitted processes; COO discrepancies to be viewed liberally under trade rules; no extended period; remanded for fresh adjudication on classification, COO, duty/interest/penalties.
Issues: Correct classification of low nickel austenitic stainless steel; validity of COO certificates; invocability of extended limitation; quantum of penalties.
Ratio Decidendi: Classification demands scrutiny of technical aspects like composition, processes within explanatory notes' ambit; trade preferential rules liberally construed distinguishing procedural from substantive COO flaws; demands based on importer documents preclude extended period.
Result: Appeals disposed by remand.
| Table of Content |
|---|
| 1. appellants argue classification under 72209022 as nickel chromium austenitic steel (Para 2 , 3) |
| 2. revenue defends reclassification to 72209090 and rejects coo (Para 4) |
| 3. rebuttal: no low/high nickel bifurcation in standards (Para 5) |
| 4. court analyzes classification considering processes and standards (Para 6) |
| 5. remand for fresh classification and penalty determination (Para 7) |
SATENDRA VIKRAM SINGH:
The matter in these bunch of appeals is same. To avoid repetition, the facts in the case of M/s Gulshan Exim Private Limited (Appeal No. 10098/2024) are mentioned as under:-
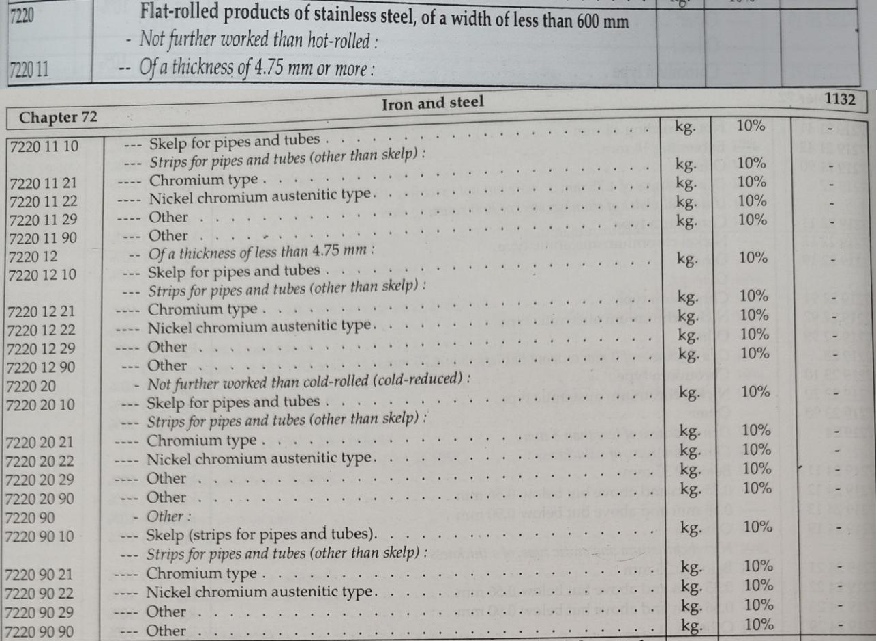
1.1 The appellant M/s Gulshan Exim Private Limited had imported “Flat rolled product of Stainless Steel” falling under Chapter Heading 7219 / 7220 from China. On the basis of intelligence, officers of DRI conducted investigation in the case of the appellant as well as other importers suspecting that they had wrongly availed the benefit of Notification No. 50/2018-Cus dated 30.06.2018 by mis- classifying goods under Chapter Tariff Heading 7220 9022. This Notification exempts duty to the extent of 45% of the applied rate on the goods “Nickel Chromium Austenitic Steel” falling under Chapter Tariff Heading 7220 9022. The appellant had imported Cold Rolled Stainless Steel Coils Grade J-3 which contain more percentage of Chromium and Manganese than Chromium and Nickle. After conducting investigation and recording statements of Shri Dipak Sawlani (G Card Holder), statements of Shri Ashok Kumar, Director of the Appellant Firm, a show cause notice dated 20.05.2022 was issued to the appellant proposing rejection of declared classification and reclassifying the said imported goods under Chapter Tariff Heading 7220 9090, reassessment of the imported goods, confiscation of the said goods valued at Rs. 8,05,40,987/- under Section 111(m) of the Customs Act, 1962, demanding differential duty of Rs. 41,36,129/- and imposition of penalty under Section 112(a), 112(b), 114A, 114AA and 117 of the Customs Act, 1962. Separate penalties were proposed on Shri Ashok Kumar, Director of the appellant firm, M/s R R Logistics, M/s Shivam Clearing Agency Private Limited, Shri Dipak Sawlani, G Card Holder under Section 112(a), 112(b), 114A, 114AA and 117 of the Customs Act, 1962. Separate SCNs were issued to the appellant for imports done from JNPT and Customs, Noida. Similar SCNs were issued to other two appellants namely M/s Gupta Steel and M/s Bhagvan Shri Strips Pvt. Ltd. as detailed in below para.
1.2 The Principal Commissioner, Customs Mundra decided three show cause notices issued to M/s Gulshan Exim together vide impugned order dated 11.12.2023 wherein he confirmed the charges made in the SCNs. He rejected the classification of the goods declared by the appellant reclassified them under tariff heading 7220 9090, confiscated the imported goods under Section 111(m), confirmed the differential duty along with interest and imposed equal penalty upon the appellants under Section 114A of the Customs Act, 1962alongwith penalty under Section 114AA & 117 of the Act . He however did not impose any penalty under Section 112(a) and 112(b) of the Customs Act, 1962.He also imposed penalty on Shri Ashok Kumar, Director of the appellant firm under Section 112(a)(ii) of the Customs Act, 1962. The adjudicating authority did not impose penalty on other co-noticees namely M/s R R Logistics, M/s Shivam Clearing Agency Private Limited and Shri Dipak Sawlani(G Card Holder of M/s R R Logistics and M/s Shivam Clearing Agency Private Limited). He also passed separate orders in the case of M/s Gupta Steel (order dated 22.04.2024) and M/s Bhagvan Shri Strips (order dated 09.05.2024) as detailed under:-
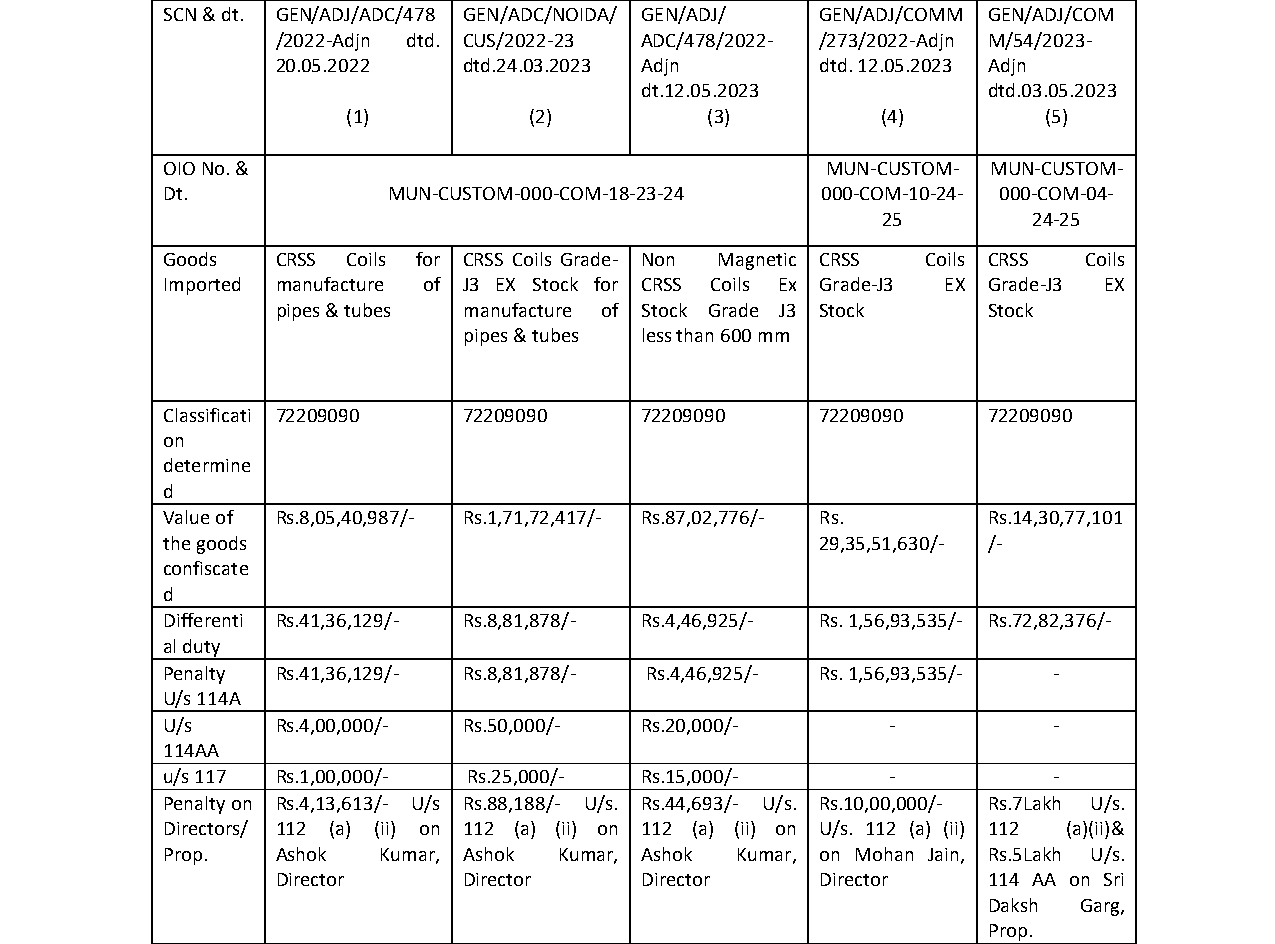
Note : CRSS – Cold Rolled Stainless Steel.
1.3 Aggrieved with the said orders, the appellant(s) filed appeal (s) before this Tribunal.
2. In their appeal, the appellant(s) submitted the following points:
There are no pre-requisites for imported goods to fall under Chapter heading 7220 9022. Further, Ni