


 Back


2026 Supreme(Online)(CESTAT) 135
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
Ashok Jindal, J, K. Anpazhakan, Technical Member
M/s. McLeod Russel India Limited – Appellant
Versus
Principal Commissioner of Service Tax-I – Respondent
Service Tax Appeal No. 76070 of 2017
For the Appellants/Petitioners: Shri Rajeev Agarwal
For the Respondents: Shri S.K. Jha
Service tax demands confirmed without evidence of suppression or fraud cannot sustain extended limitation periods.
Headnote:This case addresses the demands of service tax and penalties confirmed by the Principal Commissioner of Service Tax-I. The appeal by McLeod Russel India Limited challenges the audit findings, claiming that previous audits concluded without further action. The court ruled on issues of limitation, revenue neutrality, and clarified that certain demands of service tax were either set aside or upheld based on the appellant's compliance.
| Table of Content |
|---|
| 1. the initial demand for service tax was based on the audit's findings. (Para 1 , 2) |
| 2. the regulations surrounding the limitations and applicable exemptions for service tax. (Para 3 , 4) |
| 3. court's reasoning for sustaining certain demands and setting aside others based on compliance. (Para 6 , 7 , 8 , 9) |
| 4. final orders on affirmed and dismissed demands, along with penalties. (Para 10 , 11) |
ORDER: [PER SHRI K. ANPAZHAKAN]
The present appeal has been filed against the demands of Service Tax along with interest and penalties as confirmed in the impugned Order-in- Original No. 174/PR.COMMR/ST-I/KOL/2016-17 dated 31.03.2017 passed by the Ld. Principal Commissioner of Service Tax-I, Kolkata.
2. The facts of the case are that on the basis of audit conducted on the books of accounts of M/s. McLeod Russel India Limited (hereinafter referred to as the “appellant”) by the Service Tax Department in January 2014, an audit memo was issued on 05.02.2014 wherein it was stated that there were differences in the figures appearing in the Books of Accounts and the service tax returns filed by the appellant for the period 2008-09 to 2012-13.
2.2. On the basis the said audit objection, a Show Cause Notice bearing no.37/2014 dated 22.04.2014 was issued demanding Service Tax of Rs.2,94,14,374/- (inclusive of cesses) along with interest and penalties.
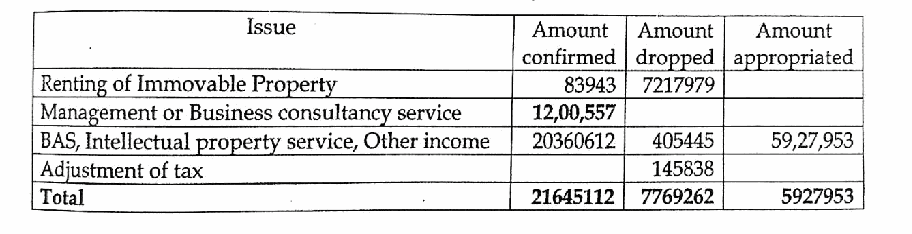
2.3. The said notice was adjudicated vide the impugned Order-in-Original dated 31.03.2017, confirming the demand of Service Tax to the extent of Rs. 2,16,45,112/- (inclusive of cesses) along with interest, and imposing equal amount of tax as penalty; the ld. adjudicating authority also imposed a penalty of Rs.10,000/- under Section 77 of the Finance Act, 1994 . For ease of reference, the details of the demands of Service Tax confirmed and dropped by way of the impugned order in respect of the various issues are provided below: -
2.4. Aggrieved by the confirmation of the demands of Service Tax along with interest and penalties against them, the appellant has filed this appeal.
3. The appellant has submitted that on the basis of the audit memo raised, initially the Department has issued a Notice dated 14.03.2014, wherein it was stated that the appellant had deposited service tax of Rs.6,75,633/- (for the period January 2013 to March 2013) and Rs.59,27,973/- (for the period July 2012 to March 2013) in the course of audit; however, the appellant was held liable to pay penalty under Section 73 (4A) of the Act. The appellant submits that since the Service Tax Department was satisfied with the explanation furnished by them that no Service Tax was payable, the audit was duly concluded and there was no reason to initiate further proceedings except for the penalty, as proposed in the Notice dated 14.03.2014. However, they submit that despite conclusion of audit as aforesaid, the impugned Show Cause Notice dated 22.04.2014 was issued proposing to demand Service Tax on the very same issue for the same period covered under the aforesaid audit. The appellant has contended that since the Authorities were duly satisfied with regard to the explanation furnished by them in the course of audit, the issuance of impugned Show Cause Notice clearly shows that there is a change in opinion of the Authorities inasmuch as the Authorities proceeded to re-open the proceedings which stood concluded in the audit. Hence, they contend that the impugned Show Cause Notice is liable to be quashed on the ground alone.
4. The appellant stated that the demands confirmed in the impugned order can be categorised under four categories. The submissions of the appellant under each of the categories of demand are summarized below: -
4.1. Demand on Renting of Immovable Property Services
(i) The appellant submits that the impugned Show Cause Notice has demanded service tax of Rs.73,01,922/- for the period 2008-09 to 2012- 13, under the category of Renting of Immovable property Services; on the basis of reconciliation submitted by appellant i







