
 Back


CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
ASHOK JINDAL, J, K. ANPAZHAKAN, Technical Member
M/s. Jindal Steel & Power Limited – Appellant
Versus
Commissioner of Central Tax, G.S.T. and C.X. – Respondent
Excise Appeal No. 76300 of 2018
ORDER: [PER SHRI ASHOK JINDAL]
The appellant is in appeal against the impugned order wherein central excise duty amounting to Rs.333,22,45,002/-, along with interest, has been demanded and penalty thereon under Section 11AC of the Central Excise Act, 1944 read with Rule 25 of the Central Excise Rules, 2002 has been imposed.
2. The brief facts of the case are that M/s. Jindal Steel & Power Ltd. (‘JSPL’), Barbil Unit, the appellant before us, is engaged in the manufacture of iron ore pellets falling under Chapter 26 of the Central Excise Tariff Act, 1985, (‘CETA’). The pellets manufactured by the appellant are primarily cleared to its own manufacturing units located at Angul, in the State of Odisha and Raigarh, in the State of Chhattisgarh, for captive consumption. The appellant also sells iron ore pellets to independent third-party buyers.
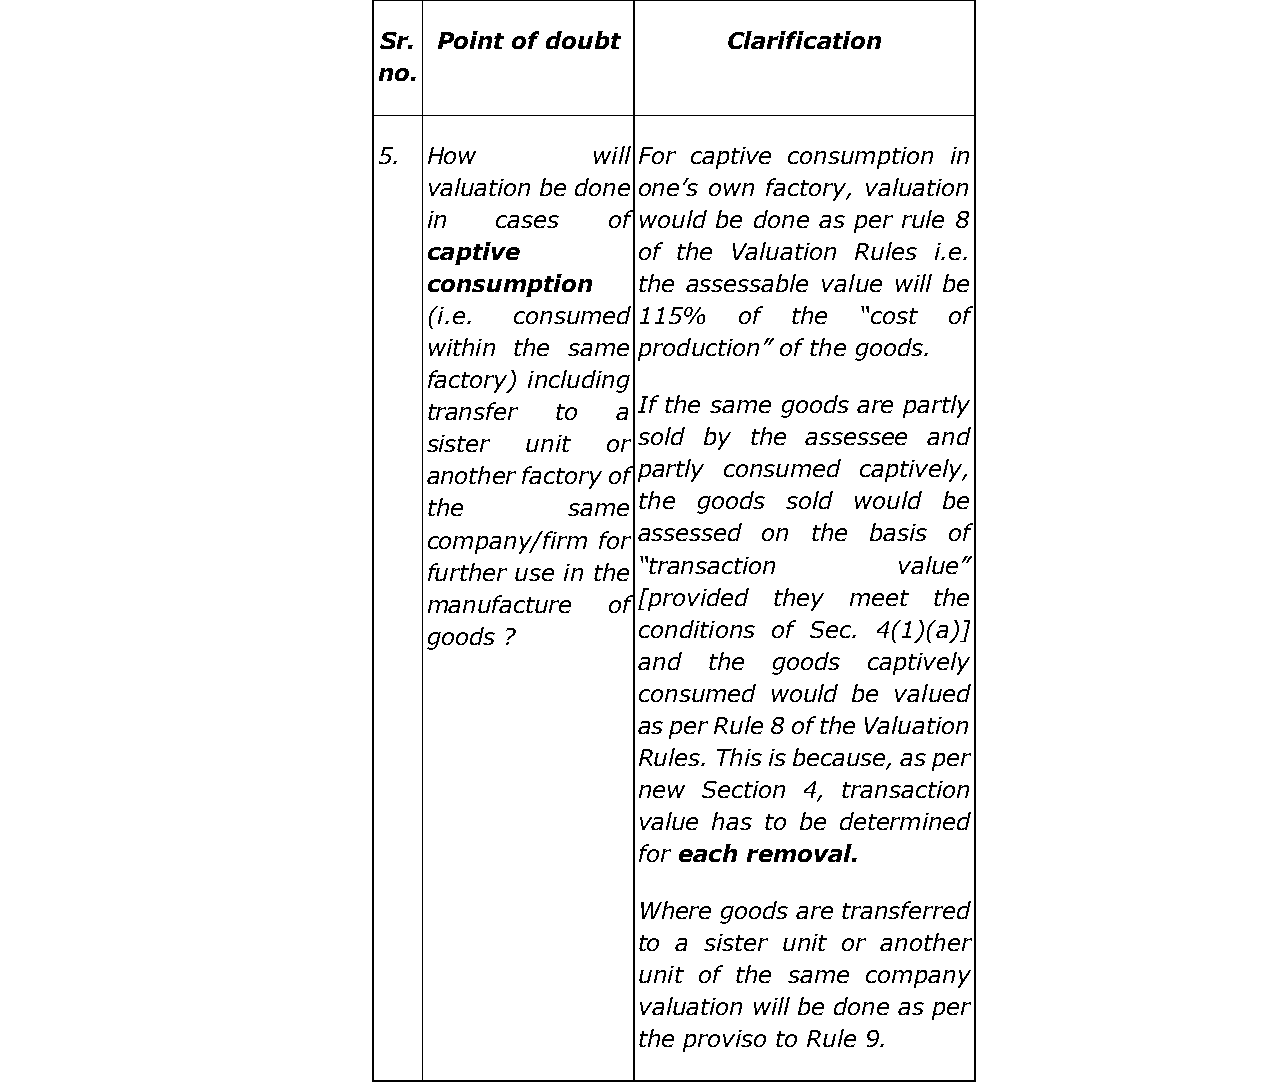
2.1. With regard to the clearances made by the appellant to its own units for captive consumption, during the period in dispute, the excise duty was paid on the value determined in terms of Rule 8 of the Central Excise Valuation (Determination of Price of Excisable Goods) Rules, 2000 (hereinafter referred to as “Valuation Rules”) i.e., on the basis of 110% of the cost of production computed in terms of Cost Accounting Standard-4 (“CAS-4”). It is undisputed that the excise duty paid on the goods cleared for captive consumption to its own units at Angul and Raigarh, was available as CENVAT credit to the recipient units and had in fact, been so availed and utilized for the purpose of discharging excise duty on the downstream goods manufactured by using such pellets.
2.2. The records of the appellant’s units were audited from time to time and the audit team, in its reports dated 16.05.2012 and 14.08.2013, specifically observed that there was some infirmity in the determination of value arrived under Rule 8 by applying CAS-4, in respect of excisable goods cleared to its own units and had directed the appellant for payment of excise duty with interest, for the period from 2009-10, 2010-11 and 2011-12.
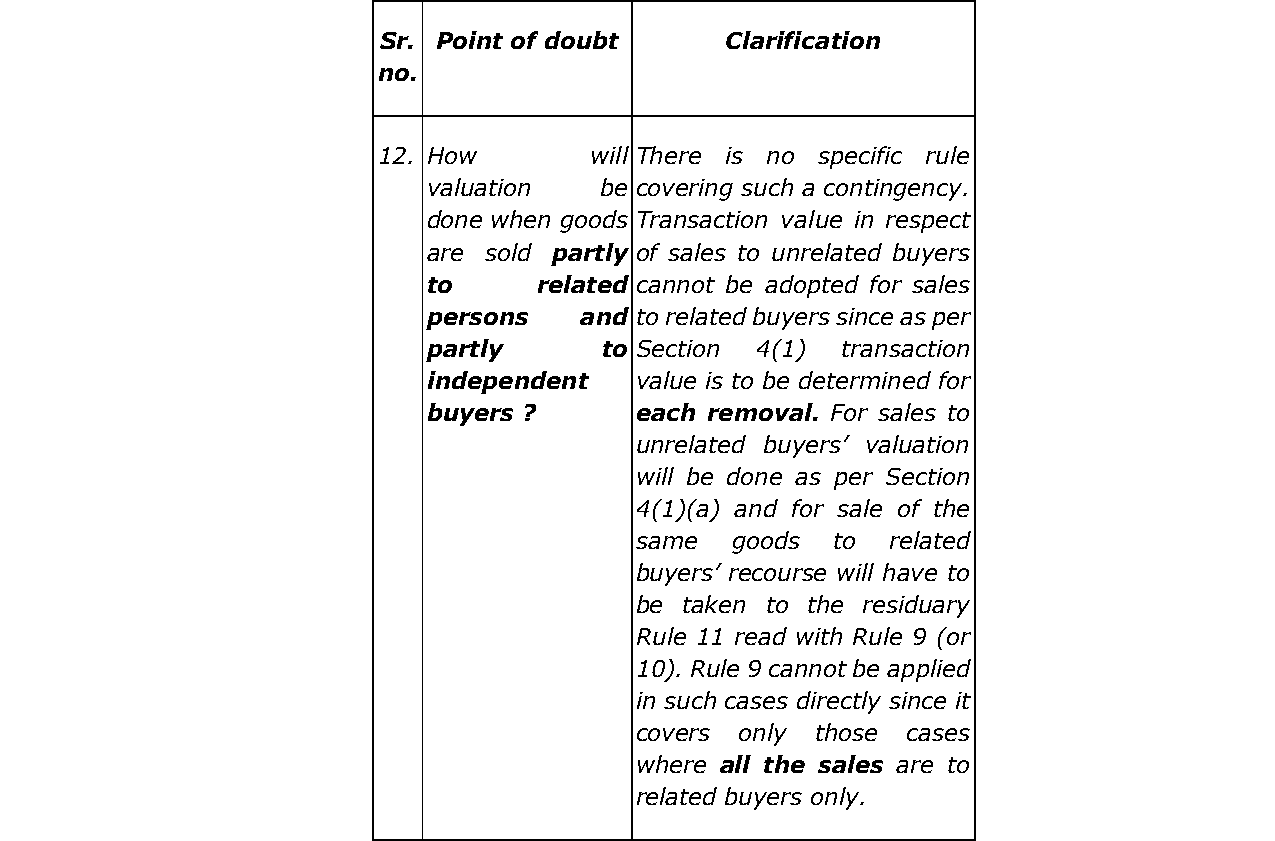
3. A Show Cause Notice was issued to the appellant on 11.12.2014, alleging that the appellant’s clearances to its own units at Angul and Raigarh, tantamount to “sales” to a related party. The Show Cause Notice placed reliance on the decision of the Tribunal in the case of Aquamall Water Solutions Ltd. [2005 (182) E.L.T. 196 (Tri. - Bang.)] maintained by Apex Court in the case of 2006 (193) E.L.T. A197 (S.C.), as well as the C.B.E.C. Circular No. 643/34/2002-CX dated 01.07.2002, particularly para 12 thereof, to allege that where excisable goods are sold by one unit to another unit of the same company or to a sister unit, valuation in terms of Rule 9/10 of the Valuation Rules, read with Rule 8 of the Valuation Rules is inapplicable since all the excisable goods are not sold to the related buyer. Accordingly, demand of central excise duty amounting to Rs.333,22,45,002/- (inclusive of cesses), along with interest and penalty, was proposed, considering the price charged to independent buyers at the nearest point in time when the goods were cleared to the appellant’s own units at Angul and Raigarh, by invocation of the extended period of limitation.
4. The matter was adjudicated by way of the Order-in-Original No. 46/CCE/CEX/RKL/2017-18 dated 29.11.2017, wherein the ld. adjudicating authority has confirmed the demand of central excise duty amounting to Rs.333,22,45,002/-, as proposed, along with interest thereon; penalty under Section 11AC of the Central Excise, Act, 1944 read with Rule 25 of the Central Excise Rules, 2002 was also imposed upon the appellant.
4.1. Against the said order, the appellant is before us.
5. The various submissions made by the Ld. Counsel appearing on behalf of the appellant herein can inter alia be summarized as under: -
(i) The issue as to whether the clearances made by the appellant to its own units for captive consumption is to be valued in terms of Rule 8 of the Valuation Rules,


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


