Back


2026 Supreme(Online)(CESTAT) 173
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
Ashok Jindal, J, K. Anpazhakan, Technical Member
M/s. Outotec India Private Limited – Appellant
Versus
Principal Commissioner of Service Tax-I – Respondent
Service Tax Appeal No. 76193 of 2016
For the Appellants/Petitioners: Shri Pulak Saha
For the Respondents: Smt. K. Kalpana
Service Tax demands must specify taxable service categorically; mere discrepancies in financial records are insufficient for levying tax.
Headnote:Statute Analysis: The judgment examines the applicability of Service Tax under Section 66 and 73(2) of the Finance Act, 1994. Facts of the Case: This appeal contests a demand of Service Tax of Rs.8,18,77,300/- due to ambiguous classification in the Show Cause Notice.
Findings of Court:
The court found that the demand was unsustainable due to lack of specificity in categorizing taxable services.
Issues: The main question was whether the demand could stand without proper classification of services.
Ratio Decidendi: The court ruled that demands cannot be confirmed merely based on discrepancies between accounting statements.
Result: The demand of Service Tax of Rs.8,18,77,300/- confirmed in the impugned order is set aside, penalties are rescinded.
| Table of Content |
|---|
| 1. service tax demand arises from order-in-original. (Para 1 , 2) |
| 2. arguments emphasize procedural flaws in tax imposition. (Para 3 , 4) |
| 3. court discusses evidentiary requirements for imposing service tax. (Para 5 , 6 , 7 , 8) |
| 4. court rules on non-sustainability of the tax due to lack of evidence. (Para 10 , 11 , 12) |
| 5. outcome favors the appellant's appeal, leading to tax nullification. (Para 13 , 14) |
ORDER: [PER SHRI K. ANPAZHAKAN]
The present appeal has been filed against the Order-in-Original No. 61/COMMR/ST-I/KOL/2015-16 dated 31.03.2016 wherein the total demand of Service Tax amounting to Rs.8,18,77,300/-, along with recovery of CENVAT Credit of Rs.1,67,768/-, has been ordered, along with interest. In the said order, the ld. adjudicating authority has also imposed penalties under Section 77 and 78 of the Finance Act, 1994 read with Rule 15 of the CENVAT Credit Rules, 2004.
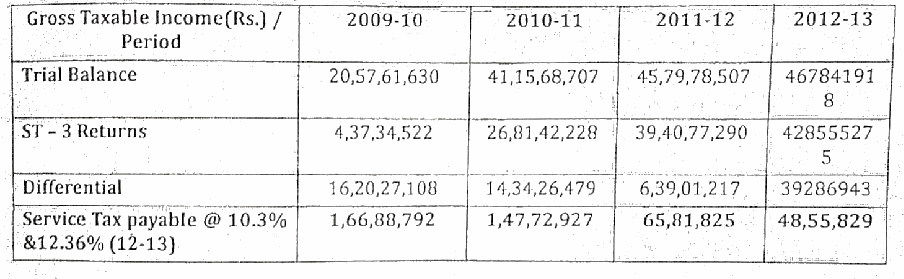
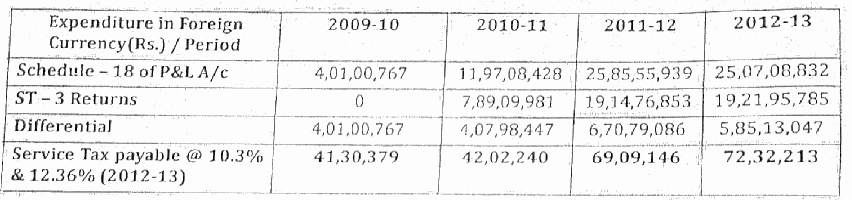
2. The appellant has pointed out that out of the total demand of Rs.8,18,77,300/-, Rs.5,94,03,322/- [Rs.4,28,99,373/- + Rs.1,65,03,949/-] pertains to the demand of Service Tax raised under Section 73 (2) of the Finance Act, 1994 and Rs.2,24,73,978/- pertains to the demand of Service Tax raised under reverse charge; it is stated that they have already reversed the CENVAT Credit of Rs.1,67,768/- from their CENVAT Credit Account, prior to utilization of the same and before passing of the impugned order and hence, denial of the same is not being contested in this appeal.
3. The submissions made by the appellant in respect of the various demands confirmed vide the impugned order, inter alia are summarized as under:- 3.1. Demand of Service Tax of Rs.5,94,03,322/- [Rs.4,28,99,373/- + Rs.1,65,03,949/-]:
(i) The appellant submits that Service Tax amounting to Rs.4,28,99,373/- has been confirmed on the basis of comparison of Profit & Loss Accounts, Trial Balance and Service Tax Returns. It is submitted that the Show Cause Notice has not classified as to under which taxable category Service Tax is liable to be paid by them for the period prior to 01st July, 2012 [Positive List Regime]; even for the period after 01st July, 2012 [Negative List Regime), the demand has been confirmed without analysing the nature of the activities which was necessary to determine whether such activities were liable to Service Tax or not.
(ii) The demand of Service Tax of Rs.1,65,03,949/- has been confirmed on the basis of the closing balance of Advance received. The Show Cause Notice has simply considered the closing balance of Advance received as mentioned in the Trial Balance Sheet for the respective Financial Years, without analysing the nature of advances received or specifying the particular category of taxable service under which the disputed tax was required to be paid.
(iii) In support of their contention that a demand cannot be raised without specifying the nature of service under any particular category of taxable service, the appellant relies on the following case-laws: -
• Commr. of Service Tax, Kolkata Versus M/s. Haldia Logistics Pvt. Ltd and vice- versa [2025 (5) TMI 2187 – CESTAT Kolkata]
• Star Freight Pvt. Ltd. versus C.S.T. - Service Tax – Ahmedabad , [2023 (9) TMI 71]
(iv) In support of their contention that no Service Tax can be demanded merely on the basis of difference between Balance Sheet and ST-3 Returns, reliance has been placed on the following case-laws: -
• M/s. R.K. Singh & Co. vs Commissioner Customs & Central Excise Bilaspur, Raipur, [2023 (5) TMI 721 – CESTAT New Delhi];
• CST, Service Tax, Delhi vs Convergys India Service Pvt. Ltd. [2018 (1) TMI 1174 – CESTAT Chandigarh];
• M/s. Sarvatra Integrated Management Service Pvt. Ltd. vs Commissioner of CGST & Central Excise, Gurgaon, [2024 (9) TMI 1028 – CESTAT Chandigarh].
• M/s. Nirman Construction Versus Commissioner of Central Excise, Service Tax and Customs, Durgapur Commissionerate, Burdwan (West Bengal) [reported in 2025 (8) TMI 6 – CESTAT Kolkata]
(v) In view of the above, the appellant pray