Back


2026 Supreme(Online)(CESTAT) 180
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
P. Dinesha, J, Vasa Seshagiri Rao, Technical Member
M/s.Hyundai Motor India Ltd. – Appellant
Versus
The Commissioner of Customs Chennai-II (Imports) – Respondent
Customs Miscellaneous Application No.40805 of 2025 & Customs Appeal No. 40552 of 2025
For the Appellants/Petitioners: Dr. C. Manickam
For the Respondents: Shri Anoop Singh
Imported parts classified as incomplete; preferential duty denial without timely notification of grounds invalid. Penalties for misclassification unsustainable without evidence.
Headnote:(A) Customs Act, 1962 - Sections 28(4), 111(m), 112(a), 114A - Classification of imported goods - The Adjudicating Authority re-classified 'Door Latch and Actuator Assembly' imported as CTI 87089900 to CTI 83012000, alleging incorrect classification, which denied preferential duty benefits under Notification No.46/2011-Cus. - The Court found that the imported items were parts of locks, not complete locks, thus deserving their classification under CTI 83016000. (Paras 2, 6, 11, 19)
(B) Customs Tariff - Determination of Origin Rules, 2009 - Failure to notify grounds within 60 days of submission of the Certificate of Origin renders denial of preferential duty invalid - Custom Department did not follow due process, making the rejection of the certificate unlawful. (Paras 8.8, 10, 12, 16)
(C) Penalty and confiscation - Imposition of penalty under Section 114A and confiscation as result of classification error held unsustainable due to lack of evidence on misrepresentation or mala fide action. (Paras 17, 19)
Facts of the case:
The Appellant imported parts necessary for automobiles and was previously allowed to classify them correctly; subsequent investigation led to an erroneous view, resulting in denial of established benefits and allegations of misclassification.
Findings of Court:
The imported goods classified were determined to be parts and not capable of performing essential lock functions independently; hence, the established preferential rate under the proper tariff was applicable.
Issues: Core issues were whether imported parts are classifiable as locks capable of essential functions, the validity of the preferential duty exemption, and whether penalties for alleged discrepancies were warranted.
Ratio Decidendi: The court concluded that classification disputes must be correctly resolved based on the functional evidence provided; differences in classification must not result in penalties without proven misconduct.
Result: Appeals allowed, impugned orders set aside.
| Table of Content |
|---|
| 1. background of the appeal and classification dispute. (Para 1 , 2) |
| 2. arguments regarding the classification of imported goods. (Para 3 , 5 , 6) |
| 3. court's analysis of classification issues. (Para 8 , 9 , 14) |
| 4. legal principles on classification and preferential tariff treatment. (Para 10 , 16) |
| 5. final decision and order of the court. (Para 19) |
Per: Shri P. Dinesha
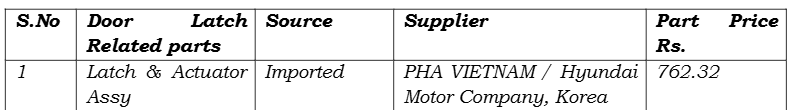
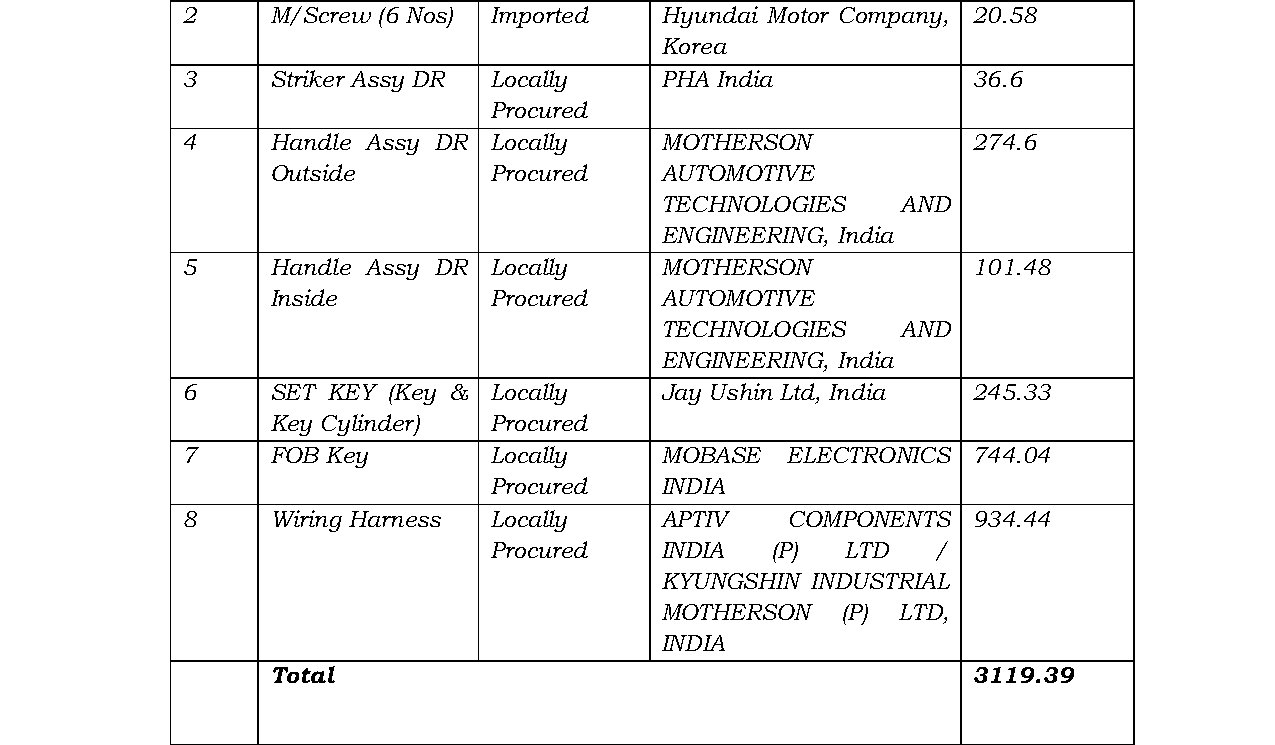
This Appeal is filed by M/s. Hyundai Motor India Limited (Appellant herein) against the Order-in-Original No. 111631/2025 dated 14.02.2025 passed by the Commissioner of Customs-II (Imports), Sea Port, Custom House, Chennai. The Appellant is an automobile car manufacturer and for manufacture of automobile vehicles in India they regularly import various parts and components from overseas countries and also procures components and parts from domestic manufacturers. In the impugned Order- in-Original, the Adjudicating Authority has re-determined the classification of the imported items such as “Door Latch and Actuator Assembly” and also denied the benefit of preferential rate of duty availed for the earlier imports as per Sl. No. 1478 of Notification No.46/2011-Cus. Dated 01.06.2011.
2. Brief and relevant facts for the purpose of this Appeal are that the Department initiated investigation on the ground that the Importer-Appellant while importing “Door Latch and Actuator Assembly” had classified the same wrongly under Customs Tariff Item (CTI) 87089900, which resulted in the Department entertaining an opinion that the imported item is to be classified under CTI 83012000 under the category of ‘Automobile Locks’; and as an outcome of the Investigation, a Show Cause Notice No. 60/2024 dated 20.06.2024 came to be issued under Section 28 (4) and 124 of the Customs Act, 1962 thereby levelling the allegation that the assessment and the declared classification of the imported goods under CTI 87089900 imported vide 149 Bills of Entry are liable to be rejected for wrong-classification and is to be re-classified under CTI 83012000 of the First Schedule to the Customs Tariff Act, 1975 and the subject Bills of Entry had to be re-assessed resulting in denial of the benefit of concessional rate of duty/ duty exemption availed under the Notification No. 46/2011-Cus. It was also proposed to confiscate the goods under Section 111 (m) of and penalty proposed to be imposed under Section 112 (a) or under Section 114A of .
3. In response to the allegations levelled in the Show Cause Notice, the Importer/Appellant appears to have submitted a detailed reply and also appeared before the Original Authority for personal hearing wherein they appear to have inter-alia submitted that the imported items are only ‘parts of locks’ and as such, cannot perform the essential functions of a lock; that Rule 2(a) of General Interpretative Rules (GIR) cannot be invoked since the imported parts cannot perform essential functions of a lock; that the Importer is an Original Equipment Manufacturer (OEM) and the imported goods undergo manufacturing process on post- importation at the factory in the course of which the imported ‘Latch and Actuator Assembly’ are integrated and processed along with other parts sourced from Domestic markets; that the benefit of Country of Origin cannot be denied at this stage when the earlier clearances were allowed since 60 days’ time limit prescribed under the FTA Rules are already expired; that extended period cannot be invoked as it is a classification dispute; and lastly, when the imported goods were allowed for clearance without execution of any bond, consequently the question of confiscation of goods and imposition of redemption fine and penalty would not arise.
4. The Adjudicating Authority having considered the explanation filed by the Assessee, passed the Impugned Order by holding that the imported “Latch and Actuator Assembly” had to be classified under CTI 83012000 as “Locks of a kind used for automobiles” as proposed in the SCN and thus denied the benefit of