Back


2026 Supreme(Online)(CESTAT) 216
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
S. S. GARG, J, P. ANJANI KUMAR, Technical Member
M/s Goyal Impex and Industries Ltd. – Appellant
Versus
Commissioner of Customs, Ludhiana – Respondent
Customs Appeal No. 61150 of 2025
For the Appellants/Petitioners: Shri Saurabh Kapoor, Ms. Muskaan Gupta, Ms. Tanya Kumar, Ms. Muskan Chahuhan, Shri Gurwinder Singh
For the Respondents: Shri Sourabh Goel, Ms. Geetika Sharma
Conditions for provisional release of imported goods should be fair and not hinder legitimate business operations; excessive demands must align with the actual risk involved and not compromise ongoing trade.
Headnote:(A) Customs Act, 1962 - Section 110A - Provisional release of imported goods - Appellants challenged the order for provisional release required bond of Rs. 8,06,03,509 and a bank guarantee of Rs. 9,12,48,585 under disputed circumstances. The goods were seized on suspicion of mis-declaration and undervaluation. The appellants contended procedural irregularities and inconsistencies in testing and valuation. Court underscores the necessity of balanced conditions for provisional release relative to legitimate business operations ensuring not to impose unreasonable financial burdens upon importers. (Paras 2, 3, 8, 10, 18, 26)
Findings of Court:
Provisional release allowed if appellants furnish a bond covering full value and a bank guarantee amounting to 30% of the alleged differential duty; harsh conditions should not hinder legitimate business continuance.
Result: Appeal partly allowed. (Para 27)
P. ANJANI KUMAR:
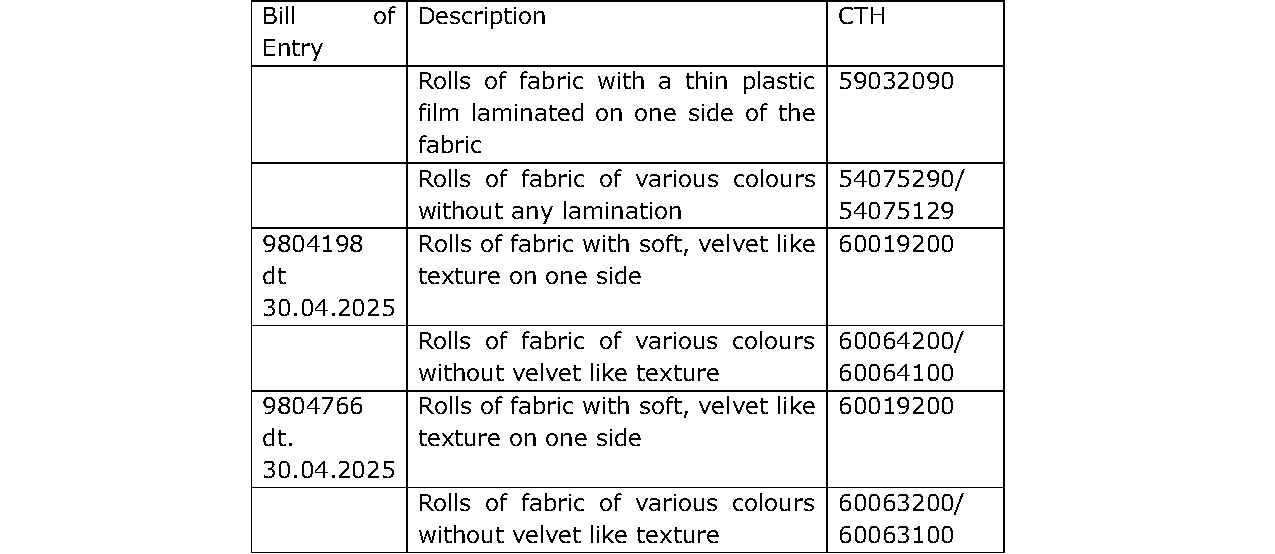
M/s Goyal Impex Industries Ltd, the appellants, challenge the order dated 15.09.2025 passed by the Commissioner of Customs, Ludhiana, who ordered for the provisional release of goods imported by the appellants, vide bills of entry no. 9769822 /29.04.2025, 9804766, 9804198, 9805550 and 9806044/30.04.2025 and 9840277/02.05.2025, subject to furnishing of the bond of Rs. 8,06,03,509 and a bank guarantee of Rs. 9,12,48,585.
2. Brief facts of the case are that the appellants are in the business of import of various kind of fabrics and hold AEO status; the appellants had entered into 4 contracts, dated 23.03.2025, 28.03.2025, 29.03.2025 and 01.04.2025, with the Chinese supplier M/s Shaoxing Keqiao Mulinsheng Trading Co. Ltd., China, for import of Mix lot of polyester woven fabric with heat pressed film made of thermoplastic polyurethane rolls of assorted colours other than coated polyurethane and others. Accordingly, the goods were supplied and on the basis of invoice, packing list, bill of loading etc. 7 bills of entry were filed by the appellant importer; the goods were cleared by the EDI system. SIIB of Customs initiated inquiry into the import and have drawn 17 samples under various Panchnama dated 05.05.2025, 06.05.2025, 07.05.2025, 08.05.2025 and 09.05.2025; the samples were sent to CRCL, New Delhi. The goods were seized on 08.05.2025 and 09.05.2025 on the basis of the reports received from CRCL. The appellants, vide letter dated 16.07.2025, requested the Commissioner of Customs to release the imported goods, though provisionally, on execution of a bond without any bank guarantee looking into the status of the import of as AEO-T1 and MSME and the fact that the appellant has been importing since 1993; vide letter dated 17/19. 5.2025, the appellant submitted that only 02-04 samples were drawn from a heterogeneous stock and the same were not representatives samples; further vide letters dated 21.05.2025 and 22.05.2025 the appellants informed the Commissioner that the samples were received without test memos and therefore, the samples already drawn may be kept at abeyance; they also supplied the clarification given the supplier vide letters dated 06.05.2025 and 09.05.2025; then vide letter dated 22.05.2025 the appellants have informed the commissioner that the measurement of the samples was incorrect and therefore, the conversion to square meters from meters was incorrect. The appellants objected to the test memo and posed 15 questions; however, CRCL vide letter dated 19/20.2025 replied to only 11 questions, thus the test reports were alleged to be inconclusive.
2.1 The appellant had been requesting the department raising objections on the sampling and testing methodology. Accordingly, 258 representative samples were drawn from the 12 containers during 27.06.2025 to 18.07.2025; the appellants pursued the provisional release of the goods imported vide impugned bills of entry between 01.07.2025-19.07.2025. Meanwhile, the appellants have moved the Hon’ble Punjab and Haryana High Court, by filing a civil writ petition No. 23019 of 2025 requesting the provisional release of the goods, who directed the authorities to decide on the representation filed by the appellants regarding provisional release; the appellants were provided data pertaining to contemporaneous imports and chartered engineer’s report vide email dated 08.09.2025; a personal hearing was held and the impugned order dated 15.09.2025.
3. Shri Saurabh Kapoor, Learned Counsel for the appellants submits that the impugned order is contrary to the facts of the case and has been passed in violation of principles of natural justice; the value of the imported goods has been calculated without appreciation of the facts due to incoherent and inconsistent stand on the basis of the investigation which is full of procedural irregularities and incomplete testing; the impugned order ignores the initial finding that the samples require reinvestigation and proceeds to issue of v