Back


2026 Supreme(Online)(CESTAT) 279
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
Ashok Jindal, J, K. Anpazhakan, Technical Member
M/s. Nanu Shome & Co. – Appellant
Versus
Commissioner of C.G.S.T. and Central Excise – Respondent
Service Tax Appeal No. 76615 of 2025
For the Appellant: Shri Aditya Dutta, Shri G. Sharma
For the Respondent: Shri S. Dutta
Service Tax demands must be substantiated by independent verification, not merely based on CBDT data, especially when claiming exemptions.
Headnote:(A) Finance Act, 1994 - Section 78 - Service Tax - Demand of Service Tax confirmed amounting to Rs.2,86,48,709/- with penalties without verification of service provision by Revenue - It is held that the demand raised solely on data from Income Tax Department without independent evidence is not legally sustainable. (Para 8.3)
(B) Exemptions - Works contract services rendered to governmental authorities - Notification No. 25/2012-S.T. dated 20.06.2012 and Notification No. 09/2016-S.T. dated 01.03.2016 - The appellant's services fall within exempted categories, and the Revenue failed to substantiate allegations of non-payment with corroborative evidence. (Paras 9.1 and 11.1)
(C) Procedural Fairness - Pre-Show Cause Notice consultation mandatory as per Board's Circular dated 21.12.2015 - No consultation conducted despite demand exceeding Rs.50 Lakhs, rendering the notice unsustainable. (Para 10.1)
Facts of the case:
The appellant, a firm engaged in providing works contract services, believed their services exempt from tax based on cited notifications. Following a Show Cause Notice based on CBDT data, which lacked validation, they appealed against the confirmed demand and penalties.
Findings of Court:
The appeal is allowed, and the impugned order is set aside due to lack of now-conducted independent verification and procedural lapses.
Issues: The main issues addressed include the nature of services rendered, the applicability of exemptions, and procedural non-compliance by the Revenue.
Ratio Decidendi: The court reasoned that demands must be substantiated with proper inquiry and that the absence of pre-notice consultation invalidates the claim.
Result: Impugned order is set aside and the appeal is allowed.
| Table of Content |
|---|
| 1. nature of appellant's services (Para 2) |
| 2. arguments for service tax exemption based on notifications (Para 4 , 5) |
| 3. need for independent verification for tax demands (Para 8) |
| 4. procedural requirements affecting service tax notices (Para 9) |
| 5. final decision and implications for tax demand (Para 11) |
ORDER:
[PER SHRI K. ANPAZHAKAN]
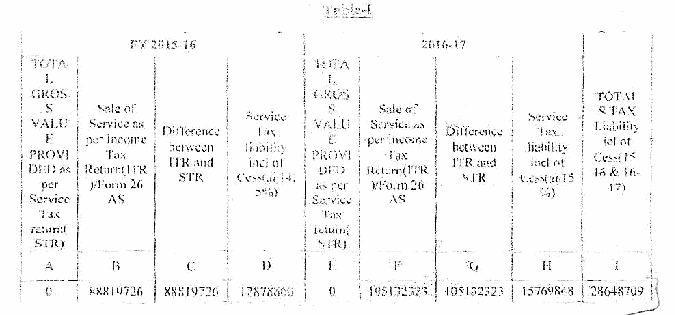
The present appeal has been filed challenging the Order-in-Original No. 60/COMM/ST/SLG/23-24 dated 28.03.2024 passed by the Commissioner, Siliguri Central Excise and C.G.S.T. Commissionerate wherein the demand of Service Tax amounting to Rs.2,86,48,709/- (inclusive of cesses) for the period from April 2015 to March 2017 has been confirmed, along with interest. A penalty equal to the above Service Tax demand confirmed has also been imposed by the ld. adjudicating authority under Section 78 of the Finance Act, 1994 ; penalty of Rs.10,000/- under Section 77 (1)(c) of the Act and late fee of Rs.80,000/- on account of non-filing of ST-3 Returns under Section 70 of the Act read with Rule 7(C) of the Service Tax Rules, 1994 have also been imposed.
2. The facts of the case are that M/s. Nanu Shome & Co. (hereinafter referred to as the “appellant”), is a firm engaged in the business of providing works contract services relating to construction of civil structures, construction of road, river embankment, canal for irrigation related works, etc., to various local authorities and government bodies. The appellant- firm had Mr. Sandeep Shome and Mrs. Nanu Shome as partners. After the death of Mr. Sandeep Shome on 23.04.2023, his wife, Mrs. Nanu Shome, became the sole owner of the firm. As per the appellant, the said firm stopped functioning after the death of Mr. Sandeep Shome.
2.1. As per the appellant, they were under the bona fide belief that the services provided by them were exempted from levy of Service Tax by virtue of Notification No. 25/2012-S.T. dated 20.06.2012 as amended by Notification No. 09/2016-S.T. dated 01.03.2016. Therefore, the appellant did not take registration with the Department and did not file any Service Tax Returns, since they were of the view that no registration was required as the services provided by them were exempted from payment of Service Tax.
3. On the basis of the data received from Central Board of Direct Taxes (C.B.D.T.), i.e., as per Form 26AS received from the Income Tax Department, the Department sought some information from the appellant by sending an e-mail on 16.04.2021. Subsequently, another letter dated 21.04.2021 was also issued, seeking documents.
4. Thereafter, on 28.04.2021, a Show Cause Notice was issued to the appellant wherein Service Tax amounting to Rs.2,86,48,709/- (inclusive of cesses), has been demanded along with interest and penalties, for the Financial Years 2015-16 to 2016-17, on the basis of the information available in Form 26AS data collected from the C.B.D.T.
4.1. The said Notice came to be adjudicated vide the impugned order dated 28.03.2024 whereby the demand of Service Tax, as proposed in the said Notice, has been confirmed, along with interest and penalties thereon.
4.2. Aggrieved by the confirmation of the above demand of Service Tax, along with interest, and imposition of penalties, the appellant has filed the instant appeal.
5. The Ld. Counsel appearing on behalf of the appellant submits that all the services rendered by the appellant were in the nature of ‘works contract service’ relating to construction of civil structures and other original works in relation to road and irrigation related work, to government bodies / local authorities / governmental authorities. It is his submission that the said services were exempted vide Notification No. 25/2012-S.T. dated 20.06.2012 as amended by Notification No. 09/2016-S.T. dated 01.03.2016; he points out that the same is evident from the 26AS statement relied upon by the Department wherein it has been categorically mentioned that the amounts were received from “Executive Engineer PWD Jal