Back


2026 Supreme(Online)(CESTAT) 1502
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
SOMESH ARORA, J, SATENDRA VIKRAM SINGH, Technical Member
ASR Multimetals Pvt Ltd – Appellant
Versus
Commissioner of Customs-Kandla – Respondent
Customs Appeal No. 10420 of 2015-DB|Customs Appeal No.10396 of 2015-DB|Customs Appeal No.10407 of 2015-DB|Customs Appeal No.10421 of 2015-DB|Customs Appeal No.10422 of 2015-DB|Customs Appeal No.10423 of 2015-DB|Customs Appeal No.10614 of 2015-DB
For the Appellants/Petitioners:Shri P D Rachchh, Advocate, Shri Vikas Mehta, Consultant
For the Respondents: Shri Aakash Singh, Superintendent (AR)
Transaction value cannot be rejected without evidence of suppression; high sea sales value per actual contract with documents.
Headnote:The Customs Act, 1962 particularly Sections 14, 28(4), 111(d), 111(m), 112(a), 112(b), 114A, and Customs Valuation Rules, 2007 (Rules 3,4,5,9,12) govern valuation and penalties for undervaluation. DRI investigated evasion on HMS scrap imports via direct imports (36 B/Es) and high sea sales (48 B/Es), issuing SCN proposing duty Rs.40,66,835/-, interest, penalties. Lower authorities confirmed demands; appeals challenged lack of evidence and natural justice violations. Court found no evidence rejecting transaction value for direct imports; remanded high sea sales for document verification per CBIC Circular No.32/2004-Cus.
Issues: Whether declared values rejected without evidence under S.14 and Valuation Rules; sustainability of penalties without proof of collusion or abetment; compliance with natural justice. Ratio: Transaction value presumed valid absent reasonable doubt and evidence (Century Metal Recycling Pvt. Ltd.); high sea sale value per actual contract price with full document chain; sequential valuation mandatory post-rejection. Duty/penalties set aside for 36 direct import B/Es; remaining high sea sales demands and penalties remanded to Adjudicating Authority for fresh decision with documents within timelines.
| Table of Content |
|---|
| 1. dri investigation into scrap undervaluation via searches, statements, scn issuance. (Para 1) |
| 2. appellants challenge lack of evidence, natural justice violations, improper valuation. (Para 2) |
| 3. oral arguments on undervaluation proof, admissions, penalties justification. (Para 3 , 4) |
| 4. no evidence rejects direct import values; set aside duty for 36 b/es. (Para 5) |
| 5. appeals disposed with partial set aside and remand directions. (Para 6) |
SATENDRA VIKRAM SINGH
1. On the basis of intelligence, DRI officers searched the factory premises of M/s. ASR Multimetals Pvt. Ltd. (Appellant) as well as the residential premises of their Director Shri Atul Agarwal to unearth evasion of customs duty by the appellant on import of Heavy Melting Steel (HMS) scrap as well as cast iron scrap, re- melting scrap etc. During investigation, they recorded the statements of Shri Prem Prakash Gupta, Vice-President (Commercial) and Shri Praksh Shivratan Lakhotia, Manager (Purchase) of M/s. Electrotherm (India) Ltd., statement of High Sea Sellers namely, Shri Hanif Akbani (Proprietor of M/s. Akbani Traders, Rajkot), Statement of Shri Pratik Sunil Garg (Director of M/s. Raj kripal Lumbers Ltd, Gandhidham,) statement of Shri Mahendra Bhavanji Chande (Authorised Signatory of M/s. Ishita Overseas), statement of Shri Jitendra Jain (Partner of Shri Adinath Tradelinks, Gandhidham,) statement of Shri Manoj Satnam ( Prop. of M/s. Trimurti Impex, Gandhidham) and the statement of Shri Atul Agarwal, Director of appellant company. On the basis of incriminating documents resumed from both the premises and the recorded statements, the department made a case of undervaluation of HMS Scrap imported directly as well as and re- meltable scrap purchased from the High Sea Sellers.
1.1 After Completing investigation, Revenue issued show cause notice dated 23.08.2012 to M/s. ASR Multimetals Pvt. Ltd. proposing confiscation of seized goods valued Rs.18,16,64,440/- under Section 111(m) and (d) of the Customs Act, 1962 and demanding the customs duty of Rs.40,66,835/- under Section 28(4) along with interest under Section 28AA and penalty under Section 114A and 112(a) of the Customs Act, 1962. The show cause notice also proposed penalty on Shri Atul Agarwal, Director of M/s. ASR Multimetals under Section 112(a) of the Customs Act, 1962 and penalty on M/s. A Kumar & Brothers, M/s. Adinath Tradelinks, M/s. Agarwal Sons, M/s. Akbani Traders, M/s. Ishita Overseas, M/s. Jhanvi Impex, M/s. Param Exim, M/s. Morsons Enterprise and M/s. Trimurti Impex under Section 112(b) of the Customs Act,1962.
1.2 The show cause notice was decided by the Additional Commissioner vide order dated 23.01.2014 wherein, he confirmed the duty demand of Rs.40,66,835/- on the appellant M/s. ASR Multimetals along with interest under Section 28AA and imposed equal penalty of Rs.40,66,835/- on them under Section 114A of the Customs Act, 1962. He also imposed following penalty on various co-noticees:-
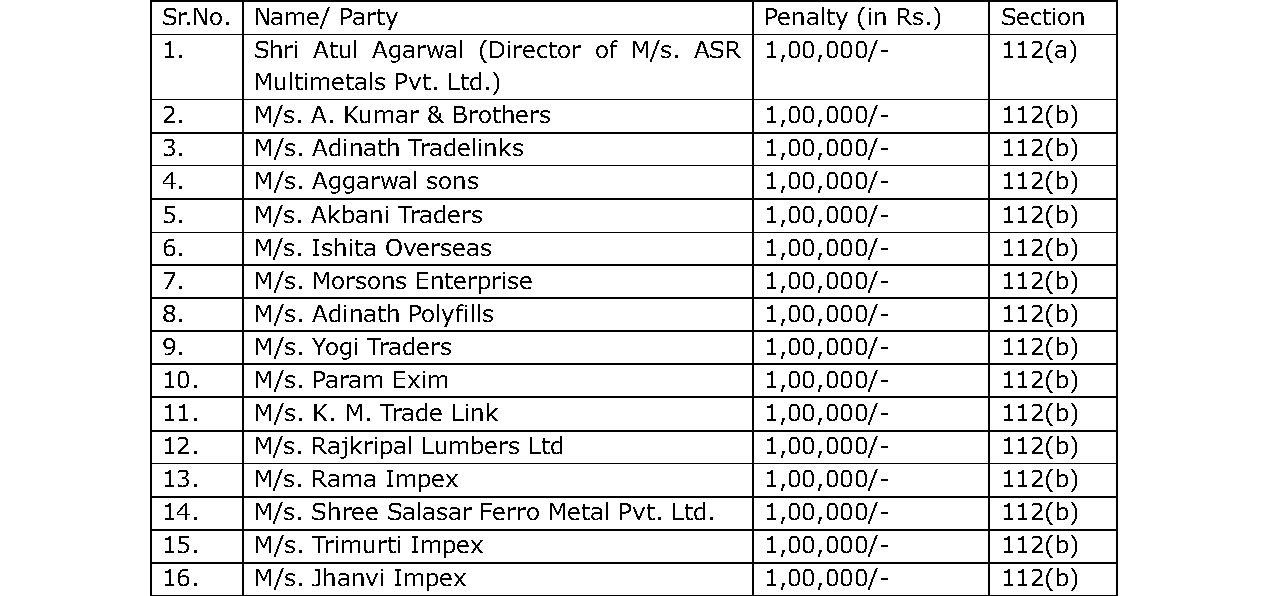
1.3 Being aggrieved with the above order, parties mentioned at Sr.1 to 9 of the above table and M/s. ASR Multimetals Pvt. Ltd. filed appeals before the Commissioner (Appeals) who after considering their submissions, concluded vide impugned order dated 11.12.2014 that appeals filed by M/s. ASR Multimetals Pvt. Ltd., it’s Director Shri Atul Agarwal, M/s. A. Kumar & Brothers, M/s. Adinath Tradelinks, M/s. Aggarwal Sons, M/s. Akbani Traders, M/s. Ishita Overseas, M/s. Morsons Enterprises and M/s. Adinath Polyfills have no merit and therefore, he upheld the said order in respect of above 9 appellants by rejecting their appeals. He however, set aside penalty imposed on M/s. Trimurti Impex on the ground that the proprietor of the said firm had expired and therefore, proceedings in the case abate. Aggrieved with the above order, all the 9 parties filed appeals before this Tribunal. The main appeal is of M/s. ASR Multimetals which involve duty demand, interest and penalty whereas, other appellants are aggrieved by imposi