Back


2026 Supreme(Online)(CESTAT) 2061
CUSTOMS EXCISE & SERVICE TAX APPELLATE TRIBUNAL
Dilip Gupta, President, P. Anjani Kumar, Technical Member
Commissioner of Customs – Appellant
Versus
Adani Enterprises Limited – Respondent
CUSTOMS APPEAL NO. 86116 OF 2024 | C/86117/2024 | C/86118/2024 | C/86119/2024 | C/86120/2024 | C/86121/2024
For the Appellants/Petitioners: Shri Shambhoo Nath
For the Respondents: Shri V.S. Nankani, Shri J.H. Motwani, Shri Sachin Mishra, Shri Archi Aditya
Identical show cause notices based on the same investigation, evidence, and documentary record, where prior similar proceedings have attained finality in favor of the importer, are not sustainable. Uncertified electronic documents are inadmissible as evidence to support allegations of over-invoicing.
Headnote:(A) Customs Act, 1962 - Section 14, 111(m), 112(a), 114AA - Customs Valuation (Determination of Value of Imported Goods) Rules, 2007 - Rule 3, 4, 11, 12 - Valuation of imported goods - Rejection of declared value - The core issue concerns the rejection of transaction value and redetermination of assessable value in a series of related imports. The Tribunal held that where an investigation for alleged over-invoicing has already been concluded in favor of the importer by the authorities, and those findings have attained finality before the Supreme Court, subsequent proceedings based on the same investigation and set of documents must result in the same outcome. (Paras 39, 41, 51, 52)
(B) Evidence - Admissibility - Requirement of certificate under Section 138C(4) of Customs Act, 1962 - Documents, specifically computer printouts received from overseas entities, lack the mandatory certification and are therefore inadmissible as evidence to support allegations of over-invoicing. (Para 51, 52)
Facts of the case:
Multiple appeals were filed by the Revenue challenging an order that dropped proceedings initiated by a show cause notice. The notice alleged over-invoicing in relation to the import of machinery and equipment. It was argued by the respondents that the allegations were previously determined against the Revenue in prior proceedings involving the same investigation and evidentiary record, which were upheld up to the Supreme Court.
Findings of Court:
The Court held that the department could not re-litigate the same issue based on identical evidence, especially when previous proceedings had concluded in favor of the importers. Furthermore, the reliance on uncertified documents retrieved from overseas bankers was deemed invalid under the law. The Court observed that the transaction values represented arms-length pricing determined through competitive bidding.
Issues: Whether the declared transaction value could be rejected under the valuation rules and whether the goods were liable for confiscation and penalty due to alleged over-invoicing.
Ratio Decidendi: Where an issue of fact has reached finality up to the Supreme Court for the same investigation and evidence, subsequent identical show cause notices cannot be sustained. Additionally, electronic documents without the mandated statutory certification (under Section 138C of the Act) lack evidentiary value to support a charge of over-invoicing.
Result: Appeals dismissed.
| Table of Content |
|---|
| 1. prior investigation and litigation history regarding show cause notices. (Para 1 , 2 , 3 , 4 , 5 , 6 , 7) |
| 2. framework for parties' contentions and the scope of the present appeals. (Para 8 , 9 , 10 , 11) |
| 3. factual overview of import transactions and epc contract structures. (Para 12 , 13 , 15 , 16 , 17 , 18 , 19 , 20 , 21 , 22 , 23 , 24 , 25 , 26 , 27 , 28 , 29 , 30 , 31 , 32 , 33 , 34 , 35) |
| 4. res judicata or finality of earlier adjudication binding on subsequent proceedings. (Para 36 , 37 , 38 , 39 , 40 , 41 , 42 , 43 , 44 , 45) |
| 5. valuation of imported goods and inadmissibility of evidence without proper certification. (Para 46 , 47 , 48 , 49 , 50 , 51 , 52 , 53 , 54 , 55 , 56 , 57) |
FINAL ORDER No’s. 85706-85711/2026
JUSTICE DILIP GUPTA:
All the aforesaid six appeals have been filed by the Commissioner of Customs (Import-I), Mumbai, (the Commissioner) to assail the order dated 21.12.2023 passed by the Principal Commissioner of Customs (Adjudication), Mumbai, (the Principal Commissioner) that has dropped the proceedings initiated against the six respondents by the show cause notice dated 31.08.2016.
C/86116/2024 & 5 others
2. The respondents in the aforesaid six Customs Appeals are:
| Appeal No. | Name of the respondents |
|---|---|
| C/86116/2024 | Adani Enterprises Limited, (AEL) |
| C/86117/2024 | Adani Renewable Energy LLP, (AREL) |
| C/86118/2024 | Adani Hazira Port Private Limited, (AHPPL) |
| C/86119/2024 | Adani Port and Special Economic Zone Limited, (APSEZL) |
| C/86120/2024 | Adani International Container Terminal (P) Limited, (AICTPL) |
| C/86121/2024 | Adani Vizag Coal Terminal Private Limited, (AVCTPL) |
3. It transpires from the records that a common investigation by the Directorate of Revenue Intelligence, (DRI) led to issuance of three separate show cause notices. The details of the show cause notices and the parties are as follows:
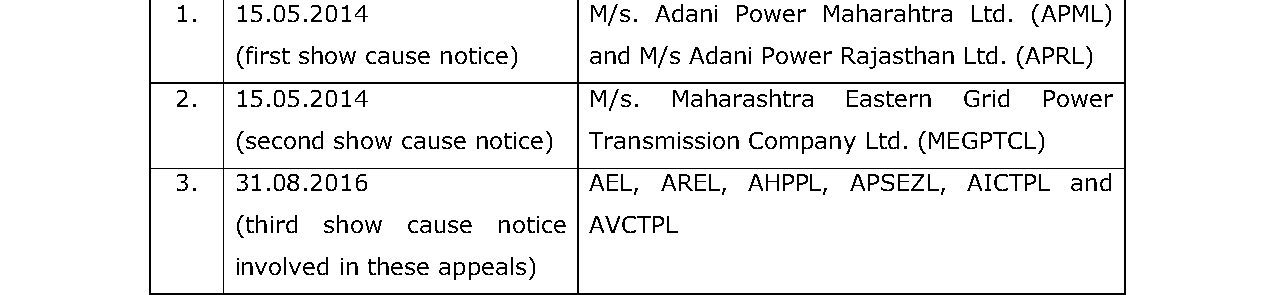
4. It also transpires from the records that the first show cause notice dated 15.05.2014 was adjudicated by the Additional Director General, DRI (Adjudication), (the Additional Director General) by order dated 22.08.2017. The second show cause notice also dated 15.05.2014 was adjudicated by the Additional Director General by order dated 17.10.2017. The Additional Director General dropped the proceedings initiated by these two show cause notices, each dated 15.05.2014.
C/86116/2024 & 5 others
5. It also transpires from the records that as the Additional Director General had discharged the two show cause notices dated 15.05.2014, the proceedings of the third show cause notice, which has given rise to these six appeals, were transferred to the call book and this fact was communicated to the respondents by a letter dated 26.09.2019.
6. The department challenged the two orders dated 22.08.2017 and 17.10.2017 before the Tribunal. The Tribunal, by final order dated 18.07.2022, dismissed Customs Appeal No. 87758 of 2017 filed by the department to assail the order dated 22.08.2017 passed by the Additional Director General dropping the proceedings initiated by the first show cause notice dated 15.05.2014. The department had also filed Customs Appeal No. 85476 of 2018 to assail the order dated 17.10.2017 passed by the Additional Director General discharging the second show cause notice dated 15.05.2014. This appeal of the department was also dismissed by the order dated 17.10.2017. These two orders of the Tribunal were assailed by the department by filing Civil Appeals before the Supreme Court. Both the Civil Appeals were dismissed by the Supreme Court on 27.03.2023.
7. The third show cause notice dated 31.08.2016 was thereafter taken up for adjudication by the Principal Commissioner.
8. It for this reason that Shri V.S. Nankani, learned senior counsel appearing for the respondents assisted by Shri J.H. Motwani, Shri Sachin Mishra and Shri Archi Aditya submitted that these six appeals filed by the department should also be dismissed as they are squarely covered by the aforesaid two decisions of this Tribunal against which the Civil Appeals filed by t