Back


2026 Supreme(Online)(CESTAT) 3311
CUSTOMS, EXCISE & SERVICE TAX APPELLATE TRIBUNAL ALLAHABAD
Sanjiv Srivastava, Member (Technical)
Ashtvinayak and Company – Appellant
Versus
Commissioner of Customs (Preventive), Lucknow – Respondent
FINAL ORDER NO.70364/2026 | Order-in-Appeal No.124-CUS/APPL/LKO/2022 | Order-in-Original No.09/JC/2021-22
Important Points
Subject
Customs Law - Confiscation and Penalty
Act Referred
Intellectual Property Rights (Imported Goods) Enforcement Rules, 2007: R.11, R.7(1)(b)
Headnote
(B) Section 118 and 119 - Goods used for concealment of undeclared or prohibited goods are liable for confiscation. Redemption fine must be reasonable and proportional to the value of the goods. (Para 4.4)
(C) Section 112 - Imposition of penalty - *Mens rea* is not always a prerequisite for penalty for contravention of statutory obligations under the Customs Act; the principle of "Caveat Emptor" (buyer beware) applies to importers regarding the nature and genuineness of imported goods. (Paras 4.7, 4.8)
Facts of the case:
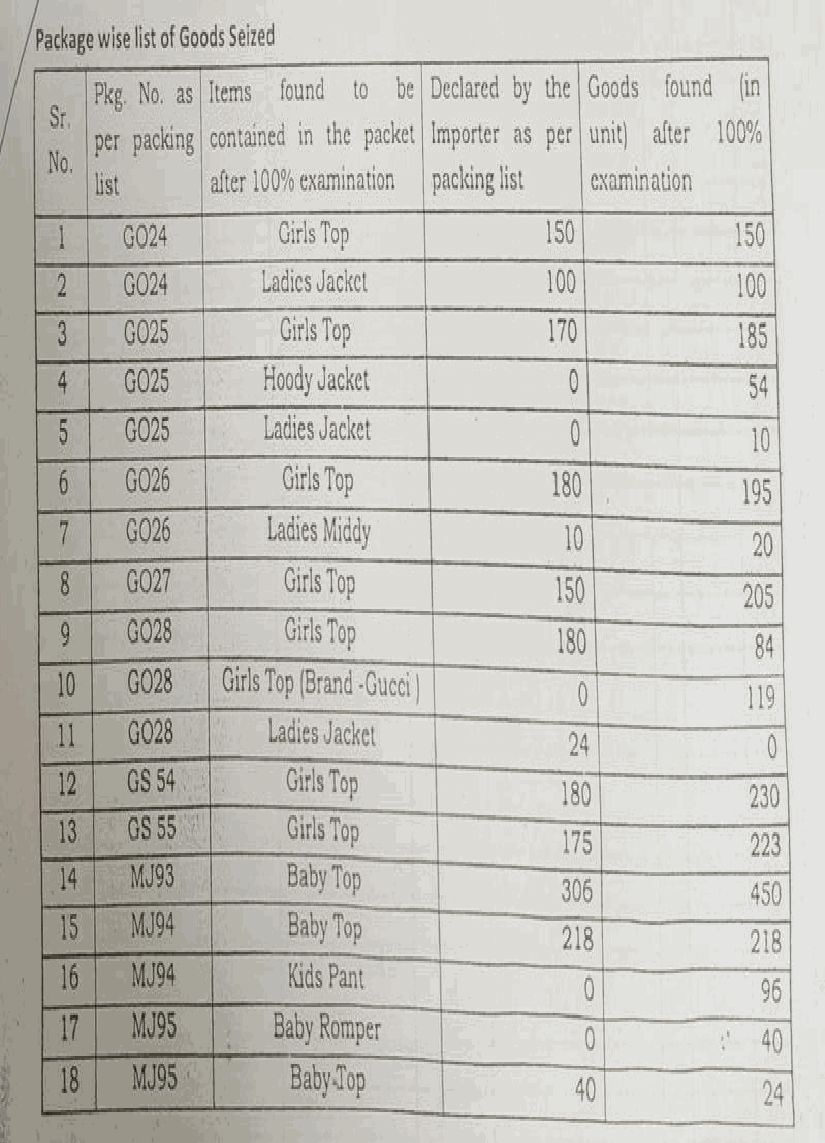
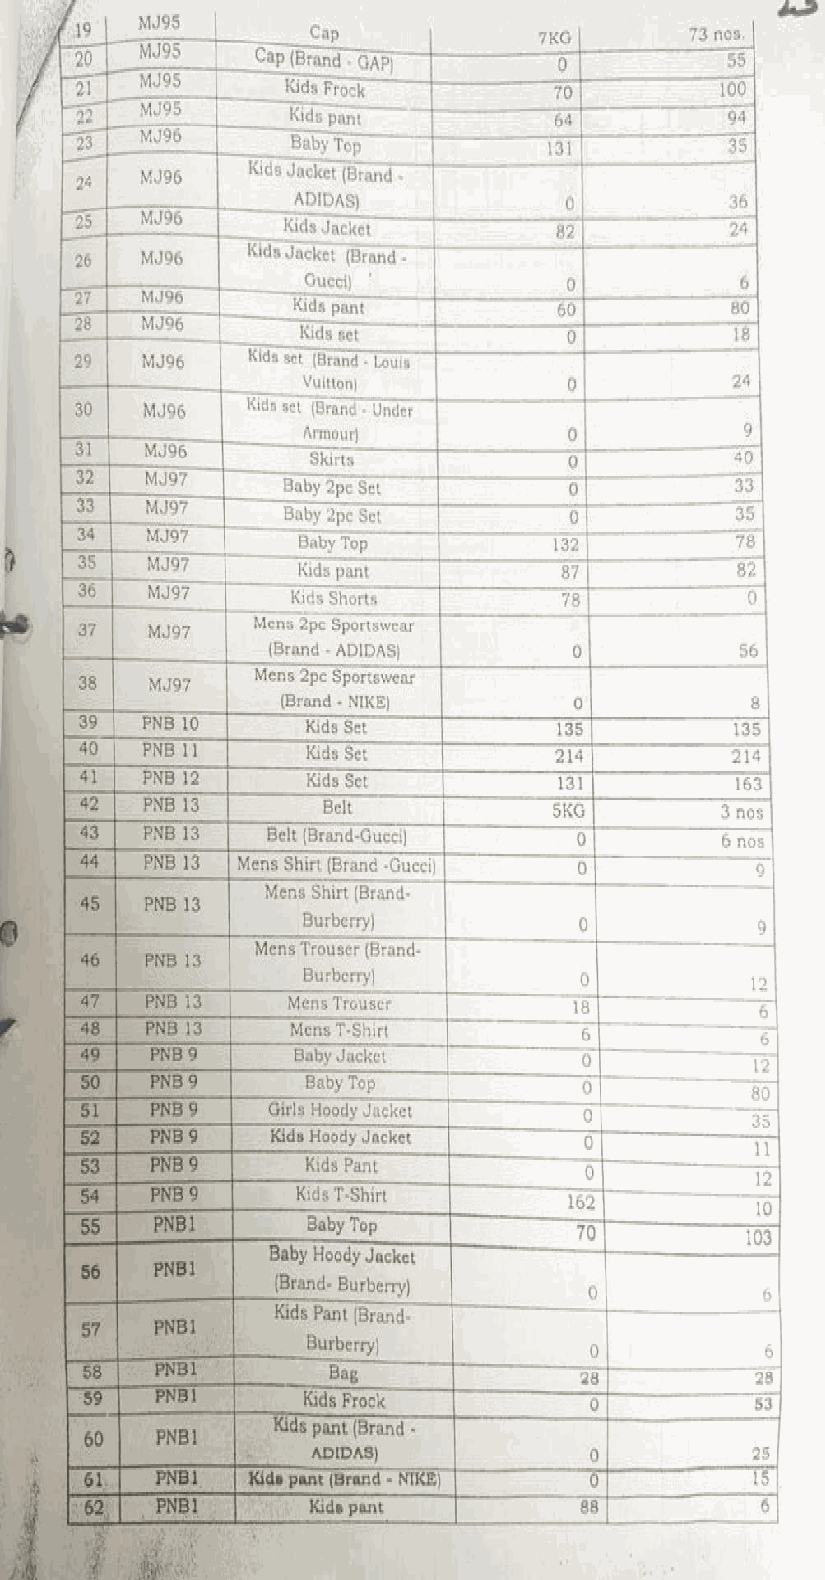
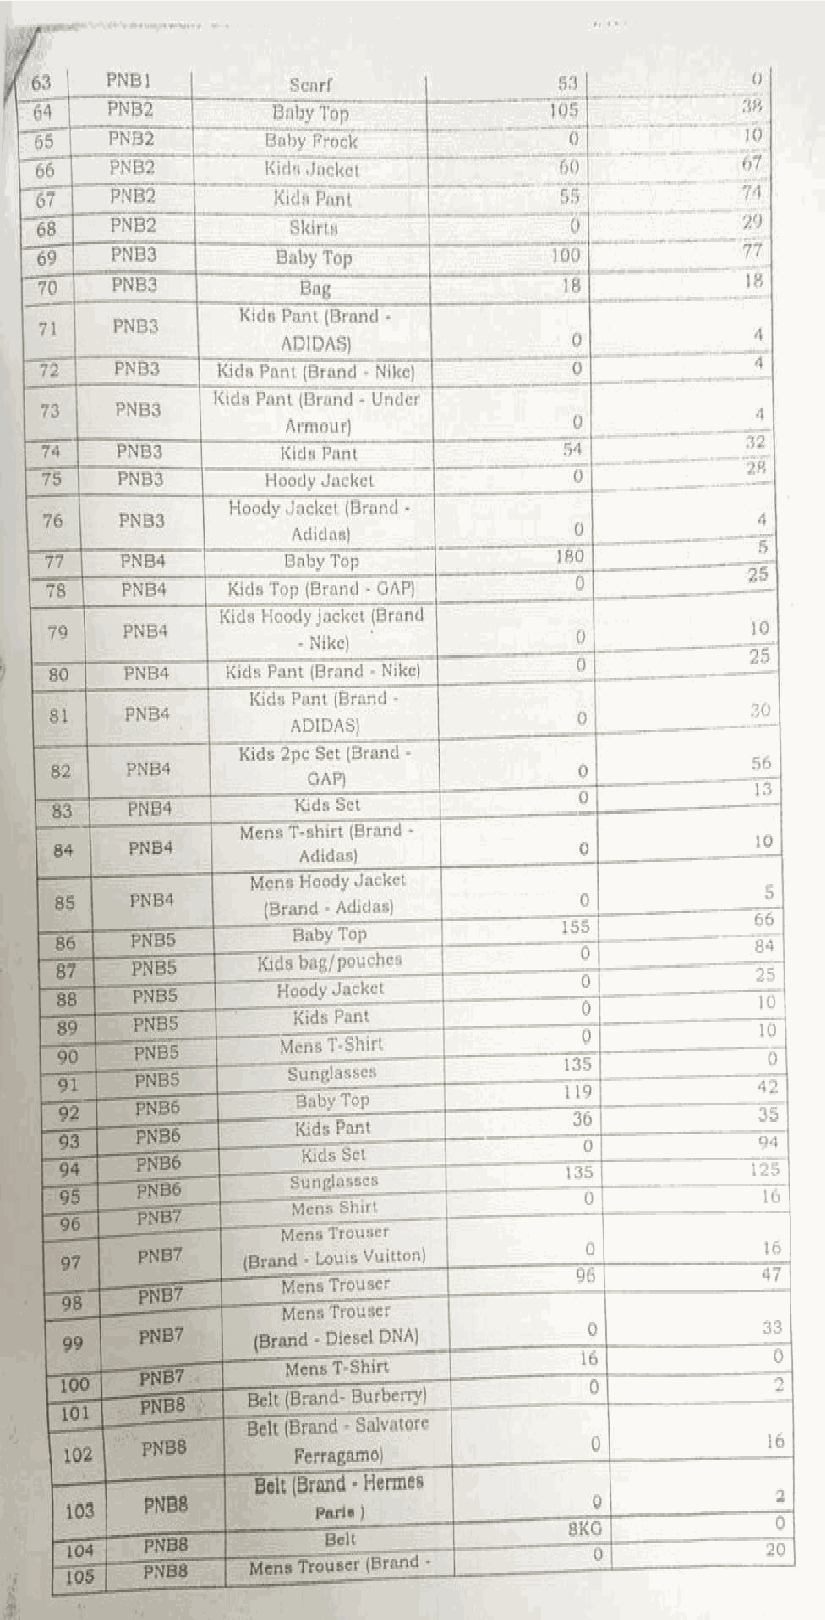
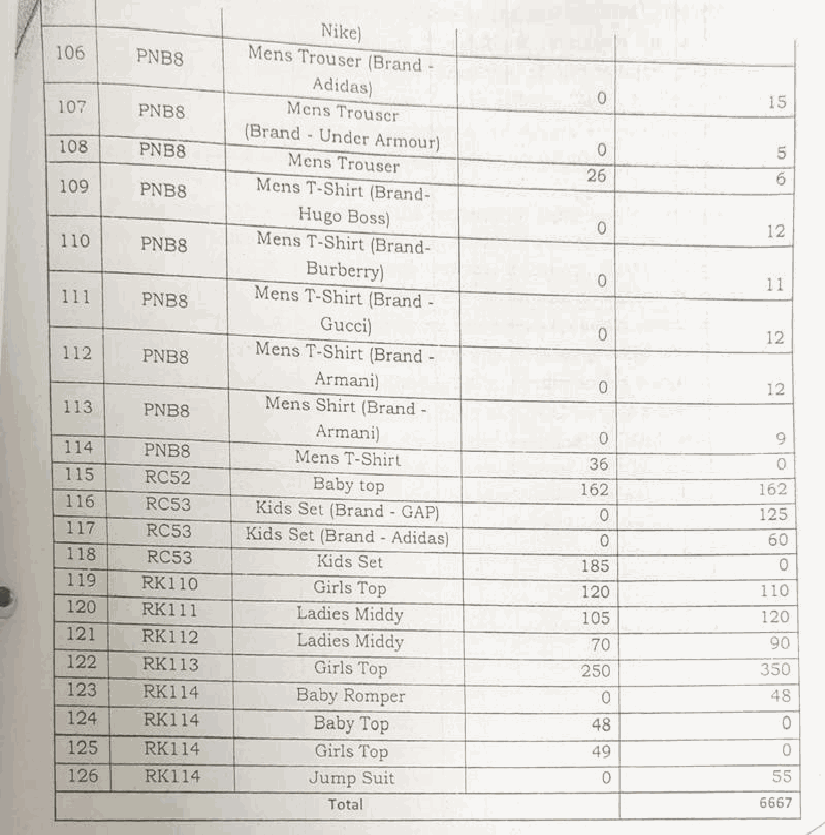
An importer brought a consignment of garments which, upon 100% examination, were found to be grossly mis-declared in terms of quantity, description, and value. A large quantity of undeclared branded clothes was found concealed within the declared goods, violating intellectual property rights and customs regulations. The importer contended that the branded goods were sent by mistake by the foreign supplier and claimed innocence, seeking a lenient view.
Findings of Court:
The declared goods used to conceal undeclared and prohibited goods are liable for confiscation under Sections 118 and 119 of the Customs Act. The plea that the foreign supplier mistakenly sent thebranded goods was rejected due to the lack of supporting contemporaneous evidence, such as emails or purchase orders. While the liability for confiscation and penalty was upheld, the redemption fine and the penalty amount imposed by the lower authorities were found to be excessive.
Issues: Whether declared goods used to conceal undeclared branded goods are liable for confiscation and whether a claim of supplier error without evidence exempts an importer from liability and penalties.
Ratio Decidendi: The court ruled that the concealment of prohibited goods renders the concealing goods liable for confiscation. Importers are responsible for the accuracy of their declarations, and a plea of supplier mistake cannot be accepted without evidence. Additionally, penalties for statutory contraventions under the Customs Act are applicable even in the absence of *mens rea*.
Result: Appeal is partially allowed.
Legal Category Hierarchy
-
customs law
- confiscation of goods
- penalties
- redemption fine
- valuation of goods
- intellectual property rights enforcement
-
practice and procedure
- appeal
For the Appellants/Petitioners: Anuj Agarwal
For the Respondents: Abhishek Mukharjee
SANJIV SRIVASTAVA:
This appeal is directed against Order-in-Appeal No.124-CUS/APPL/LKO/2022 dated 22/02/2022 passed by Commissioner (Appeals) Customs, Central Excise & CGST, Lucknow. By the impugned order, Commissioner (Appeals) has upheld the Order- in-Original No.09/JC/2021-22 dated 27.05.2021 wherein following has been held:-
“ORDER
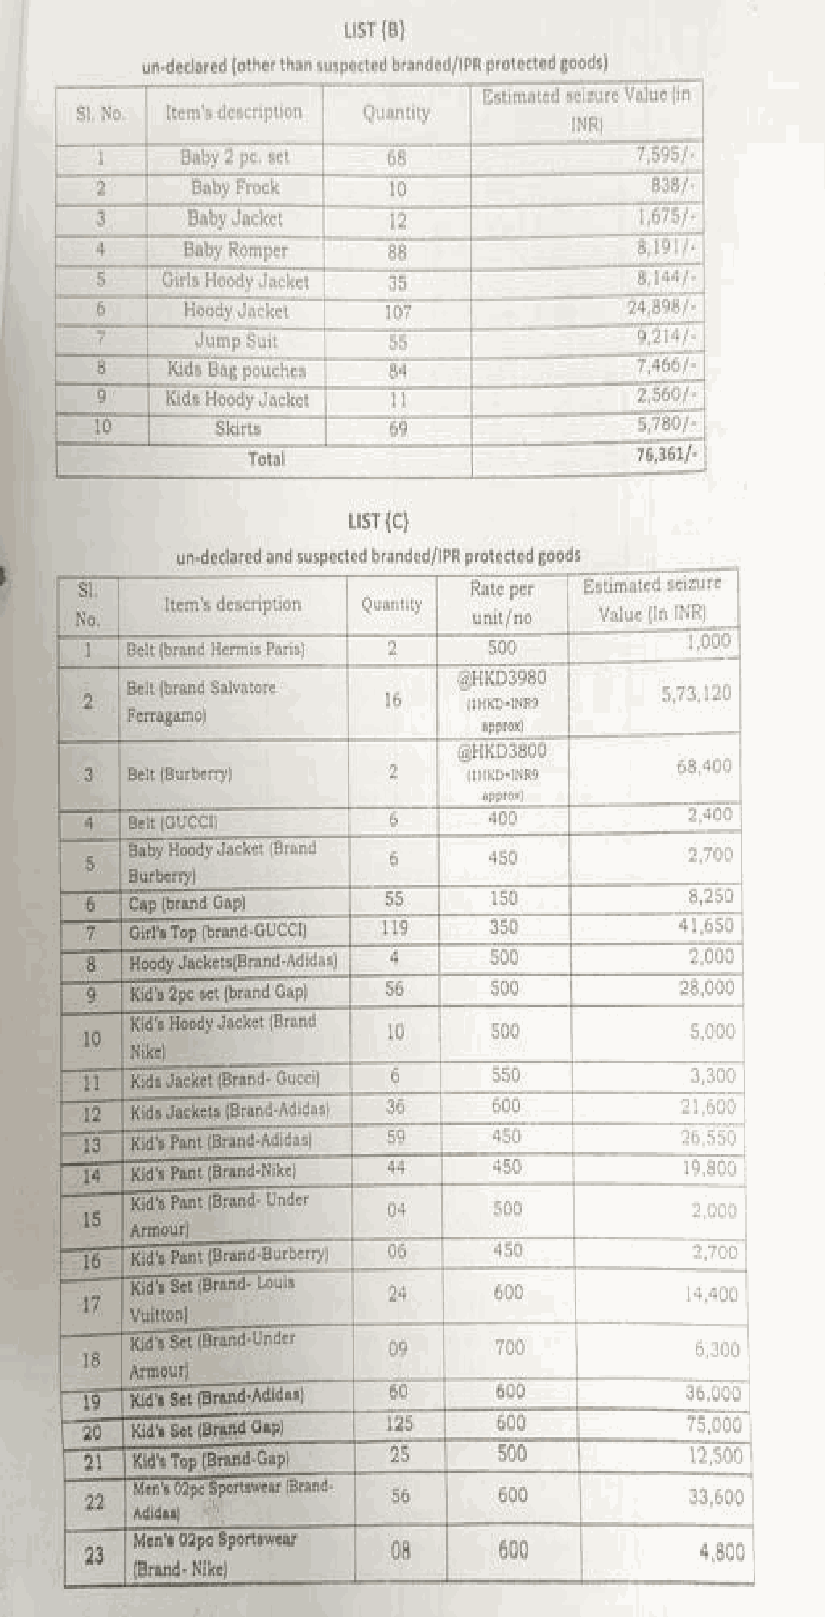
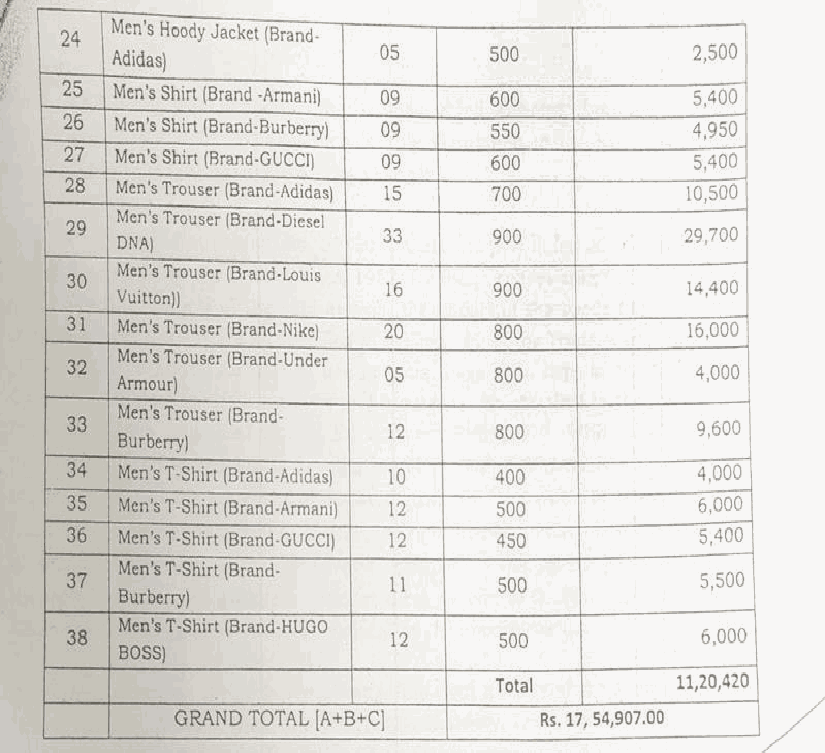
(i) I order for absolute confiscation of the seized undeclared branded clothes valuing Rs 4,21,850/ as mentioned in the List, (C) of SCN (excluding the goods mentioned at Sl. No. 2, 6, 20, 21 & 29 of the list) under Section 111(d) of the Customs Act, 1962.
(ii) I order for absolute confiscation of the seized undeclared branded clothes valuing Rs. 6,98,570/- mentioned at Sl No. 2, 6, 20, 21 & 29 in the List (C) of SCN under Section 111(f), 111(i), 111(1), 111(m) of the Customs Act, 1962.
(iii) I order for confiscation of the seized undeclared clothes valued at Rs 76,361/-mentioned in the List (B) of SCN under Section 111(1), 111(i), 111(1), 111(m) of the Customs Act, 1962. However, I give an option for redemption of said garments to its lawful owner as envisaged under Section 125 of the Customs Act, 1962 on payment of redemption fine Rs 11500/- along with applicable rate of Customs duty leviable thereon within the time as stipulated under Section 125 (3) of the Customs Act, 1962, in lieu of the confiscated foreign origin garments valued at Rs.76,361/-. The cash security deposited by the noticee at the time of provisional release of goods can be appropriated against redemption fine imposed as above under Section 125 of the Act.
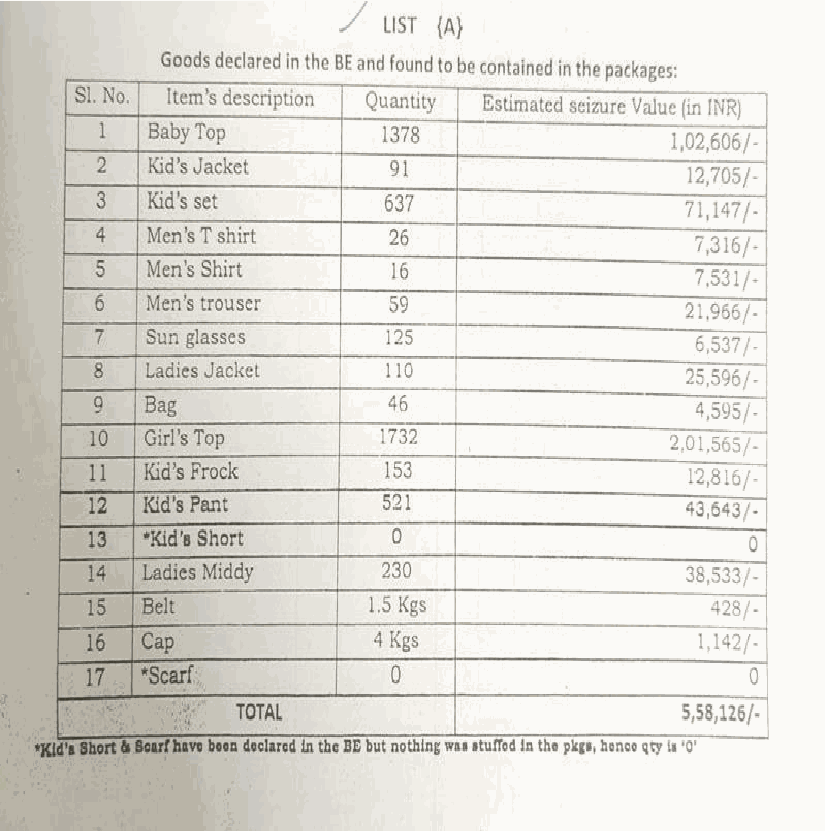
(iv) 1 order for confiscation of the seized declared clothes valued at Rs. 5,58,126/- mentioned in the List (B) of SCN under Section 118 of the Customs Act, 1962. However, I give an option for redemption of said garments to its lawful owner as envisaged under Section 125 of the Customs Act, 1962 on payment of redemption fine Rs 85,000/- along with applicable rate of Customs duty leviable thereon, within the time as stipulated under Section 125 (3) of the Customs Act, 1962, in lieu of the confiscated foreign origin garments valued at Rs. 5,58,126/-. The cash security deposited by the noticee at the time of provisional release of the goods can be appropriated against redemption fine imposed as above under Section 125 of the Act. Duty already paid by the noticee may be adjusted against total Customs duty liability.
(v) I impose penalty of Rs 4,00,000/- (Rs. Four lakh only) under Section 112(a) & 112(b) of the Customs Act, 1962 on the Noticee M/s Ashthvinayak & Co., Lucknow.”
2.1 Appellant having IEC No.0610004026 had filed Bill of Entry No. 4699807 dated 30.08.2019 with the customs for clearance of goods contained in 32 packages brought by them under Airway Bill No.065-33160713 dated 27.08.2019 from Guangzhou, China, for home consumption. These goods have been supplied by M/s. Nand Enterprise Co. Ltd., Room No. 909, Wayson Commercial Building, 28 Connaught Road, West Sheung Wan, Hong Kong, China under Invoice No. LK003060 dated 27.08.2019.
2.2 The said Bill of Entry was assessed on value as declared by the appellant for value Rs.5,51,179/- and Customs duty of Rs.1,95,556/ (Rs.1,59,167/-+IGST-Rs.36,389/-) by the proper officer. After deposit of the customs duty, they were presented by thee importer for examination by the Customs on 02.09.2019. During the course of examination of the randomly selected packages, in presence of the importer Shri Gaurav Shukla, Proprietor of appellant, the goods contained in the packages were not found in consonance with the declaration made by the importer in the packing list dated 27.08.2019 appended with the Bill of Entry. Therefore, 100% examination of the consignments was directed. The importer was directed to be present on the next date i.e. 03.09.2019 for 100% examination of the consignment, but the importer, vide his letter dated 02.09.2019 informed that he would not be available for examination from 03.09.2019 to 08.09.2019 due to Ganesh Uts