


 Back


2025 Supreme(Online)(DEL) 809
HIGH COURT OF DELHI
Prathiba M. Singh, Rajneesh Kumar Gupta, JJ
M/S PRENDA CREATIONS PVT. LTD. – Appellant
Versus
UNION OF INDIA & ORS. – Respondent
W.P.(C) 2767/2025
MANUJ SABHARWAL
The court emphasized the necessity of adequate documentation to establish the country of origin for imported goods under SAFTA provisions, allowing the Petitioner to clarify compliance with customs requirements.
Headnote:
(A) Constitution of India - Article 226/227 - Customs Act, 1962 - Provisional release of goods - The Petitioner sought release of imported fresh garlic from Afghanistan under SAFTA, asserting no duty applicable - Customs Department required additional documentation to verify country of origin, claiming the Petitioner did not provide necessary transit documents - The court allowed the Petitioner to clarify the situation with the Customs Department, emphasizing the need for proper documentation to establish compliance with SAFTA provisions. (Paras 2-12)
(B) Customs Procedures - The court noted that the Customs Authorities assumed a lack of requisite documentation for establishing the goods' origin, impacting the claim for preferential duty rates. (Paras 4-5)
Facts of the case:
The Petitioner imported fresh garlic from Afghanistan, claiming it was exempt from duty under SAFTA, but the Customs Department contested the origin due to documentation issues.
Findings of Court:
The court granted the Petitioner an opportunity to present necessary documents to the Customs Department for verification of the goods' origin and compliance with SAFTA provisions.
Issues: The main issues included the adequacy of documents provided by the Petitioner to establish the country of origin and the implications of these documents on the duty calculation.
Ratio Decidendi: The court underscored the importance of proper documentation in customs procedures and the need for the Petitioner to clarify the origin of goods to meet the requirements under SAFTA.
Result: Petition disposed of with directions.
ORDER :
1. This hearing has been done through hybrid mode.
2. The present petition has been filed by the Petitioner under Article 226/227 of the Constitution of India inter alia seeking release of the goods i.e., fresh garlic which has been imported by the Petitioner from Afghanistan without any condition of furnishing of a bank guarantee.
3. The case of the Petitioner is that it had imported one consignment of fresh garlic from its foreign supplier in Afghanistan via Dubai. According to the Petitioner, Afghanistan falls under the South Asian Free Trade Area (SAFTA) region and therefore such products are importable without payment of any duty.
4. The stand of the Customs Department is that Petitioner has not shown adequate documents to establish the country of origin as Afghanistan. Ms. Anushree Narain, ld. Counsel for the Department further points out that the port of loading, as per the Bill of Lading dated 21st January, 2025 (Annexure P-9), is in UAE and no documents have been given to establish the origin of the goods from the SAFTA region.
5. Ld.Counsel for the Petitioner relies upon various documents which are attached with this petition in order to argue that the transit certificate clearly shows that the country of origin of the goods is Afghanistan.
6. Ld. Counsel for the Department submits, however, that the documents also show the port of loading as Jebel Ali, UAE. Hence there is a confusion and it is upon the Petitioner to explain the same.
7. A perusal of the impugned order shows that the Customs Authorities have proceeded under the assumption that there is an absence of submission ofrequisitedocumentsincludingthecompletechainoftransitdocuments.The said paragraphs read as under:
“4. On conjoined reading of Rule 12 of Rules of Determination of Origin of Goods under the Agreement on South Asian Free Trade Area (SAFTA), notified vide Notification No. 75/2006-Customs (NT) dated 30.06.2006 and Article 17 of Annexure-B of the Notification No. 75/2006 along with Rule 5 of the Customs (Administration of Rules of Origin under Trade Agreements) Rules, 2020 dated 21.09.2020 and in the absence of submission of requisite documents by the Importer viz. thorough Bill of Lading/complete chain of transit documents, the claim of preferential rate of duty by the Importer appears liable to disallowed without further verification. Further, the Importer has not submitted the PQ clearance report as mandated by RMS for the current Bill of Entry.
5. In view of the above, the duty calculation details in respect of goods imported vide Bill of Entry No. 7516199 dated 30.12.2024 are as under:”
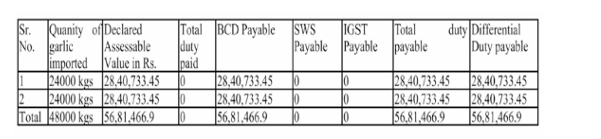
6. The importer vide their email/letter dated 20.01.2025 has requested for provisional release of goods imported vide Bill of Entry No.7516199 dated 30.12.2024. As per aforesaid request letter of the importer, this office has No Objection for provisional release of the seized goods as per CBIC Circular No. 35/2017 dated 16.08.2017 read with Section 110A of the Customs Act , 1962, subject to furnishing of necessary clearance from Plant Quarantine Department. The adjudicating authority may take bond and Bank Guarantee/fixed deposit for differential duty, interest, RF and Penalty in respect of aforesaid BOE, as may deem fit.”
8. It is under the above circumstances that the Petitioner appears to have been directed by the Respondent/Department to furnish a bank guarantee.
9. However, the Petitioner at this time submits that these documents showing the Country of Origin of the goods were, in fact, available with the Respondent/Department at the time of passing the impugned order requiring Petitioner to present a bank guarantee.
10. Considering the facts and circumstances, this Court is inclined to grant an opportunity to the Petitioner to clarify the actual position before the Respondent/Department.
11. Accordingly, let the present writ petition and the documents annexed therein be submitted by the Petitioner to the Commissioner of Customs (Preventive) NCH, New Delhi and l







