


 Back





2025 Supreme(Online)(GSTARA) 1
GST APPELLATE
Sh. Anil Kumar Gupta, Member (Technical)
DGAP – Appellant
Versus
GOPAL TEKNOCON PVT. LTD. – Respondent
NAPA/15/PB/2025
Compliance with Section 171 of the CGST Act mandates transfer of ITC benefits, duly achieved by the Respondent.
Headnote:In evaluating the compliance of Section 171(1) of the CGST Act, this Tribunal considered the findings of the Directorate General of Anti-Profiteering regarding the passing of Input Tax Credit benefits. The Respondent was determined to have fulfilled obligations by transferring identified residual ITC benefits to the applicant. The Tribunal affirmed the DGAP's findings, noting that compliance was adequately achieved, thus concluding the investigation and closing proceedings. The final order stated: 'The investigation stands concluded with compliance fully achieved.'
| Table of Content |
|---|
| 1. investigation and reporting on itc compliance. (Para 1 , 2) |
| 2. findings on itc benefits passed on. (Para 6 , 8 , 10) |
| 3. closure of proceedings and final order. (Para 7 , 9 , 13 , 14 , 15) |
| 4. summary of compliance with cgst provisions. (Para 11 , 12) |
ORDER
1. This Tribunal has received the detailed investigation report dated 31.08.2022 from the Directorate General of Anti–Profiteering (DGAP), submitted under Rule 129(6) and Rule 133(4) of the Central Goods and Services Tax Rules, 2017 , in the matter of M/s Gopal Teknocon Private Limited and M/s Indian Oil Corporation Limited. The proceedings arise under the provisions of Section 171 of the Central Goods and Services Tax Act, 2017 , concerning alleged non-passing of Input Tax Credit (ITC) benefits related to the contract for Maintenance and Inspection of Crude Oil Storage Tanks.
2. The complaint was originally filed by M/s Indian Oil Corporation (Pipeline Division), Rajkot, alleging that the Respondent had not passed on the benefit of Input Tax Credit by way of commensurate reduction in price for the contracted works undertaken post-GST implementation. The Standing Committee, after due consideration, referred the matter to the DGAP under Rule 129(1) of the Rules on 07.08.2020, and the DGAP issued a Notice of Investigation dated 04.09.2020, covering the period from 01.07.2017 to 31.07.2020
3. The DGAP completed its initial investigation and submitted a report dated 29.01.2021 before the erstwhile National Anti– Profiteering Authority (NAA), concluding that the Applicant had voluntarily agreed to the prices and contract modifications, and therefore there was no evidence of profiteering. However, the erstwhile NAA, vide Interim Order No. 03/2022 dated 10.05.2022, directed the DGAP to re-investigate under Rule 133(4) of the CGST Rules, 2017, with specific focus on whether the discounts extended during negotiations were linked to GST benefit, and whether the methodology employed by the Respondent adequately captured the passing on of ITC benefits.
4. The DGAP reinvestigated and, after evaluating fresh submissions, filed its second report dated 31.08.2022, received by NAA on 05.09.2022. The report summarised that negotiations for contract finalization were initiated in the pre-GST period, whereas execution and procurement occurred only after 01.07.2017. Accordingly, the DGAP examined revised pricing, tender amendments, and payments, particularly noting that GST-linked discounts were granted subsequently on 24.10.2017 and 21.03.2018, amounting to Rs. 11,61,246.84/- for each Tanks MT-05 and MT- 03 respectively.
5. On comparative analysis of pre- GST and post-GST credit positions, DGAP presented the following findings. For this exercise data of both the parties (the Respondent and the Applicant) has been examined and calculations worked out as per table- A as under:
Table-A
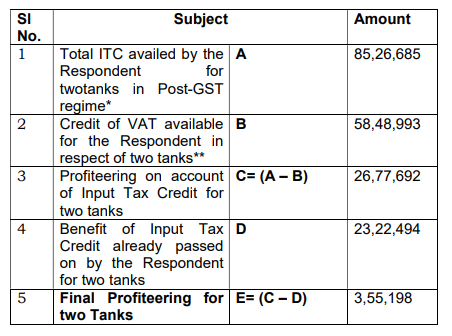
6. The Total ITC availed post-GST was Rs. 85,26,685/- as against a pre-GST notional VAT credit of Rs. 58,48,993/-. The net incremental ITC benefit was thus Rs. 26,77,692/-, of which Rs. 23,22,494/- had already been passed on by way of GST-related discounts. The differential balance of Rs. 3,55,198/- was identified as the residual ITC benefit to be passed on to IOCL. Based on this quantification, the DGAP recommended transfer of Rs. 3,55,198/- to IOCL to ensure complete compliance with Section 171 (1) of the CGST Act.
7. The erstwhile NAA, through communication dated 09.09.2022, directed the Respondent to submit a written response and justification, which was not filed. Subsequently, the matter remained pending until the case was transferred to the GSTAT, Principal Bench, following Notification No. 18/2024–Central Tax dated 30.09.2024.
8. Upon constitution of this Bench, the hearing took place on 25.09.2025 where the Respondent was granted one final opportunity vide order dated 25.09.2025 to appear and file written submissions on the DGAP’s findings.
9. The Respondent, through its Director, submitted a detailed









