Back


2026 Supreme(Online)(GSTARA) 29
GSTAT Principal Bench at Delhi Division Bench Court No. Court II
APL/54/PB/2026
VISHAL CHAUDHARY .............Appellant
Versus
BANGLA FOODS PRIVATE LTD., DIRECTOR, 32 BABAR ROAD BENGALI MARKET NEW DELHI DLCEN 110001 .............Respondent
Hon’ble Justice Sh. Mayank Kumar Jain, Member(Judicial)
Hon’ble Sh. A. Venu Prasad, Member (Technical)
Counsel for Appellant: SHRI SUBKARAN SINGH, SUPERINTENDENT (APPEARED ADVOCATE VIRTUALLY)
Counsel for Respondent: SHRI ASHU DALMIA, MS. ANKITA JHA, ADVOCATE
Dated: 20.11.2026
Date:- 20.11.2026
 (Justice Mayank Kumar Jain)
 (Sh. A. Venu Prasad)
Form GST APL-04A [See rules 113(1) & 115]
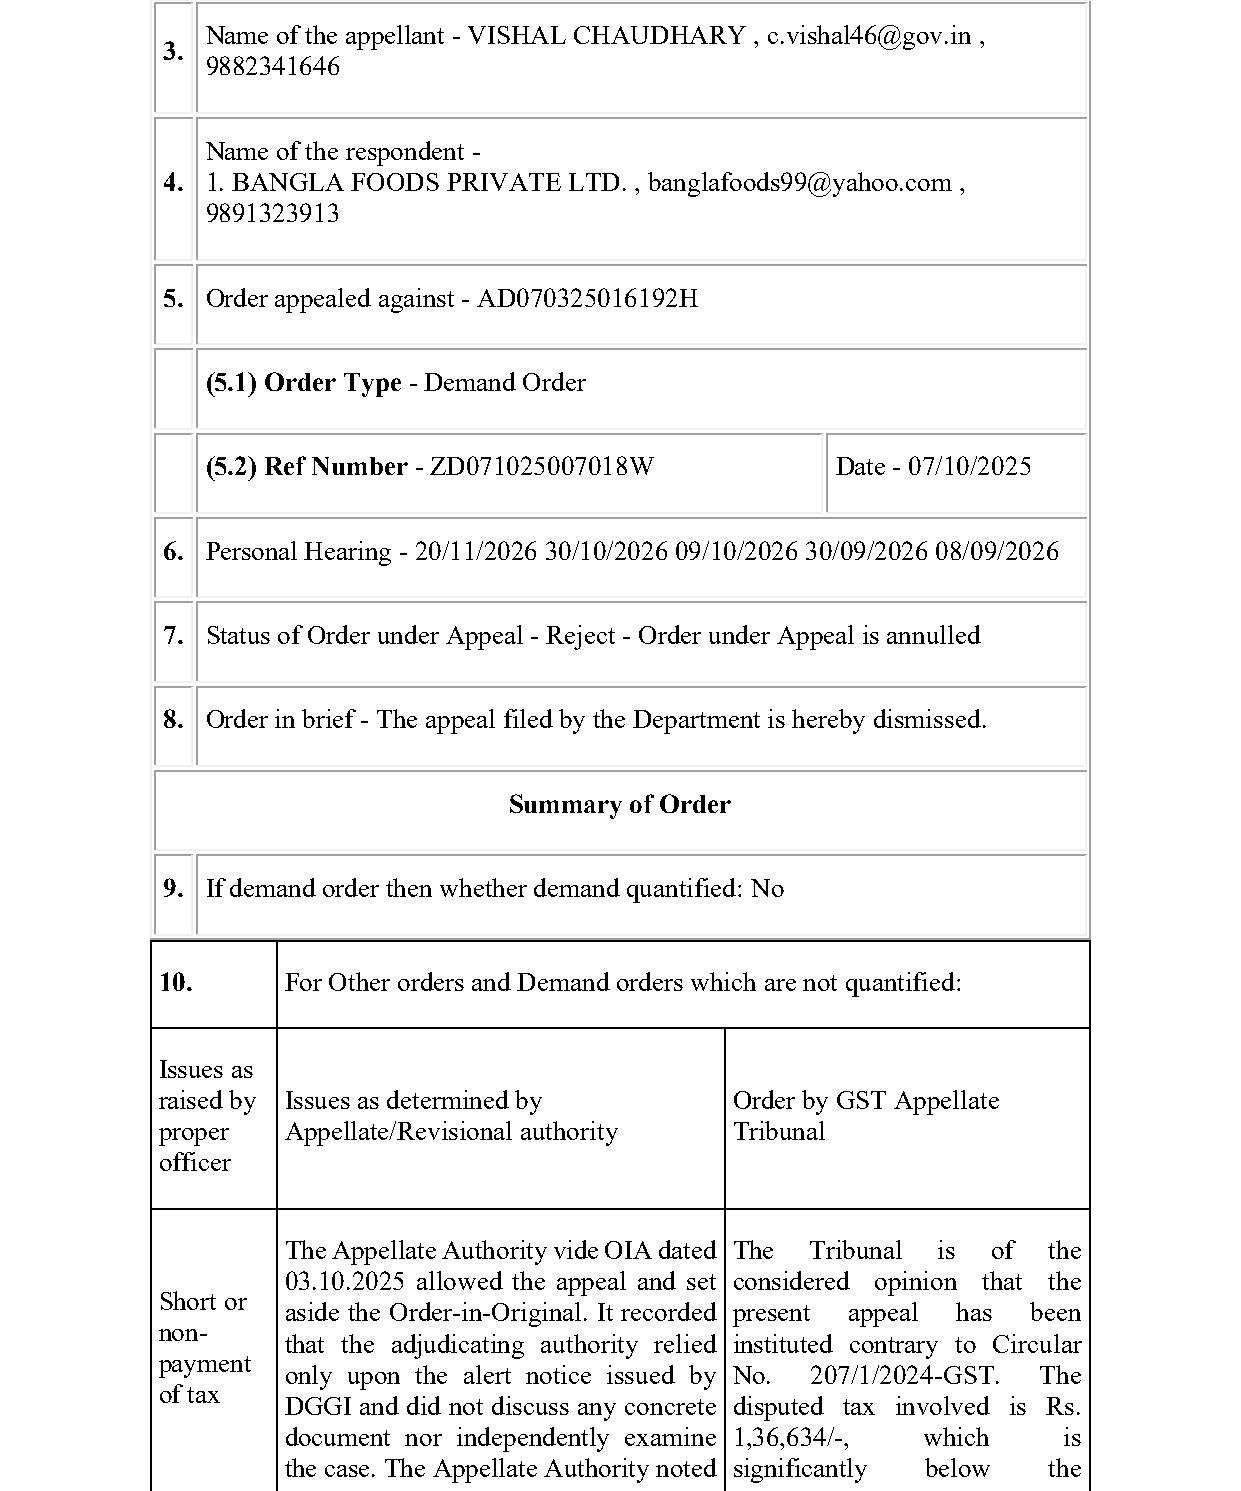
Summary of the order and demand after issue of order by the GST Appellate Tribunal whether remand order : No Order reference no. : ZN510011126000080H Date of order : 20/11/2026
1. GSTIN/Temporary ID/UIN - 07AACCB2863P1ZB
2. Appeal Case Reference no. - APL/54/PB/2026 Date - 18/02/2026
ORDER
Justice Mayank Kumar Jain, Member (Judicial)
Shri A. Venu Prasad, Member (Technical)
(Per Justice Mayank Kumar Jain)
1. The Revenue (hereinafter “the Appellant”) has preferred this appeal under Section 112(3) of the Central Goods and Services Tax Act, 2017 (hereinafter the “CGST Act, 2017”), challenging the Order-in-Appeal No. 1038/JC/Central Tax/Appeal-II/Delhi/2025-26 dated 03.10.2025 (for short, “OIA”) passed by the Joint Commissioner, CGST Appeal-II, Delhi (“Appellate Authority”) whereby the appeal filed by M/s Bangla Foods Private Limited, 111-113, Bangla Sahib Marg, Gole Market, Central Delhi-110001 (hereinafter the “Respondent”) under Section 107(1) of the CGST Act, 2017 was allowed and the Order-in-Original No. 145/2024-25 dated 22.01.2025 (for short, “OIO”), passed by the Superintendent, R-49 Division, Connaught Place, New Delhi (hereinafter, the “Adjudicating Authority”) set aside.
Factual Matrix
2. The Respondent is registered under the CGST Act, 2017 vide GSTIN
07AACCB2863P1ZB.
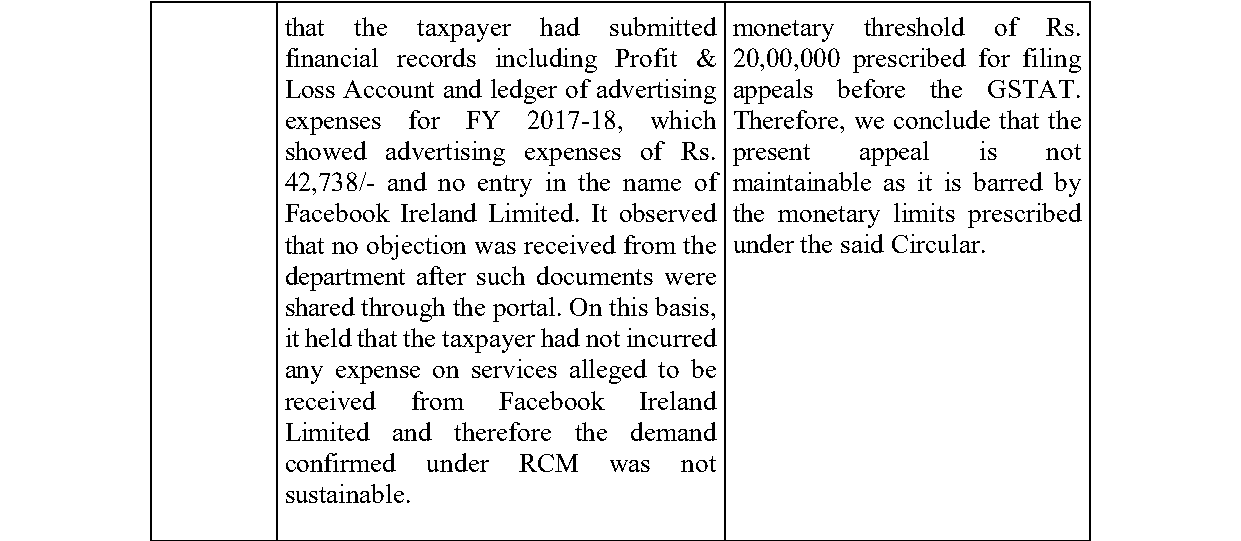
3. Based on an alert issued by the Director General of GST Intelligence, New Delhi, (“the DGGI”), it was alleged that the Respondent had not paid tax of Rs. 1,36,634/- under the Reverse Charge Mechanism (“RCM”) in respect of Online Information and Database Access Retrieval (“OIDAR”) services provided by Facebook Ireland Limited (“FIL”).
4. A show cause notice dated 01.08.2024 (for short “the SCN”) was therefore issued to the Respondent, proposing recovery of the tax under Section 74(1) of the CGST Act, 2017, together with interest under Section 50 and an equal penalty under Sections 74(1) r/w 122(2)(b) ibid., read with the corresponding provisions of the SGST Act, 2017 and Section 20 of the Integrated Goods and Services Tax Act, 2017 (“IGST Act, 2017”).
5. The Adjudicating Authority adjudicated the SCN vide OIO No. 145/2024-25 dated 22.01.2025. The OIO confirmed the tax demand of Rs. 1,36,634/- under Section 74, together with interest under Section 50 and an equal penalty under Section 122(2)(b) of the CGST Act, 2017, read with the corresponding provisions of the DGST Act, 2017, IGST Act, 2017 and UTGST Act, 2017.
6. Aggrieved by the OIO dated 22.01.2025, the Respondent filed an appeal under Section 107(1) of the CGST Act, 2017. By OIA dated 03.10.2025, the Appellate Authority allowed the appeal and set aside the said OIO. Consequently, the demand and recovery of tax of Rs. 1,36,634/- under Section 74(1) of the CGST Act, 2017, together with the interest at the applicable rate under Section 50 and the penalty of Rs. 1,36,634/- imposed under Section 74 r/w Section 122(2)(b) of the CGST Act, 2017 was set aside.
7. By the present appeal, the Appellant has challenged the OIA dated 03.10.2025 on the following grounds:
(i) The Appellate Authority has set aside the demand merely based on the submissions made by the Respondent that it had not received any services from FIL during the FY 2017-18.
(ii) The Appellate Authority did not examine the ledger account relating to FIL, bank accounts or other corroborative records to determine whether taxable services had been received by the Respondent. This verification was necessary in view of the contrary information received, which indicated that the Respondent had availed services from FIL during the relevant period.
(iii) The Appellate Authority relied entirely on the submissions made by the Respondent without examining their veracity or completeness. The Appellant contends that such reliance on unverified submissions and statements was unwarranted. The submissions of the Respondent were not substantiated by objective documentary evidence.
(iv) The Respondent’s contentions that it had not received