Back


2025 Supreme(Online)(ITAT) 1255
INCOME TAX APPELLATE TRIBUNAL (JODHPUR BENCH)
DR. S. SEETHALAKSHMI, SHRI RATHOD KAMLESH JAYANTBHAI, JJ
PATEL MINERALS PVT. LTD. UDAIPUR – Appellant
Versus
ACIT CIRCLE-1 UDAIPUR – Respondent
ITA 22/JODH/2024
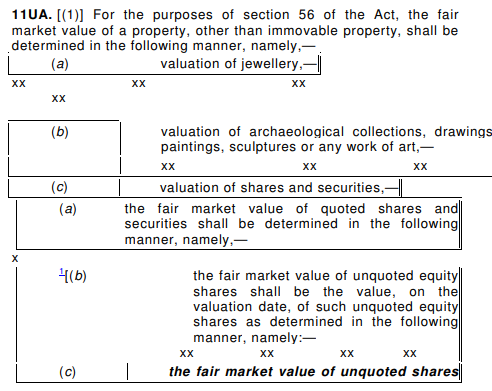
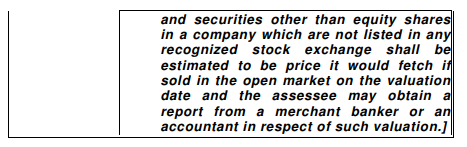
The fair market value of shares must be determined according to prescribed methods under Rule 11UA, and the assessee has discretion in choosing the valuation method, which must be supported by a valid report.
Headnote:(A) Income Tax Act, 1961 - Section 56(2)(viib) - Rule 11UA of Income Tax Rules - Appeal against addition of Rs. 51,00,000/- as share premium and share capital - Assessee claimed loss of Rs. (-) 758076/-; assessment converted to complete scrutiny - AO disallowed expenses, asserting no business activity - Valuation of shares not compliant with prescribed methods, leading to nil fair market value - CIT(A) confirmed addition, stating aggregate consideration exceeded fair market value - Court found valuation report valid, asserting discretion in choosing valuation method - Addition of Rs. 51,00,000/- was unjustified. (Paras 5.4.1, 5.4.2, 8.1, 8.3)
(B) Valuation of Shares - Fair market value must comply with Rule 11UA - Assessee's discretion in choosing valuation method upheld - DCF method valid if supported by proper report. (Paras 5.4.2, 8.1)
ORDER
PER: RATHOD KAMLESH JAYANTBHAI, AM
This appeal is filed by the assessee aggrieved from the order of the Learned Commissioner of Income Tax (Appeals), Jaipur-5 dated 04.01.2024 [ for short “CIT(A)”] for the assessment year 2015-16, which in turn arise from the order dated 08.12.2017 passed under section 143(3) of the Income Tax Act,1961 [ for short “Act” ] by the ACIT, Circle-1, Udaipur [ for short AO].
2. In this appeal, the assessee has raised following grounds: -
“1. That Learned CIT(A) has wrongly confirmed addition of Rs. 51,00,000/- of share premium and share capital treating the value of share value at Rs. Nil under section 56. The confirmation of addition is made without following provisions of law. Hence the addition of Rs. 51,00,000/- is bad in law and be deleted.
2. That appellant reserves his right to add or amend grounds of appeal.”
3. Brief facts of the case are that the assessee is a Company and had filed its original Return of Income on 03.09.2015 declaring therein total income as NIL by claiming loss of Rs (- )758076/-. The case of the assessee was selected for limited scrutiny and accordingly notice u/s 143(2) dated 13.04.2016 was issued and duly served upon the assessee, fixing the case for hearing on 29.04.2016. A detailed questionnaire u/s 142 been issued to the assessee requesting the assessee to produce certain information / clarifications.
3.1 During the pendency of the assessment proceeding the case was converted into complete scrutiny after approval of ld. Pr.CIT, Udaipur on 05.12.2017. In response to the notices so issued assessee submitted the requisite details, information, documents and clarifications sought for vide notices u/s 143(2) &142(1) as recorded in the order sheet entries made by the ld. AO.
3.2 During the course of assessment it was noticed that assessee was not doing any business activity. Even AR of the assessee in his reply dated 12.07.2017 accepted that the assessee looking for business proposition and area in which it might enter and has no active business was carried out. Thus, the claim of expenses of Rs 7,58,076/- was without any income / receipt it should have been capitalized. Assessee was asked to furnish explanation in this regard. AR of the assessee submitted that the same explanation that company was actively looking for various business opportunity and incurred routing expenditure i.e. day to day expenses and same was treated the as revenue expenditure.
3.3 Ld. AO did not find reply of the assessee as satisfactory. Thus, again a final show cause was issued on 05.12.2017 to assessee. In compliance AR of the assessee attended on 07.12.17 and vide order sheet entry dated 07.12.17 stated that he has nothing further to say and case may be decided based on reply already submitted. Ld. AO noted that when business was not even started, then all the expenses should have been capitalized. Therefore, expenses claimed for Rs 7,58,076/- claimed during the year was disallowed and added back to the income of assessee.
3.4 Further ld. AO noted that assessee (a company, not being a company in which public are substantially interested) had issued share on premium during the year. Total 1,70,000/- shares were issued at face value of Rs 10 and @ premium of Rs 20 per share at total consideration of Rs 51,00,000/- including premium received for Rs 34,00,000/- during the year. As noted earlier there was no business activity during the year as per submission filed, assessee was asked to justify the premium as per section 56(2)(viib) of the Act and rule 11UA of I.T. Rules. Ld. AR submitted share valuation report which was not as per rule 11UA but valuation of shares was done as per 'Adjusted Net Asset Method and as per 'future earning analysis. Ld. AO noted that future earning analysis method not allowed in rule 11UA but that rule allow two methods discounted free cash flow method and 'Book value of net asset method. Difference between the Adjusted Net Asset Method' taken by assessee and 'Book value o