Back


2024 Supreme(Online)(ITAT) 1088
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
NARENDRA KUMAR BILLAIYA, AM, SUNIL KUMAR SINGH, JM
DBS Bank Ltd. – Appellant
Versus
Commissioner of Income Tax (International taxation) – Respondent
I.T.A. No. 3691/Mum/2023 | I.T.A. No. 4722/Mum/2023
For the Appellants/Petitioners: Shri P.J. Pardiwala, Shri Madhur Agarwal
For the Respondents: Shri Vivek Permpurna
Deductions for bad debts must be actual write-offs as per Section 36(1)(vii), not merely provisions; expenditures enhancing operational efficiency qualify as revenue expenses.
Headnote:(A) Income Tax Act, 1961 - Sections 36(1)(vii), 36(1)(viia), 14A - Appeals concerning the denial of bad debt deduction, operational expenses, and the disallowance of interest payable to the head office of a foreign bank - The court discussed the applicability of provisions for bad debts and the relevance of revenue expenditure versus capital expenditure. The court found that the amounts written off as bad debts fulfilled criteria for allowance under relevant sections, and decisions from previous cases were distinguished based on their contexts (Paras 1-41).
(B) Deduction of bad debts - The court emphasized that mere provision for bad debts does not qualify as a deduction unless actually written off in the books, reiterating the binding nature of rules under the Income-tax Act (Paras 1, 7, 15).
(C) Disallowance under Section 14A - The court ruled that disallowance cannot be applied when shares are held as stock-in-trade, distinguishing revenue and capital expenditures (Paras 19-24).
(D) Revenue expenditure vs. Capital expenditure - It was highlighted that payments made for consultancy services linked to operational efficiency are to be treated as revenue expenses, refuting the idea of enduring benefits from such expenditure (Paras 32-36).
| Table of Content |
|---|
| 1. nature of the appeals filed (Para 1 , 2) |
| 2. claims for deduction of bad debts (Para 4 , 5) |
| 3. court's analysis of bad debt claims (Para 10 , 12) |
| 4. court's orders on appeals (Para 14 , 41) |
| 5. clarification on bad debts and provisions (Para 19 , 20) |
आदेश/ORDER
PER NARENDRA KUMAR BILLAIYA, AM:
I.T.A. No. 3691/Mum/2023 & I.T.A. No. 4722/Mum/2023, are cross-appeals by the assessee and the revenue preferred against the very same order of the ld. CIT(A)-56, Mumbai, dt. 14/08/2023, pertaining to AY 2015-16.
2. Both these appeals were heard together and are disposed of by this common order for the sake of convenience and brevity.
3. We first take up the assessee’s appeal in ITA No. 3691/Mum/2023.
4. The assessee has raised the following grounds of appeal:-
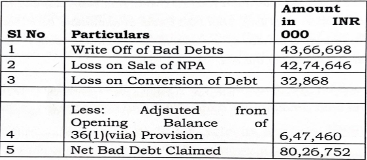
“1. The Commissioner of Income-tax (Appeals) - 56, Mumbai [herein after referred to as the "CIT(A)"] erred in upholding the action of the Assessing officer ("AO") in not allowing the deduction for bad debts written off of Rs.427,46,46,000 net of sale consideration of the non-performing asset (NPA), under section 36(i)(vii) of the Income tax Act, 1961 ("the Act").
The Appellants submit that the bad debts written off of Rs.427,46,46,000 ought to be allowed as deduction under section 36(1)(vii) of the Act read with section 36(2) of the Act.
2. The CIT(A) erred in applying the decision of the Supreme Court in the case of Southern Technologies (2010) 187 Taxman 346 (SC) without appreciating that the decision is not applicable to the facts of the case.
3. The CIT(A) erred in not following the binding decision of the Mumbai Tribunal in the case of Bank of India ( ITA No. 2833/Mum/2015) dated 08 November 2017
4. Without prejudice to ground nos. (1) to (3) above, the CIT(A) erred in upholding the action of the AO in not allowing deduction of Rs.427,46,46,000 under section 37(1) of the Act.
5. Without prejudice to ground nos. (1) to (4) above, the CIT(A) erred in not allowing deduction of Rs.427,46,46,000 under section 28 of the Act.
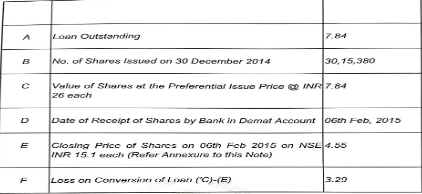
6. The CIT(A) erred in upholding the action of AO in not allowing deduction for bad debts written off of Rs.3,28,68,000 on conversion of debt to equity shares of the borrower, under section 36(I)(vii) of the Act.
The Appellants submit that the bad debts written off of Rs.3,28,68,000 ought to be allowed as deduction under section 36(1)(vii) of the Act read with section 36(2) of the Act.
7. Without prejudice to ground no. (5) above, the CIT(A) erred in upholding the action of AO in not allowing deduction for bad debts written off of Rs.3,28,68,000, under section 37(1) of the Act.
8. Without prejudice to ground nos. (5) and (6) above, the CIT(A) erred in not allowing deduction for Rs.3,28,68,000 under section 28 of the Act.
9. The CIT(A) erred in not deleting the disallowance under section 14A of the Act read with Rule 8D of the Income tax Rules, 1962, for the year under consideration.
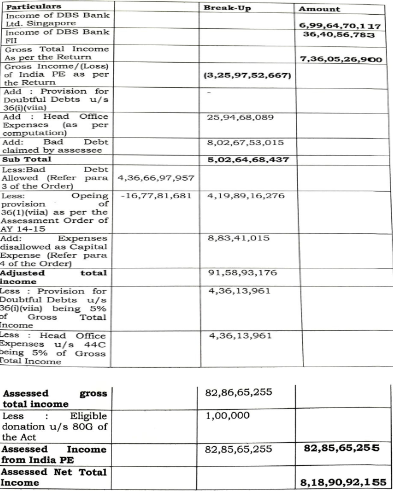
10. The CIT(A) erred in upholding action of the AO in not including the amount taxed as income of the HO while working out adjusted total income for computing the deduction under section 36(1)(viia) and section 44C of the Act.
11. The Appellant submits that considering the facts and circumstances of its case and the law prevailing on the subject, the impugned order dated 13 February 2018 passed u/s 143(3) r.w.s. 144C(3) of the Income-tax Act, 1961 is ab-initio void being barred by limitation and hence, ought to be struck down.
The appellants crave leave to add, to amend, alter, vary, omit or substitute the aforesaid grounds of appeal or add a new ground or grounds of appeal at any time before or at the time of hearing of the appeal as they may be advised.”
5. Ground Nos. 1 to 5 relate to the denial of claim of bad debts written off amounting to Rs. 4,27,46,46,000/- being net of sale consideration of the non-performing asset (NPA) u/s 36(1)(vii) of the Act.
6. Representatives of both the sides were heard at length. Case records carefully perused and the relevant documentary evidence brou