Back


2024 Supreme(Online)(ITAT) 1770
INCOME TAX APPELLATE TRIBUNAL (BANGALORE BENCH)
Shri Chandra Poojari, ACM, Shri Soundararajan K., JM
Nalapad Hotels & Convention Centre – Appellant
Versus
Income Tax Officer – Respondent
ITA No.1297/Bang/2024 | ITA No.1298/Bang/2024 | SP No.33/Bang/2024 | SP No.34/Bang/2024
For the Appellants/Petitioners: Sri H. Guruswamy, Sri Ravikiran M.
For the Respondents: Shri Kiran D.
Income arising from Joint Development Agreements must be assessed based on the date of execution, not subsequent completion. Validity of assessments is contingent on adherence to procedural requirements including issuing mandatory notices.
Headnote:(A) Income Tax Act, 1961 - Sections 2(47)(iv), 45(2) and 153C - Assessment Year: 2017-18 - Appeals against the CIT(A) orders - Alleged business income from Joint Development Agreement (JDA) - Issue of income tax chargeability for AY 2017-18 deemed invalid due to application of provisions post-JDA and limitations of time - Court finds that transfer occurred in FY 2007-08, not 2016-17 as per JDA - Need for issue of Notice u/s 143(2) reiterated as mandatory for valid assessment - Findings of CIT(A) on charging of business income negated, rules that income needs to be computed when stock-in-trade is sold - Assessment orders quashed for both appeals. (Paras 2-32)
Facts of the case:
The case involves an assessee claiming business income arising from a JDA entered into on 17.1.2008. The Tax Authority assessed additional income for 2017-18 based on an Occupancy Certificate from 21.7.2016. Disputes included time limitation and the validity of income assessment periods based on JDA terms.
Findings of Court:
The Court determined that the income should be taxed in the year of JDA execution, and provisions of 153B regarding time limitations were improperly applied. No valid notice under section 143(2) issued, making the assessments void ab initio.
Issues: Whether the income from JDA engaged in was subject to taxation in AY 2017-18, and whether the provisions for time limits under section 153B were adhered to for valid assessments.
Ratio Decidendi: The court affirms the necessity of issuing a notice under section 143(2) following the procedures outlined in the Income Tax Act. The criteria for taxability based on JDA execution date is reasserted, not relying on completion dates or new provisions affecting partnerships.
Result: Appeals allowed. Assessment quashed for failure to comply with procedural necessities governing the issuance of notices.
| Table of Content |
|---|
| 1. appeals against assessment order on taxable income determination. (Para 1 , 2 , 3) |
| 2. discussion of joint development agreement and ownership implications. (Para 4 , 5) |
| 3. legal observations regarding section applicability in income assessment. (Para 6 , 7 , 8) |
| 4. significance of notices under sections 143(2) and 153c for validity. (Para 10 , 11) |
| 5. final conclusions on reassessment orders and their bases. (Para 12 , 13) |
ORDER
PER CHANDRA POOJARI, ACCOUNTANT MEMBER:
These appeals filed by assessee are directed against different orders of CIT(A) for the assessment year 2017-18 both have common date 30.6.2024. The issue in both these appeals is common in nature. Hence, these are clubbed together, heard together and disposed of by this common order for the sake of convenience.
2. The assessees herein also filed SP Nos.33 & 34/Bang/2024 seeking stay of outstanding disputed demand of tax.
2.1 We reproduce the common grounds of appeals, except change in futures in ITA No.1298/Bang/2024 for the AY 2017-18, which are as follows:
1. The impugned order u/s 250 of the Act dated 30.6.2024 passed by the ld. CIT(A) Bangalore 15 is opposed to law, facts and circumstances of the case.
2. The Ld. CIT(A) has erred in passing the impugned Appellate order confirming the additions of alleged Business income amounting to Rs.111,53,50,377/- for the A.Y.2017-18 on the ground of alleged exchange of asset which is being exploited without appreciating the fact that the income so confirmed is not chargeable to tax for the impugned A.Y. 2017-18 as no asset as transferred except the stock in trade transferred in pursuance of the JDA dated 08-01-2008 entered with M/S. Bridge Enterprises Ltd.
3. The ld. ClT(A) has erred in rejecting the ground adduced relating to limitation of time reckonable from the date of original search in the case of M/s. Brigade Enterprises conducted on 02-11-2017 and alleged seizure of documents on 28-12-2017 from the said premises without appreciating the admitted fact that the AO was he same to the searched case of the Brigade enterprise and the appellant as a result of which he limitation applicable to the original searched case was also applicable to the case of the appellant and the limitation was expired on 31-12-2019.
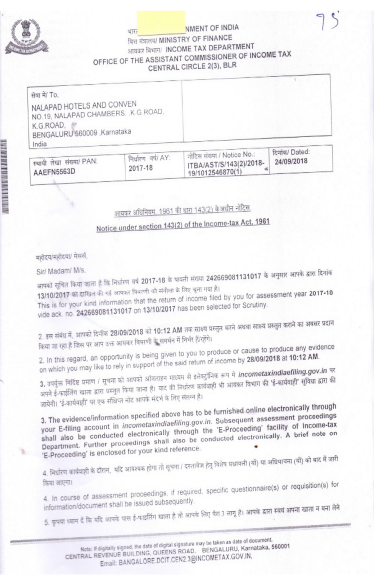
4. Without prejudice to the limitation of time as urged in ground No. 4, the ld. ClT(A) has erred in holding that the Notice U/s 143(2) of the Act was not required to be issued since the return of income was on 26.2.2021 in response to the Notice u/s 153C of the Act dated 24-03-2020 which was said to be invalid without appreciating the fact that the AO has not issued any Defective Notice u/s 139(9) and therefore the return filed on 26-02-2021 was valid.
5. The Ld. CIT(A) has erred in upholding the Notice Issued u/s 153C on the basis of a satisfaction note alleged to have been drawn on 24-03- 2020 on the basis of assessment proceedings in the case of searched assessee M/S. Brigade Enterprises Ltd without appreciating the fact that he limitation of time for completion of the assessment was already expired on 31-12-2019 as a result of which the Notice u/s 153C was invalid.
6. Without prejudice as to the limitation of time and validity of the assessment order, it is urged that he Ld. CIT(A) has erred in holding a sum of Rs111,53,50,377/- as Business income for the A. Y 017-18 on the decision dated 22-01-1997 of the Honourable Supreme Court in the case of M/S. Oriental Trading co. Ltd. vs. CIT(A)- 224 ITR 371 without appreciating the fact that the said decision was distinguishable on facts and circumstances of the case of the appellant.
7. The Ld. CIT(A) has erred in holding a sum of Rs. 111,53,50,377/- as Business income merely on the basis of occupation certificate obtained in the Financial year 2016-17 relevant to the A.Y 201718 without appreciating the fact that the said certificate was not a relevant document for chargeability of Tax relating to transfer of stock in trade in pursuance of the JDA dated 08-01-