Back


2024 Supreme(Online)(ITAT) 775
INCOME TAX APPELLATE TRIBUNAL (AHMEDABAD BENCH)
SMT.ANNAPURNA GUPTA, ACJ, SHRI SIDDHARTHA NAUTIYAL, J
REKHA SANJEEV BHATT AHMEDABAD – Appellant
Versus
THE INCOME TAX OFFICER WARD-2 INTL.TAXN. AHMEDABAD – Respondent
ITA No.1025/Ahd/2023
For the Appellants/Petitioners: Shri Jaimin Shah, AR
For the Respondents: Shri Rignesh Das, Sr.DR
The failure of revenue to substantiate claims against the assessee’s documentary evidence renders unexplained income additions unsustainable.
Headnote:(A) Income Tax Act, 1961 - Sections 69, 69A, 143(3) read with 144C(13) - Income Tax Officer made additions pertaining to unexplained cash deposits and investments by the assessee. The arguments were based on the source of funds deposited in bank accounts as well as the justification of the transactions. Findings of Court indicated that necessary documentary evidence was provided by the assessee, demonstrating the source of funds and the non-resident status of the assessee was cited. The Court emphasized that mere doubts by the Revenue regarding the genuineness of the transactions, without substantial evidence, would not validate the additions made. (Paras 4, 13, 18, 26, 36)
Facts of the case:
The assessee challenged multiple assessments concerning unexplained cash deposits and investments in her name, arguing against improper applications of tax laws and providing corroborating evidence for the legitimacy of their income sources involved in transactions.
Findings of Court:
The Revenue authorities lacked a substantial basis for rejecting the explanations provided by the assessee for cash deposits and investments as evidenced by necessary documentation.
Issues: The court principally addressed the validity of additions made based on alleged unexplained sources of income and the importance of documentary corroboration in tax matters.
Ratio Decidendi: The court ruled that sufficient evidence must support claims of income legitimacy and that the rejection of such claims without substantial foundation is unwarranted.
Result: The appeal of the assessee is allowed.
| Table of Content |
|---|
| 1. various grounds against additions made are put forth. (Para 1 , 7) |
| 2. assessment issues were based on insufficient justification by revenue. (Para 3 , 8 , 14 , 16) |
| 3. contention on cash deposits explanation and evidence provided. (Para 4 , 6 , 9 , 10 , 11 , 12) |
| 4. findings demonstrate documentary evidence supports assessee's claims. (Para 13 , 15 , 17 , 18 , 20 , 24 , 26) |
आदेश/ORDER
PER ANNAPURNA GUPTA, ACCOUNTANT MEMBER
This appeal has been filed by the assessee against the order of the Assessing Officer, viz. Income Tax Officer (International Taxation), Ahmedabad passed under section 143(3) read with section 144C(13) of the Income Tax Act, 1961 ("the Act" for short) pertaining to the Assessment Year 2021-22.
2. At the outset itself, it was stated that, the grievance of the assessee is against various additions made to her income on account of cash deposited in her bank account, as also investments made in immovable property, source of which allegedly remained to be satisfactorily explained by the assessee.
3. Briefly summarizing the additions in challenge before us, it was pointed that the following additions were made in the hands of the assessee for the aforementioned reason:
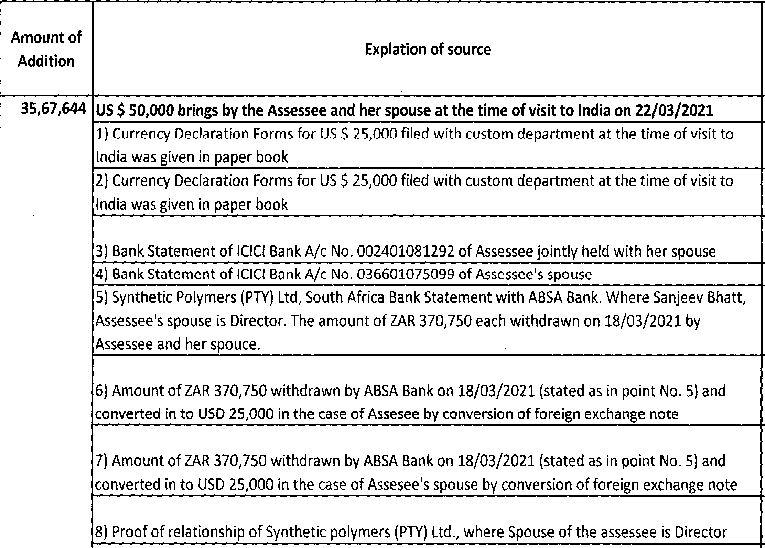
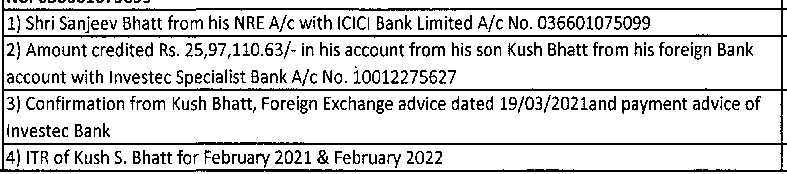
i) Cash deposit in bank account remaining unexplained, under section 69A of the Act, of Rs.35,67,644/-;
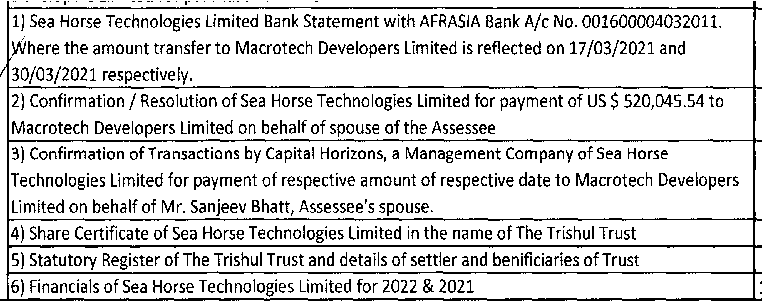
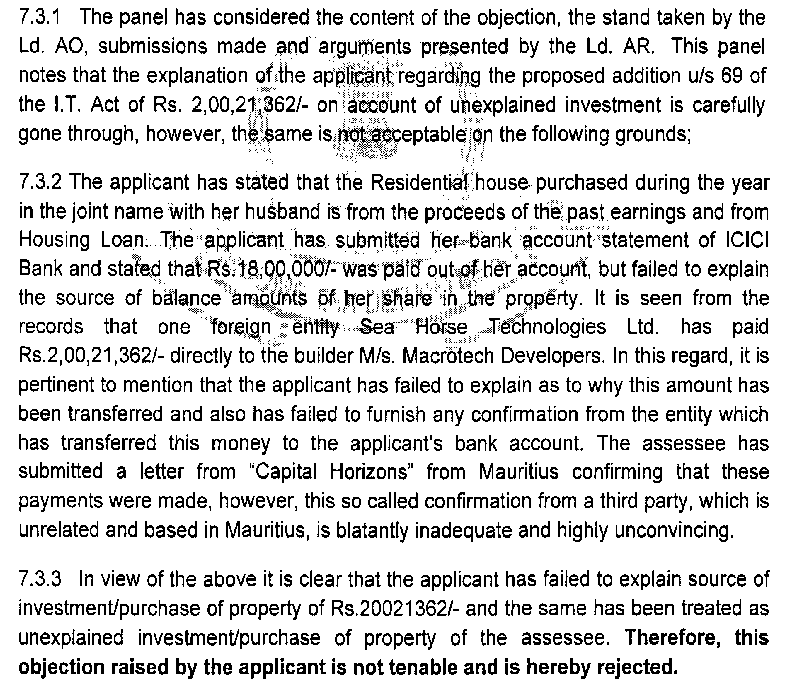
ii) Unexplained investment in immovable property, under section 69 of the Act ,of Rs.2,00,21,362/-;
iii) Unexplained investment by way of stamp duty charges and registration fees of Rs.26,19,000/- for the aforementioned immovable property.
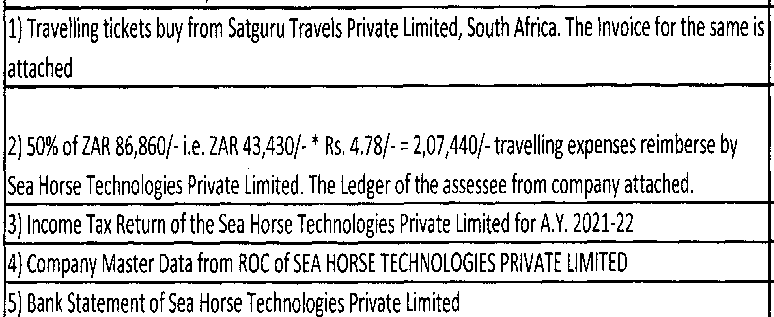
iv) Unexplained cash deposit in bank account of the assessee of Rs.2,07,440/- ,under section 69A of the Act.
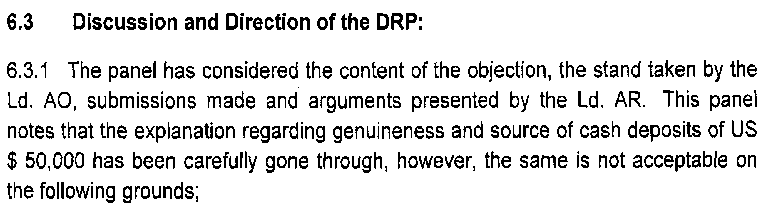
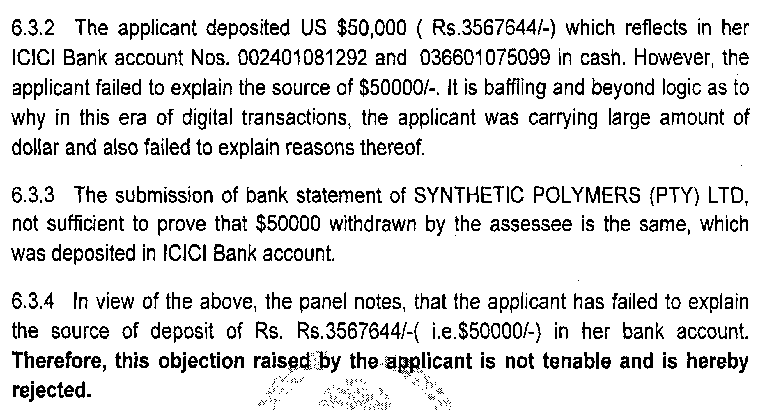
4. It was contended that the AO had proposed the above additions in a draft order passed in terms of provisions of section 144C(3) of the Act, to which the assessee had filed objections to the DRP, and the DRP accordingly, after considering the contentions of the assessee rejected all the objections of the assessee in its order passed under section 144C(5) of the Act. The AO accordingly thereafter passed final order in accordance with the directions of the DRP making all the aforementioned additions to the income of the assessee.
Aggrieved by the same the assessee has come up in appeal before us raising the following grounds:
01. That the Income Tax Officer, Ward -1, International Taxation Ahrnedabad and Ld DRP has erred both in law and on facts while making the various additions of Rs.2,64,45,446/- against the returned Income of Rs. 385/-, and therefore the additions made while passing the order u/s 143(3) r.w.s. 144C(13) of the Income Tax Act, 1961 is requires to be deleted.
02. That the Ld. Assessing officer and DRP failed to appreciate the facts that the appellant and her husband are two different person as per Income Tax Act, 19(51, However various additions made which are the transactions of not the appellant is bad in law and therefore the order is totally erroneous and required to be quashed.
03. That the Ld. A.O. and DRP fails to appreciate the facts and DTAA between India - Mauritius and India -South Africa and therefore various addition made wil lout appreciating the submissions of the appellant during the DRP proceedings are bad in law and requires to be deleted.
04. That the Ld. A.O. and DRP has erred both in law and on facts while making the addition of Rs.35,67,644/- u/s 69A r.w.s. 115BBE and therefore it requires to be deleted.
05. That the Ld. assessing officer and DRP has erred in law and on facts while making the additions of Rs.2,00,21,362/- u/s 69 of the IT. Act of on account of unexplained investment is against the fact and documentary evidence available on record and therefore it required to be deleted.
5. Ground No.1 was stated to be general in nature, and is therefore not being adjudicated by us. Ground no.9 challenging the initiation of penalty proceedings, being premature, is dismissed.
Ground No.2 and 3 was stated to be argumentative concerning the grounds challenging the addit