Back


2024 Supreme(Online)(ITAT) 1442
INCOME TAX APPELLATE TRIBUNAL (BANGALORE BENCH)
Shri Waseem Ahmed, ACM, Shri Keshav Dubey, JM
Sri.Veeranna Murthy – Appellant
Versus
The Income Tax Officer – Respondent
ITA No.1072/Bang/2024
For the Appellants/Petitioners: Ms. Lakshmi S.
For the Respondents: Sri.Chinmay Anand Jain, JCIT-DR
Unexplained cash deposits during demonetization must be substantiated with relevant evidence to avoid classification as unaccounted income.
Headnote:(A) Income Tax Act, 1961 - Sections 68, 115BBE, 143(2), 271AAC, 282A, 292B, and 292BB - Unexplained cash credit - The appellant challenged additions made by AO, claiming significant cash deposits during demonetization as part of turnover - CIT(A) upheld assessments citing absence of evidence and violation of law by appellant - The Court emphasized on necessary verification as per CBDT circulars, specifically addressing the burden of proof on the taxpayer for cash deposits during demonetization. (Paras 7, 9, 10, 16)
| Table of Content |
|---|
| 1. appeal against assessment order by taxpayer. (Para 1 , 2 , 3) |
| 2. assessment challenges on legal grounds and principles of natural justice. (Para 4 , 5 , 6) |
| 3. court's strict adherence to verification of cash deposits as per laws. (Para 7 , 9 , 10 , 16) |
| 4. final judgment allows for further statistical scrutiny of cash deposits. (Para 13 , 15) |
ORDER
Per Keshav Dubey, JM :
This appeal at the instance of the assessee is directed against the order of CIT(A) / National Faceless Appeal Centre, Delhi dated 30.03.2024 vide DIN & order No. ITBA/NFAC/S/250/2003-24/1063672689(1) passed u/s.250 of the Income-tax Act, 1961 (“the Act”) for Assessment Year (AY) 2017-18.
2. The assessee has raised the following grounds:-
“1. The Order of the learned Commissioner passed under section 250 of the Act is opposed to law, equity, weight of evidence, probabilities and the facts and circumstances in the Appellant's case.
2. The Appellant denies to be assessed to tax on total income as determined by the learned AO of Rs. 60,31,780/- as against the total income reported by the Appellant of Rs. 10,06,240/- on the facts and circumstances of the case.
3. The learned Commissioner of Income-tax (Appeals) erred in passing the order without giving adequate opportunities hence violated the principles of natural justice.
4. The Learned Commissioner of Income-tax (Appeals) erred in upholding the addition of Rs. 50,25,540/- as unexplained cash credit despite the fact that the same was attributed as part of turnover by reducing a net profit rate of 1.37%; hence the source stands explained to be business income in the facts and circumstances of the case.
5. The Learned Commissioner of Income-tax (Appeals) erred in law that the Appellant was not authorised to accept demonetised currency between 8.00 - 11.00 pm on 8 November 2016 despite the fact that it ceased to be legal tender from 9 November 2016 as per RBI notification in the facts and circumstances of the case.
6. The Learned Commissioner of Income-tax (Appeals) erred in upholding the addition of Rs. 50,25,540/- as unexplained cash credit just because cash was accepted during demonetisation which is against the intention of demonetisation which was not to penalise genuine business transactions in the facts and circumstances of the case.
7. Without prejudice, the Learned Commissioner of Income-tax (Appeals) erred in making an addition of Rs. 50,25,540/- without reducing the equivalent turnover as the cash deposit was considered as a part of the turnover to arrive at the net profit declared in the return of income in the facts and circumstances of the case.
8. The Learned AO erred in taxing the determined total income of the Appellant as per the provisions of section 115BBE on the facts and circumstances of the case.
9. The Appellant craves leave to add, alter, delete or substitute any of the grounds urged above.
10. In the view of the above and other grounds that may be urged at the time of the hearing of the appeal, the Appellant prays that the appeal may be allowed in the interest of justice and equity.”
3. Further, the assessee has also raised the following additional grounds of appeal:-
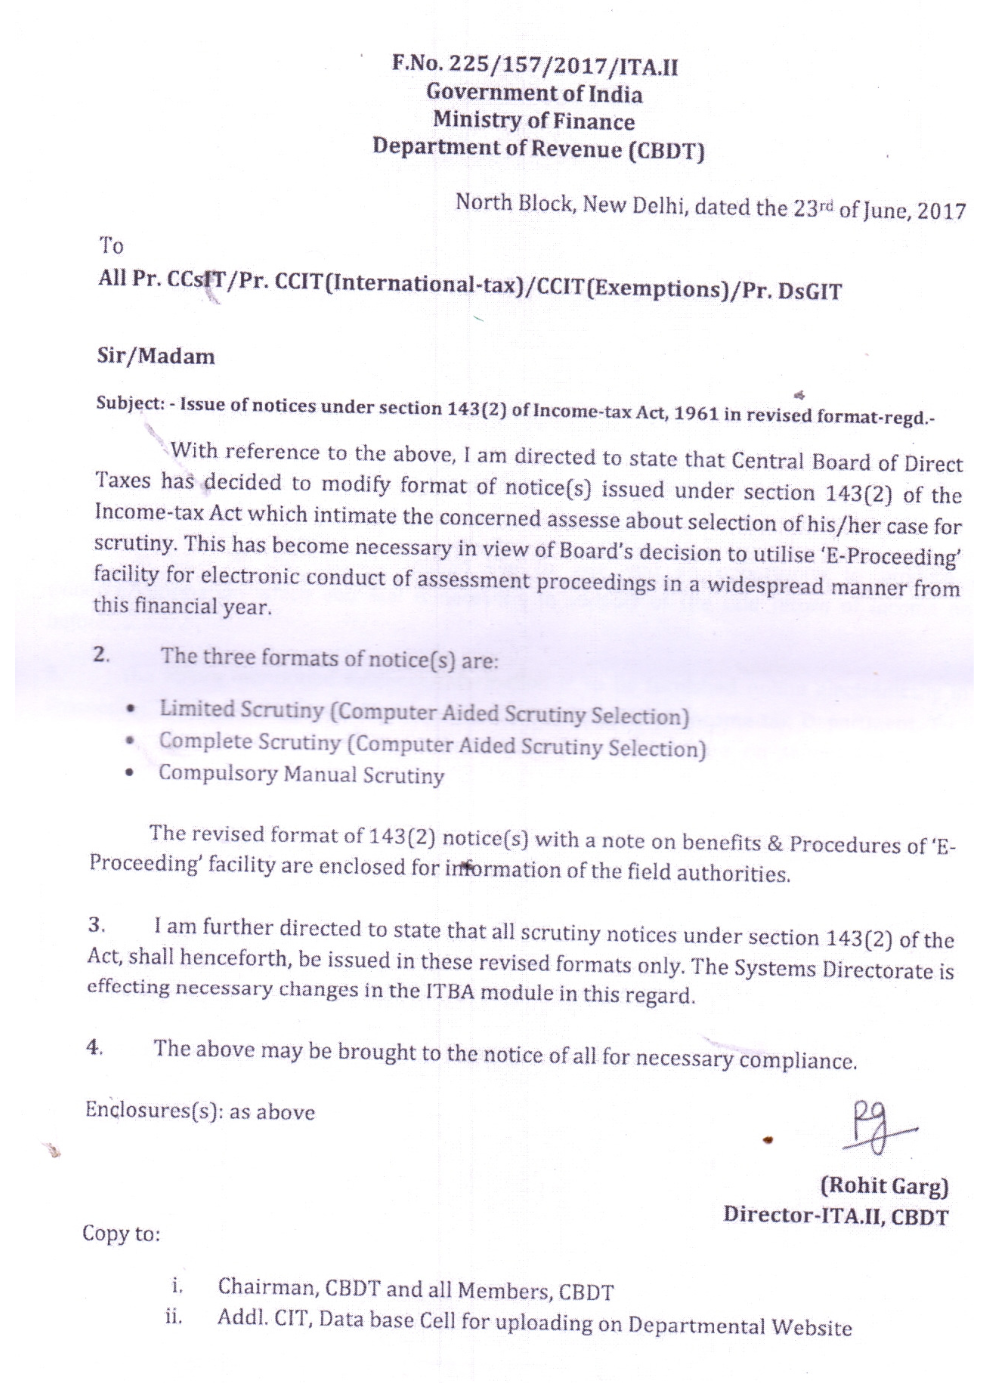
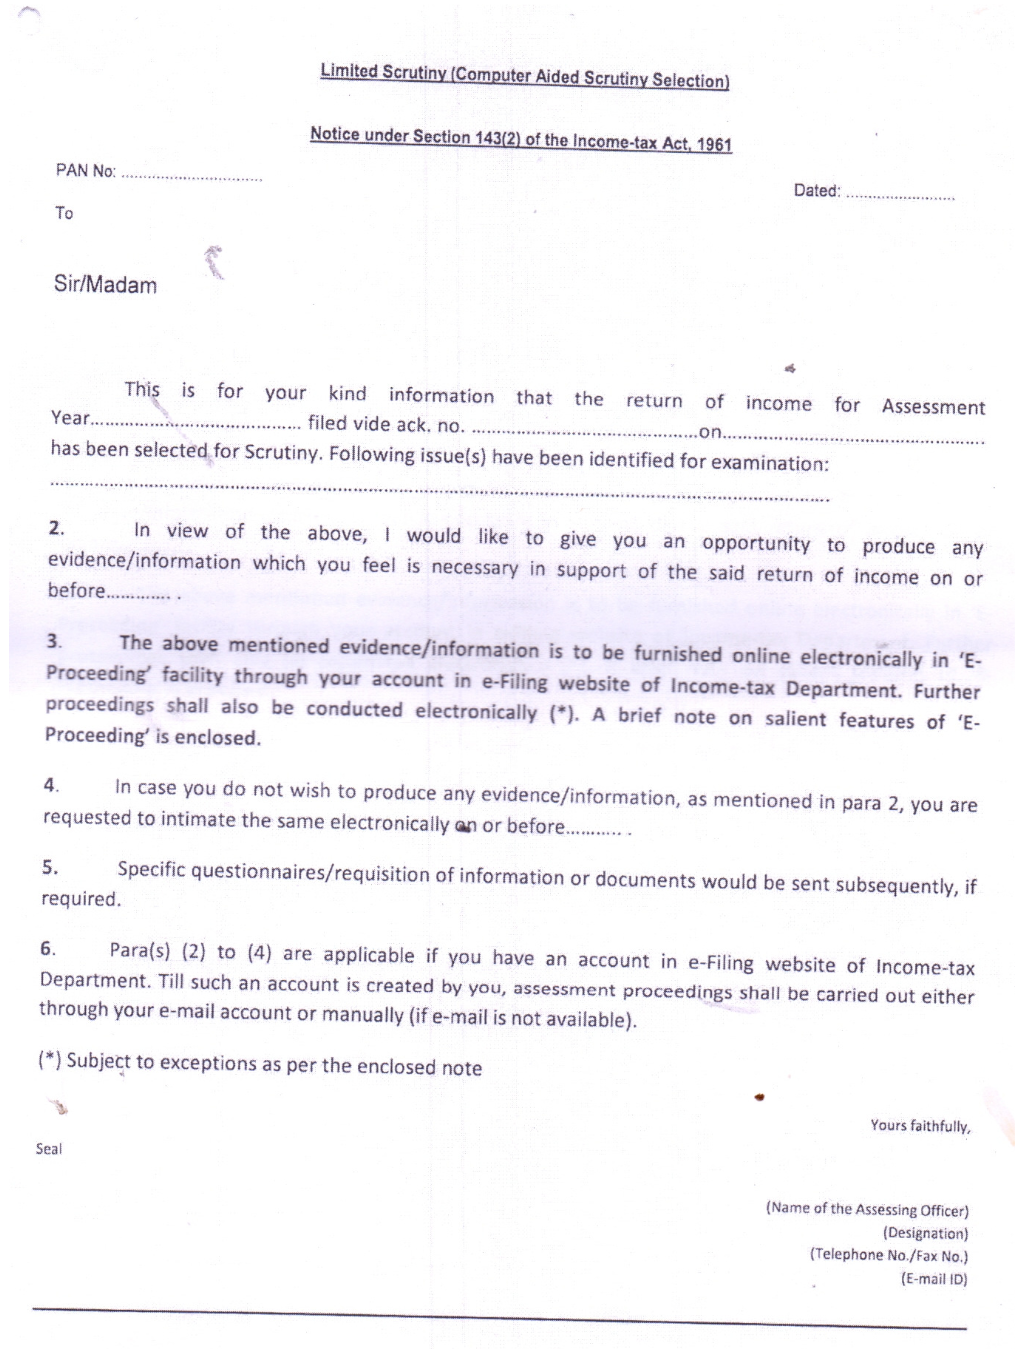
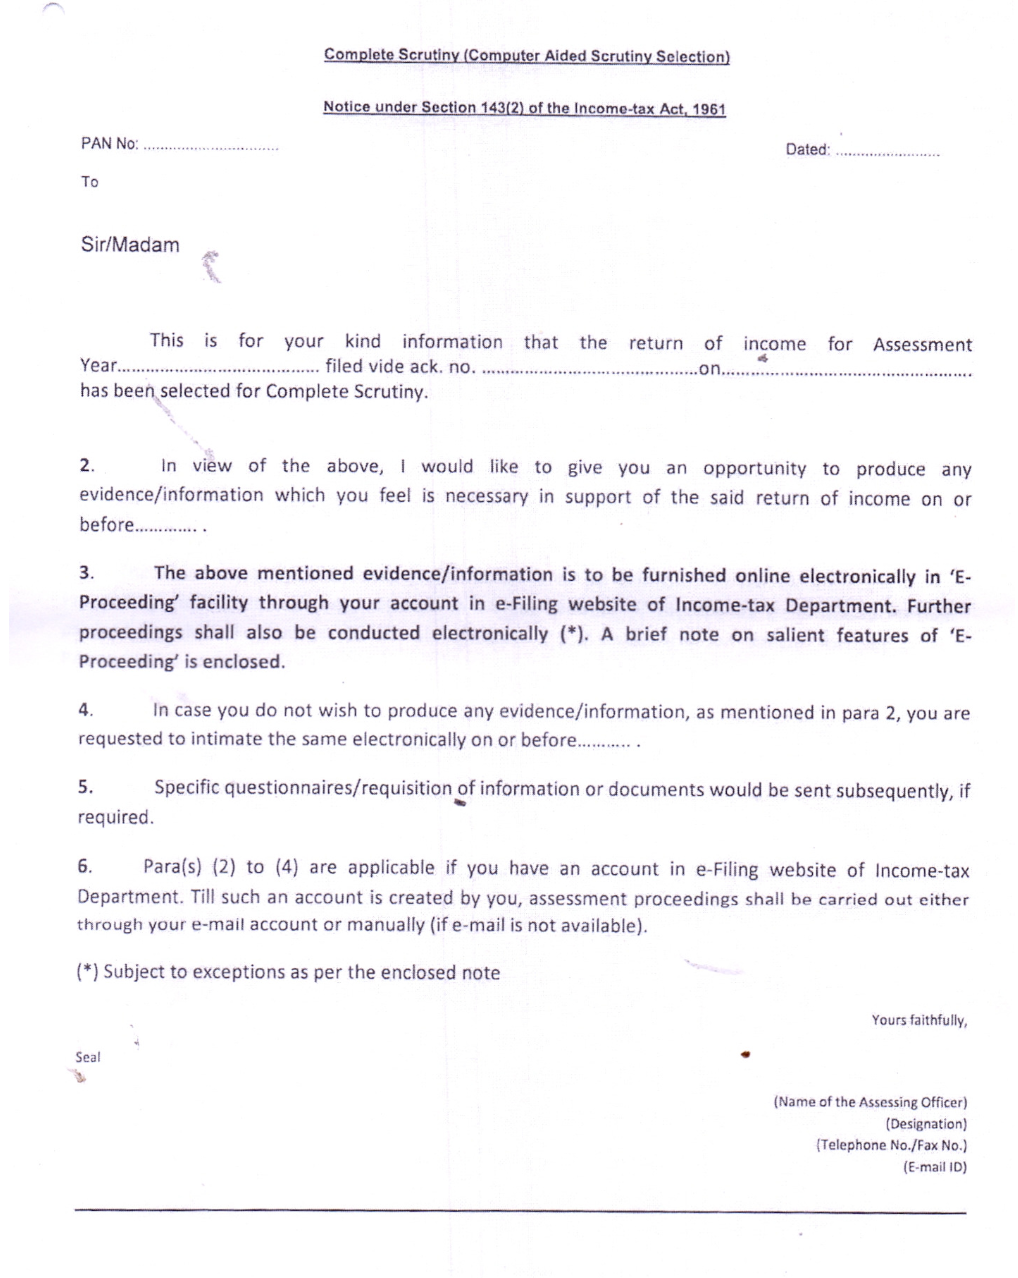
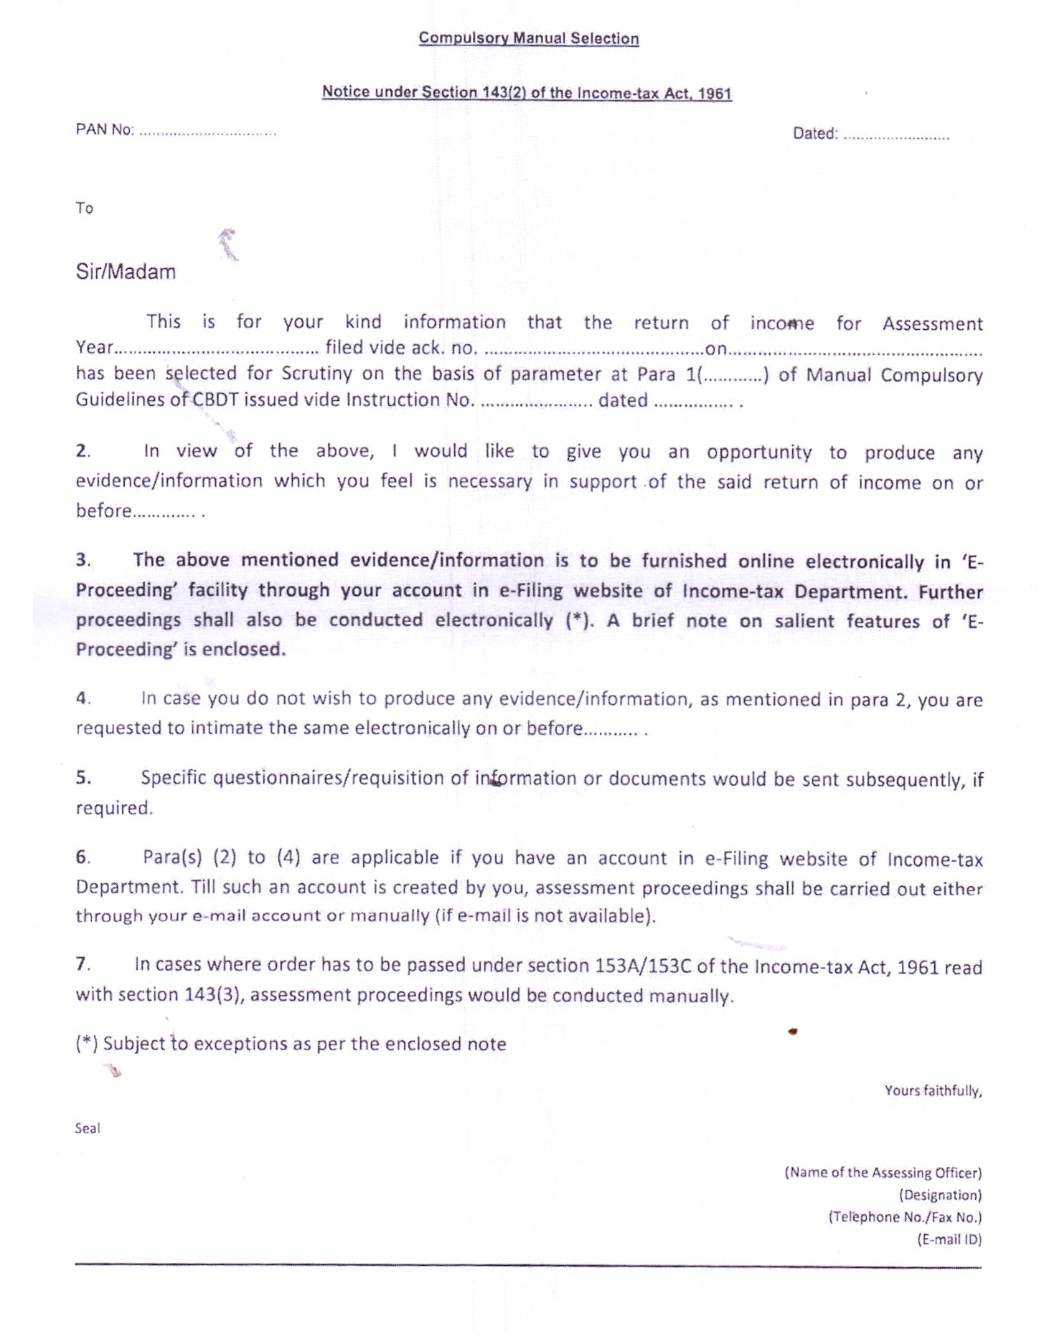
“1. The notice issued u/s.143(2) of the Act dated 24.09.2018 is bad at law as it is not accordance in the format prescribed by the Central Board of Direct Taxes as per Instructions (F No.225/157/2017/ ITA .II) dated 23.06.2017; therefore all consequential assessment proceedings including the assessment order are rendered bad at law in the facts and circumstances of the case.
2. Without prejudice to the right to seek waiver with the Hon'ble Chief Commissioner of Income Tax/Director General of Income Tax, the Appellant denies itself liable to be charged to interest under section 234B and 234C of the Act which under the facts and circumstances of the case deserves to be cancelled. The calculation of interest under section 234B and 234C of the Act is not in accordance with law as the rate, amount and method for calculating interest