Back


2024 Supreme(Online)(ITAT) 291
INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
Dr. B. R. R. Kumar, ACJ, Sh. Yogesh Kumar, US
Vaibhav Jain – Appellant
Versus
DCIT, Central Circle-7 – Respondent
ITA No. 9854/Del/2019 | ITA No. 9855/Del/2019
For the Appellants/Petitioners: Sh. Mayank Patawari, CA, Sh. Anmol Jagga, Adv.
For the Respondents: Ms. Sapna Bhatia, CIT DR
The decision emphasizes the necessity of incriminating evidence for tax assessments and the importance of cross-examination rights for due process.
Headnote:(A) Income Tax Act, 1961 - Sections 69, 153A, 115BBE, 271(1)(c), 234A, 234B - Appeal against addition of unexplained investments made by a director in Jindal Bullion Ltd. based on incriminating documents seized during search - Order upheld due to lack of incriminating evidence presented by the appellant and rejection of the opportunity for cross-examination. (Paras 11, 22)
(B) Assessment Procedure - Action under section 153A must have basis in incriminating material - Cross-examination is integral to fair adjudication; refusal can undermine the fairness of the proceedings. (Paras 15, 23)
Facts of the case:
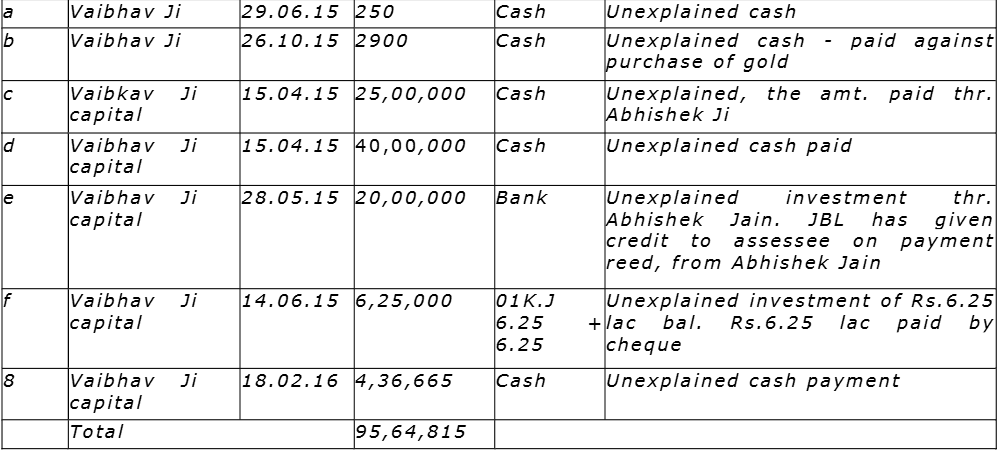
The appellant challenged the addition of Rs.95,64,815 and other amounts on the grounds of lack of valid jurisdiction and failure to provide adequate opportunity for defense during assessment proceedings, leading to claims of unfairness.
Findings of Court:
The tribunal concluded that the assessment made by the AO lacked sufficient grounds, and therefore, the appeals were allowed based on the failure to justify additional amounts against their existence in the books of accounts.
Issues: The controversy revolved around the validity of assessment charges without adequate incriminating evidence and the balance of fairness in assessment procedures.
Ratio Decidendi: The tribunal underscored the necessity of substantiating claims with proper evidence and the importance of allowing the appellant to cross-examine witnesses to uphold principles of natural justice.
Result: Appeals allowed.
| Table of Content |
|---|
| 1. grounds for appeal and assessments validated. (Para 2 , 12) |
| 2. analysis of incriminating evidence for assessment. (Para 5 , 6) |
| 3. need for cross-examination in assessment. (Para 14 , 15) |
| 4. conclusion restoring fairness and justice in taxation. (Para 22) |
ORDER
Per Dr. B. R. R. Kumar, Accountant Member:
The present appeals have been filed by the assessee against the orders of ld. CIT(A)-24, New Delhi dated 23.10.2019.
2. In ITA No. 9854/Del/2019, following grounds have been raised by the assessee:
“1. On the facts and circumstances of the case, the order passed by ld. CIT(A) is bad both in eyes of law and on facts.
2. That the ld. CIT(A) has erred in law as well as on facts in confirming the action of ld. AO as he was not justified in arbitrarily assuming jurisdiction u/s 153A of the Income Tax Act, 1961 and has further erred in confirming the impugned Assessment Order.
3. That the ld. CIT(A) has erred in law as well as on facts by upholding the initiation of proceedings u/s 153A, since no incriminating documents pertaining to the assessee was found during the course of search.
4. That the ld. CIT(A) has erred in law as well as on facts in confirming the action of the ld. AO for assuming jurisdiction and framing the impugned assessment order u/s 153A/143(3) of the Income Tax Act, 1961 which is bad in law and the same is not sustainable on various legal and factual grounds.
5. That the ld. CIT(A) has erred in law as well as on facts in upholding the addition of Rs.95,64,815/- on account of investment allegedly made in gold and investment in JBL (i.e. m/s Jindal Bullion Ltd.) u/s 69 r.w.s. 115BBE of the Income Tax Act, 1961 .
6. That the ld. CIT(A) has erred in law as well as on facts in upholding the addition of Rs.95,64,815/- made by the ld. AO without having any incriminating documents.
7. That the ld. CIT(A) has erred in law as well as on facts by upholding the ld. AO order without observing the principles of natural justice and without providing the opportunity to cross examine the deponents.
8. That ld. CIT(A) as well as ld. AO ought to have allowed the benefit of telescoping and ought not to have taxed one and the same amount twice.
9. That ld. CIT(A) has erred in law as well as on facts in confirming the impugned addition and passing the impugned assessment order without providing the adequate opportunity of being heard which is bad in law and not sustainable on various legal and factual grounds.
10. That the ld. CIT(A) and the ld. AO has erred in law as well as on facts by initiating the penalty proceeding u/s 271(1)(c) of the Income Tax Act, 1961 .
11. That the ld. CIT(A) has erred in law as well as on facts by confirming the charging of interest u/s 234A and 234B of the Income Tax Act, 1961 .”
3. In ITA No. 9855/Del/2019, following grounds have been raised by the assessee:
“1. On the facts and circumstances of the case, the order passed by ld. CIT(A) is bad both in eyes of law and on facts.
2. That the ld. CIT(A) has erred in law as well as on facts in confirming the action of ld. AO in passing the impugned assessment order without assuming jurisdiction as per rule.
3. That the ld. CIT(A) has erred in law as well as on facts in upholding the addition of Rs.9,03,040/- on account of unexplained investment u/s 69 r.w.s. 115BBE of the Income Tax Act, 1961 .
4. That the ld. CIT(A) has erred in law as well as on facts in upholding the addition of Rs.1,00,000/- on account of undisclosed salary income.
5. That the ld. CIT(A) has erred in law as well as on facts by upholding the ld. AO order without observing the principles of natural justice and without providing the opportunity to cross examine the deponents.
6. That ld. CIT(A) as well as ld. AO ought to have allowed the benefit of telescoping and ought not to have taxed one and the same amount twice.
7. That ld. CIT(A) has erred in law as well as on facts in confirming the impugned addition and passing the impugned assessment order without providing the adequate opportu