Back


SHRI NARENDRA PRASAD SINHA, ACCOUNTANT MEMBER आयकर अपील (एस.एस.)
सं./I.T(SS).A. Nos. 48 & 49/Ahd/2024 ((cid:467)नधा(cid:91)रण वष (cid:91) / Assessment Years : 2012-13 & 2016-17)
Date of Hearing 02/04/2025 Date of Pronouncement 05/05/2025
For the Appellants/Petitioners: Shri Abhay Thakur
For the Respondents: Shri Tushar Hemani
Income of a foreign company with a permanent establishment in India is subject to taxation based on the income accruing from its business connection, regardless of previously established Arm's Length Prices.
Headnote:(A) Income Tax Act, 1961 - Section 9(1)(i) - Determination of deemed income - The appeal concerns the assessment of a foreign company's income deemed to arise in India due to its business connection through a permanent establishment via local employees. The CIT(A) deleted the additions on the ground that no adjustments were made by the TPO regarding Arm’s Length Price (ALP). The court emphasized that once ALP is determined, further profit attribution cannot be made for the PE. However, the Revenue contended that the provision of Section 9(1)(i) warranted taxation of income from business connection in India. (Paras 6, 9, 18-20)
Findings of Court:
The court ruled that profit attribution mechanisms must adhere to the statutory methods and confirmed that the AO’s original profit attribution should be reassessed where appropriate. Significant errors in the application of statutory rules were identified.
Issues: The key issues included whether the company had a business connection in India, the existence of a PE, and the proper methodology for attributing profits.
Ratio Decidendi: The court established that the mere presence of employees in India constituted a PE and that taxable income must be tied to the business operations conducted through that PE, notwithstanding the application of transfer pricing regulations.
Result: Appeals allowed for statistical purposes.
| Table of Content |
|---|
| 1. order for convenience in appealing cases. (Para 1 , 2) |
| 2. factual background of assessing business connection. (Para 3 , 4) |
| 3. cit(a)'s order regarding international transactions. (Para 6) |
| 4. revenue's contention on business connection. (Para 7) |
| 5. assessee's arguments against profit attribution. (Para 8) |
| 6. court's examination of business connection and pe. (Para 9 , 10 , 11) |
| 7. conditions for establishing a permanent establishment. (Para 12 , 13) |
| 8. discussion on profit attribution in relation to pe. (Para 14 , 15) |
| 9. legal precedent regarding taxability of pe profits. (Para 16 , 17 , 18 , 19 , 20) |
| 10. court's directive for reassessing profit attribution. (Para 21 , 22 , 23 , 24) |
| 11. conclusion on appeals and further proceedings. (Para 26) |
ORDER
PER SHRI NARENDRA PRASAD SINHA, AM:
These two appeals are filed by the Revenue against the combined order of the Commissioner of Income-Tax (Appeals)- 11, Ahmedabad, (in short ‘the CIT(A)’), dated 28.03.2024 for the A.Ys. 2012-13 & 2016-17, respectively.
2. Since, facts of the two cases are identical, both the matters were heard together and are being disposed of vide this common order for the sake of convenience.
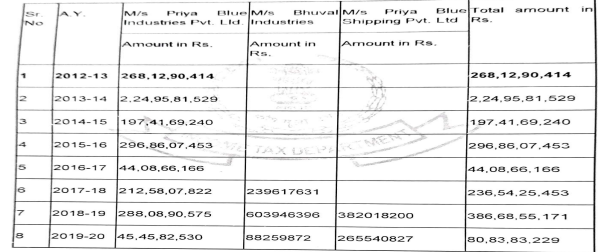
3. The brief facts of the case are that the assessee is a foreign company registered in Hong Kong since 2010 and wholly owned subsidiary of Priya Blue Industries Pvt. Ltd. (PBIPL). A search under Section 132 of the Income Tax Act, 1961 (in short ‘the Act’) was conducted on Priya Blue group on 19.11.2019 and it transpired that the assessee company was carrying out its business operation in India through the employees of PBIPL. In the course of search at Mumbai Office of PBIPL, it was found that the said office was also functioning as the key office of Best Oasis Ltd. (Hong Kong) and a number of important functions of assessee company were being carried out from Mumbai office premises. The activities of the assessee company being carried out in India from the office of PBIPL constituted a business connection in India and the income of the assessee was deemed to accrue or arise out of such business connection and was liable to be taxed in India. It further transpired that the assessee company had entered into various international transactions with its associated/related enterprise (AEs) which included sale, securing guarantee and getting managerial/office services from its AEs. The international transaction entered into by the assessee company with its AEs in India in respect of sale of vessels in different years was found to be as under:
4. In the course of assessment proceedings, the AO had referred the matter to the Transfer Pricing Officer (TPO) to compute the Arm’s Length Price (ALP) in relation to international transactions carried out by the assessee with its AEs. The TPO after making detailed enquiries had passed order u/s.92CA(3) of the Act dated 28.01.2022, wherein it was found that the transaction of the assessee with its AEs in respect of receipt of services and corporate guarantee was not at ALP. However, as the revision of ALP had impact of reducing the income of the assessee, no adjustment was proposed by the TPO in accordance with the provision of Section 92(3) of the Act. The AO held that the assessee had a permanent establishment (PE) in India and that it was carrying on business in India through its PE. Accordingly, the AO applied “Profit Attribution Theory” and quantified deemed taxable income from source in India. The AO had passed the final assessment order u/s.153A/143(3) of the Act on 31.03.2022 and incomes of Rs.4,98,11,358/- and Rs.1,57,90,918/- were quantified for the A.Y. 2012-13 & 2016- 17 respectively. The AO had computed the income of the assessee by net profit attribution in accordance with the Proviso to Section 9(1)(i) of the Act read with Rule 10 of IT Rules.
5. Aggrieved with the order of the AO, the assessee had filed an appeal before the First Appellate Authority, which was decided by the Ld. CIT(A) vide the impugned order. The Ld. CIT(