Back


2021 Supreme(Online)(ITAT) 112
INCOME TAX APPELLATE TRIBUNAL (LUCKNOW BENCH)
A. D. Jain, VP, T. S. Kapoor, AM
assessee – Appellant
Versus
CIT(A)-IV, Kanpur – Respondent
IT(SS)A. No.78/Lkw/2019
For the Appellants/Petitioners: learned counsel for the assessee
For the Respondents: learned CIT, D. R.
The reliance on uncorroborated witness statements in tax assessments without providing cross-examination opportunities violates natural justice, necessitating annulment of the assessment.
Headnote:(A) Income Tax Act, 1961 - Sections 68 and 153A - The court emphasized that in assessments under section 153A, there must be incriminating material for additions. Reliance solely on statements from lenders alleged to be bogus, without cross-examination, violates natural justice. The assessment lacks valid evidence when no incriminating material is found, warranting deletion of addition. (Paras 4.1, 5.1, 6, 18)
(B) Natural Justice - The principles of natural justice necessitate the opportunity for cross-examination of witnesses whose statements are used against an assessee; failure to provide this renders the assessment void. (Paras 5.1, 5.2, 12-18)
Facts of the case:
The assessee’s appeal arises from an assessment under section 153A following a search, asserting no incriminating material was found. Additions were made based on interest from unsecured loans deemed bogus. Supporting documentation was provided, yet cross-examination of statements used was denied, leading to disputes about legitimacy of deductions. (Paras 1, 4.1)
Findings of Court:
The court found the assessment and subsequent charges invalid as no incriminating evidence justified the additions, reiterating the importance of documentary evidence over untested statements. (Paras 4.2, 5.4)
Issues: The primary issues were the legitimacy of the added income based on unsecured loans and whether denial of cross-examination led to violations of due process in the assessment. (Paras 11, 14)
Ratio Decidendi: The court concluded that reliance on uncorroborated witness statements, coupled with denial of cross-examination rights, constituted a serious breach of the principles of natural justice, nullifying the assessment. (Paras 18, 19)
Result: The appeal of the assessee is allowed, resulting in the deletion of the additions made to income. (Para 6)
| Table of Content |
|---|
| 1. cit(a)'s order being appealed (Para 1) |
| 2. arguments against the cit(a) ruling (Para 2 , 3) |
| 3. court's observation on evidence and due process (Para 4) |
| 4. appeal allowed based on merits (Para 6) |
ORDER
PER T. S. KAPOOR, A.M.
This is an appeal filed by the assessee against the order of learned CIT(A)-IV, Kanpur dated 29/11/2018 pertaining to assessment years 2014- 2015. In this appeal, the assessee has taken the following grounds:
“1. BECAUSE the Learned CIT(A) was wrong in law & on facts in confirming the assessment order passed by AO u/s 153A of the Act as the same was not in consonance with the settled position of law vis-a-vis search cases.
2. BECAUSE the learned CIT(A) has erred in law and on facts in upholding the assessment ignoring the settled position of law that provisions of section 153A, in case where proceedings are not pending, could not be applied in absence of any incriminating material.
3. BECAUSE the reliance on 'reports of investigation wing' etc. did not constitute 'material' relevant for the purpose of assessment in this case, as the 'appellant' had never been confronted with the same in right perspective and as such the addition made on the basis of such an ex-parte information and reports etc. is wholly vitiated.
4. BECAUSE the computation of income was not even relevant for the purpose of assessment and the same is vitiated, as during the course of search (even in pursuance of joint warrant of Authorisation), no incriminating material was found which could impinge upon the genuineness of the unsecured loan.
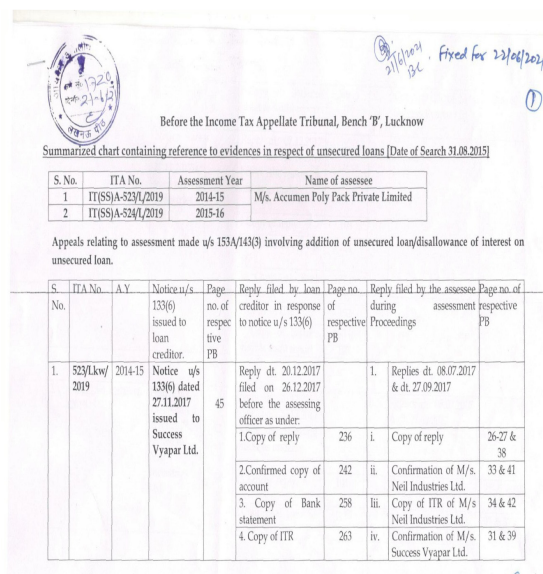
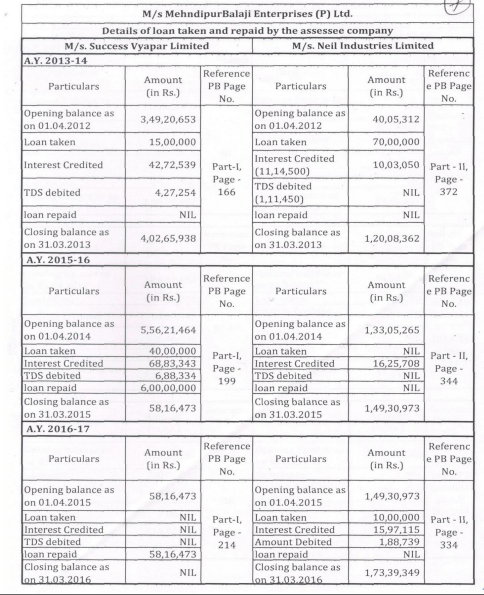
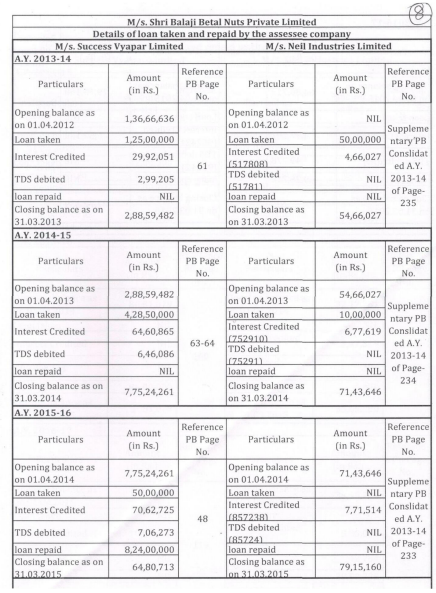
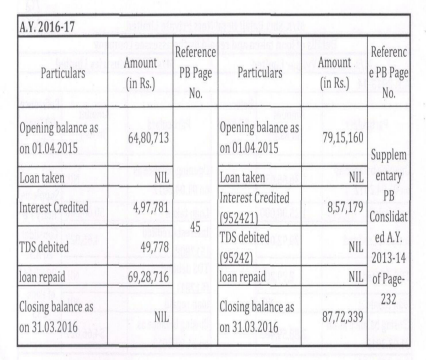
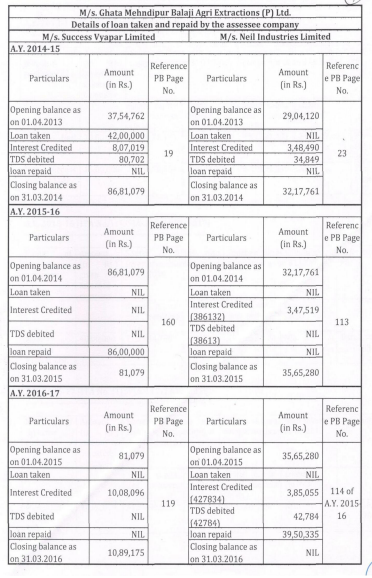
5. Because the Learned CIT(A) has erred in law and on facts in confirming the following additions:-
| S.No. | Name of lenders | Amount | Total addition interest |
|---|---|---|---|
| 1 | M/s Neil Industries Ltd. | 2,96,160.00 | 2,96,160.00 |
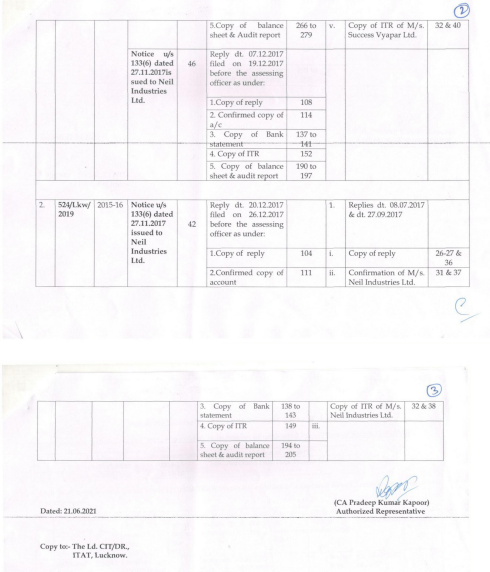
without appreciating the supporting documentary evidences & explanation of the appellant placed on record and ignoring the information obtained u/s 133(6) of the Act from the loan creditor.
6. BECAUSE the learned CIT(A) failed to appreciate that the assessee had duly discharged the onus of proving, all the three vital ingredients of section 68 of the I.T. Act, namely identity of the lenders of unsecured loan, genuineness of the transactions and credit worthiness of the lenders and that such loans in the case of various family members and their business associates had been accepted in the orders passed earlier u/s 143(3)/153C of the Act in the relevant assessment year.
7. BECAUSE the learned CIT(A) has erred in law and on facts in holding that the Assessing Officer had tried his best to provide cross examination of concerned persons whereas virtually required efforts were not made by the AO in enforcing the presence of such persons for their cross examination and even no penal action and /or other coercive measures as provided under the Act was initiated against such persons.
8. BECAUSE in the absence of opportunity of cross examination of the persons giving statement of culpable nature, as had been sought by the appellant, the assessment stood wholly vitiated and consequently the addition made deserved to be deleted as held by the Apex Court in umpteen number of cases.
9. BECAUSE the addition for sum of Rs. 2,96,160/- made by AO and upheld by CIT(A) is based on whims, surmises and conjectures and the cases relied upon by the authorities below are distinguishable from the facts of the present case, which resulted in high pitched assessment.
10. BECAUSE the lower authorities have failed to consider various case laws relied upon by the appellant & also the guidelines issued by CBDT relating to the procedure to be adopted by AO in respect of addition under section 68 of the Act and the case laws relied upon by the authorities below are distinguishable from the facts of the present case.
11. BECAUSE various adverse observations and allegations made by the lower authorities are contrary to the facts, material & evidences available on record.
12. BECAUSE in relation to the Grounds of Appeal, the appellant relies upon