Back


2025 Supreme(Online)(ITAT) 3774
INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
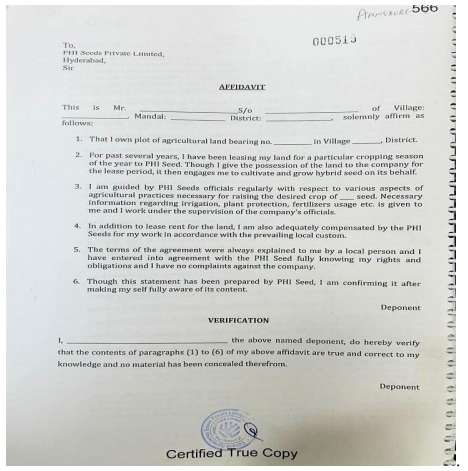
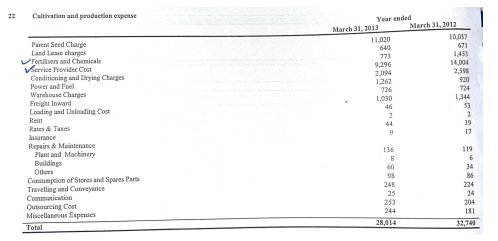
Brajresh Kumar Singh, AM, Vikas Awasthy, JM
PHI SEEDS PVT. LTD. HYDERABAD – Appellant
Versus
ADDL.CIT SPECIAL RANGE-7 NEW DELHI – Respondent
ITA No.1575/DEL/2018 | ITA No.7375/DEL/2018 | ITA No.9205/DEL/2019
For the Appellants/Petitioners: Not mentioned
For the Respondents: Not mentioned
Income derived from agricultural activities must involve basic agricultural operations; mere procurement does not qualify for exemption under section 10(1).
Headnote:This judgment deals with three appeals concerning the denial of agricultural income exemption under section 10(1) of the Income Tax Act, 1961. The court analyzed the activities of the assessee involved with agricultural operations and determined that they do not qualify for such an exemption. From the judgement, it follows that agricultural income entails the necessity of performing basic agricultural operations, which the assessee was found lacking. The court upheld the findings of the lower authorities stating that the income in question constituted business income rather than agricultural income. "The assessee does not own any agricultural land" (para 4.4). The court concluded that there was no basis for granting exemption under section 10(1) due to the absence of actual cultivation (para 14.9). The appeals were dismissed.
| Table of Content |
|---|
| 1. ultimate conclusion regarding exemption of agricultural income. (Para 1 , 2 , 3 , 4 , 5 , 6) |
| 2. description of the activities and operational audits leading to tax implications. (Para 8 , 9 , 10 , 11 , 12) |
| 3. delineation of legal framework regarding agricultural income qualification. (Para 13 , 14) |
ORDER
PER BRAJESH KUMAR SINGH, AM,
This is a bunch of three appeals filed by the assessee, pertaining to assessment years 2013-14, 2014-15 and 2015-16, respectively. Since identical and similar issues are involved in all these appeals and were heard together, these are being disposed of by this common order for the sake of convenience and brevity.
The details of the appeals are as under:-
| Sl. No. | ITA No. | Assessment Year | Against/Arising out of |
| 1 | 1575/Del/2018 | 2013-14 | Order dated 17.11.2017 of the Ld. CIT(A) arising out of Assessment order u/s 143(3)/144C(3) of the Act dated 28.02.2017, relevant TPO order u/s 92CA(3) is dated 27.10.2016 |
| 2 | 7375/Del/2018 | 2014-15 | Order dated 28.08.2018 of the Ld. CIT(A) arising out of order u/s 143(3)/92CA/144C(3) of the Act, TPO order dated 25.10.2017 |
| 3 | 9205/Del/2019 | 2015-16 | Assessing Officer’s order dated 30.09.2019 u/s 144C(13) r.w.s. 143(3) of the Act arising out of Dispute Resolution Panel’s direction dated 25.07.2019 u/s 144C(5) of the Act. |
ITA No. 1575/DEL/2018 [AY 2013-14]
2. First of all, we take up the appeal for assessment year 2013-14. The assessee is in appeal against the order dated 17.11.2017 passed by the Ld. CIT(A)-38, New Delhi arising out of assessment order passed under section 143(3)/144C(3) of the Income Tax Act, 1961 (hereinafter referred as ‘the Act’), dated 28.02.2017 passed by the Addl. CIT, Special Range-7, Delhi.
3. Brief facts of the case: The assessee is a company incorporated under the Companies Act, 1956 and is a 100% subsidiary of Pioneeer Overseas Corpn. USA (POC). In the relevant AY 2013-14, the assessee filed its return of income on 30.11.2013 declaring total income of Rs.40,03,75,727/- after claiming exemption under section 2(1A) r.w.s. 10(1) of the Income-tax Act, 1961 in respect of agricultural income amounting to Rs.124,59,41,832/-. According to the assessee- company, the main activity of the company is to procure various varieties of seeds from growers, processing and packing, and subsequent sale. The procurement of seeds from growers is at a fixed rate. The procurement cost is bifurcated in the books of account under the following heads: a) Land Lease Rent b) Fertilizers & Chemicals c) Labour& Service Charges The case of the assessee was selected for complete scrutiny assessment under section 143(2) of the Act. The AO show issued the assessee a show-cause notice dated 07.12.2016 asking the assessee to explain as to why the income of Rs.124,59,41,832/- claimed to be exempt u/s 2(1A) r.w.s. 10(1) of the Act be treated as business income and thus taxed accordingly.
3.1. The assessee submitted that its claim of business activities being agricultural in nature, is entitled for exemption under section 10 (1) of the Act. The AO rejected the contention raised by the assessee and held that the charges for supervision and guidance cannot be said to be agricultural activities within the meaning of the Act. It was further held that the assessee does not indulge in agricultural operations in accordance with tests laid in the judgment of the Hon’ble Supreme Court in the case of CIT Vs. Raja Benoy Kumar Sahas Roy 32 ITR 460. In view of the above, the claim of exemption under section 10 (1) of the Act amounting to Rs.124,59,41,832/- was denied to be assessee. Further, Transfer Pricing Adjustment u/s 92CA of the Act amounting to Rs.67,17,965/- was also made on account of receivables received from its Associate Enterprises (in short ‘AEs’) beyond the period of more than 30 days being not received. Further additions on account of disallowance u/s 37(1) of the Act (Rs.54,91,340/-) being capital in nature and disallowance u/s 43B of the Act (Rs.2,84,85,605/-) on account of unpaid grat