Back


2025 Supreme(Online)(ITAT) 3833
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
Sandeep Gosain, JM, Girish Agrawal, AM
Income Tax Department – Appellant
Versus
Shri Vimal Punmiya – Respondent
ITA No. 1885/Mum/2025
For the Appellants/Petitioners: Shri Annavaran Kosuri, Sr. AR
For the Respondents: Shri Vimal Punmiya, CA
The addition of sale proceeds as unexplained cash credit without cogent evidence is not sustainable under Income Tax laws.
Headnote:This judgment addresses the appeal made by the revenue against the CIT(A)'s order which had deleted additions made under section 68 relating to the sale of shares of a penny stock. The court found that the revenue's claims lacked substantial evidence tying the respondent's gains to alleged tax evasion activities. The court highlighted that established documentary evidence supported the respondent's transactions, aligning with section 10(38). Ultimately, the appeal was dismissed, affirming the CIT(A)'s findings; the long-term capital gains were substantiated and entitled to exemption under section 10(38).
| Table of Content |
|---|
| 1. the appeal concerns the deletion of additions related to long-term capital gains arising from penny stock transactions. (Para 1 , 2 , 3) |
| 2. the evidence presented supports the respondent's claim, emphasizing the legitimacy of the reported gains. (Para 4 , 5 , 6) |
| 3. the revenue's arguments based on hearsay and third-party information lack substantiation. (Para 7 , 8 , 9 , 10) |
| 4. the court finds that the documentation provided establishes the transactions as genuine. (Para 11 , 12 , 13) |
| 5. the cit(a) rightly allowed the exemption under section 10(38), and the appeal is dismissed. (Para 14 , 15) |
ORDER
PER SANDEEP GOSAIN, JM:
The present appeal has been filed by the revenue challenging the impugned order dt. 22.01.2025 passed u/s 263 of the Income Tax Act, 1961 (‘the Act’), by the National Faceless Appeal Centre, Delhi (NFAC) for the assessment year 2011-12.
2. All the ground raised by the revenue are interrelated and interconnected and relates to challenging the order of Ld. CIT(A) in deleting the additions made u/s 68 of the Act. Therefore we have decided to adjudicate the same through the present consolidated order.
3. Ld. DR appearing on behalf of the revenue while relying upon the order of AO submitted that the scrip M/s. Splash Media & Infra Ltd (Now know as Loharuka Media & Infra Ltd) is a penny stock scrip and the assessee during the course of assessment proceedings had categorically admitted that she was minor at the time of investment in the scrip and thus all the investments were made by her father Shril Anil Kumar Agarwal who operated a share broking company viz M/s. Comforts Pvt Ltd, whose case such action u/s 132 of the Income Tax Act was carried out by the Mumbai Investigation Wing and during the course of search action the said Shri Anil Kumar Agarwal in his statement recorded u/s 132(4) of the Act had categorically admitted that the said scrip to be a penny stock. It was further submitted that the said Anil Kumar Agarwal also stated in detail the process, how the transactions in penny scrip take place to the stock exchange with the connivance of commission agents on nominal commission in cash in order to provide bogus and LTCG / STCG through rigging of shares. Ld. DR also challenged the order of Ld. CIT(A) by submitting that Ld. CIT(A) deleted the additions while ignoring all the vital aspects which leads to the conclusion that M/s Splash Media & Infra Ltd was a penny script and that the assessee’s investments in A grade shares such as Reliance Power etc, is very low and in very small quantity as compared to the investments made in the penny scrip of M/s. Splash Media and Infra Ltd. Thus requested to set aside the order of CIT(A) and requested to uphold the order of AO.
4. On the contrary, Ld. AR while relying upon the order passed by Ld. CIT(A) submitted that assessee had entered into a genuine transactions in the said scrip and therefore additions were wrongly made by the AO u/s 68 of the Act treating the total sale consideration received from sale of M/s. Splash Media & Infra Ltd as income from other sources. Ld. AR also relied upon his written submissions filed before us and the same is reproduced herein below:
A. Brief facts of the case
1. The appellant is an individual having income for the year under consideration from income from the head capital gain and income from other sources. Return of Income was originally filed on 21/07/2011 declaring total income of Rs. 1,11,889/- which was processed u/s.143 (1)of the Income Tax Act, 1961 .
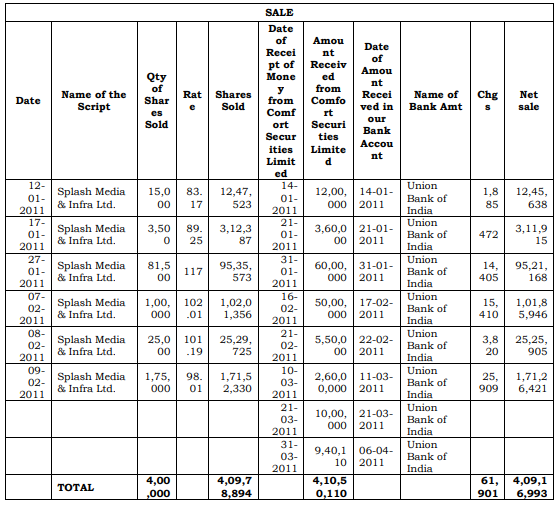
2. In the above return, the assessee had income from LTCG from sale of scrip M/s Splash Media of Rs. 3,56,92,613/- which was claimed exempt u/s 10(38) which reflected in the Profit and Loss Account. (PB Pg. No. 3)
3. The assessee is a regular investor. The same can be verified from Investment in the Balance Sheet (PB Pg No. 3 and 6). The assessee has sizable portfolio.
4. Further we would like to state that the father of appellant has purchased10,000 shares of Splash Me