Back


2025 Supreme(Online)(ITAT) 4098
INCOME TAX APPELLATE TRIBUNAL (CHENNAI BENCH)
S.S. Viswanethra Ravi, J, S.R. Raghunatha, ACJ
Revenue – Appellant
Versus
Assessee – Respondent
Income Tax Appeal/ITA Nos.: 370 & 368/Chny/2025 | Cross Objections/CO Nos.32 & 33/Chny/2025
For the Appellants/Petitioners: Shri. P. Krishna Kumar, J.C.I.T.
For the Respondents:Shri. N. Arjun Raj, Advocate
The non-filing of an audit report within the stipulated time under Section 139(1) of the Income Tax Act is viewed as a procedural lapse, not a ground to deny tax exemption under Section 10(23C)(v).
Headnote:This judgment concerns appeals filed by the Revenue and cross objections from the Assessee regarding tax exemption claims under Section 10(23C)(v) of the Income Tax Act for assessment years 2013-14 and 2014-15. The Tax Appeals addressed whether filing an audit report within the stipulated time was mandatory given that the returns were not filed accordingly. The Court found that the non-filing of the audit report constituted a procedural lapse, referencing prior judicial declarations affirming that such requirements should be regarded as directory. The assessment findings were reviewed and ultimately ruled in favor of the Assessee, affirming the claim for exemption under Section 10(23C)(v) for the income derived from public donations.
| Table of Content |
|---|
| 1. overview of appeals and cross objections regarding exemptions. (Para 1 , 4 , 5 , 6 , 10) |
| 2. judgment focusing on auditing procedures not mandating tax exemption denial. (Para 7 , 8 , 11 , 15) |
| 3. assessment of significant contributions to the temple as non-taxable. (Para 18 , 20 , 22) |
| 4. recognition of procedural flexibility in tax statute compliance. (Para 26 , 28 , 32) |
| 5. final order directing tax exemption applicability to the assessee. (Para 33) |
आदेश/ORDER
PER BENCH:
These appeals filed by the Revenue and cross objections filed by the assessee are directed against the order of the Commissioner of Income Tax (Appeals), National Faceless Appeal Centre (NFAC), Delhi, for the assessment years 2013-14 & 2014-15, vide order dated 20.12.2024. Since the facts are identical and issues are common, appeals filed by the Revenue and Cross objections filed by the assessee were heard and are being disposed of by this consolidated order.
2. The revenue has raised the following common grounds in ITA Nos.370 & 368/Chny/2025:
1. Whether in the facts and circumstances of the case, the National Faceless Appeal Centre (NFAC) is correct in directing the Assessing Officer to allow exemption u/s 11 to the assessee, given the fact that the assessee has failed to file its Audit Report within the due date prescribed u/s 139(1) of the Income Tax Act, 1961 ?
2. Whether in the facts and circumstances of the case, the National Faceless Appeal Centre (NFAC) is correct in directing the Assessing Officer to allow exemption u/s 11 to the assessee, given the fact that the assessee has failed to file its Return of Income within the due date prescribed u/s 139 of the Income Tax Act, 1961 ?
3. The assessee has raised the following common grounds of cross objection in CO Nos.32 & 33/Chny/2025:
1. The order of the National Faceless Appeal Centre, Delhi dated 20.12.2024 vide DIN & Order No.ITBA/NFAC/S/250/2024-25/1071403529(1) in so far as the issues raised in the present Cross Objection for the above mentioned assessment year is contrary to law, facts, and in the circumstances of the case.
2. The NFAC, Delhi erred in directing the verification of the audit report in Form No. 10B/10BB dated 16.02.2022 (which was not filed factually) and hence ought to have appreciated that the assessment of the gross income in such circumstances in contra distinction to the assessment of the net surplus was erroneously confirmed.
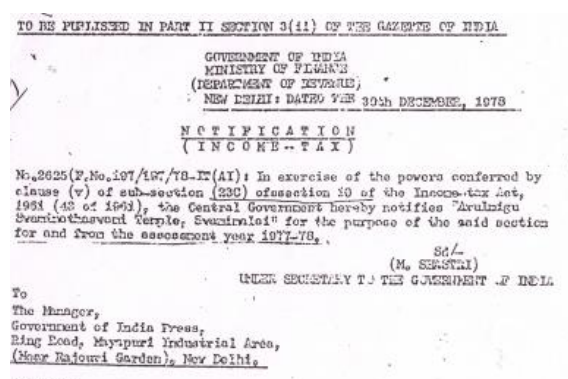
3. The NFAC, Delhi failed to appreciate that mandate prescribed in Section 12A (1)(b)(ii) of the Act / proviso to Section 10 (23C) of the Act for filing audit report within the time stipulated under Section 139 (1) of the Act ought to have been reckoned as directory and not mandatory and further ought to have appreciated that the dispensing with the filing of audit report electronically in Form No. 10B/10BB in the present proceedings (pleaded separately for admission of manual audit report in terms Rule 27/29 of the Income Tax Appellate Tribunal Rules, 1963) being reckoned as continuation of assessment proceedings could validate the claim of tax exemption computation benefit under Section 11 of the Act.
4. The NFAC, Delhi failed to appreciate that in any event, the action of the Assessing Officer in adding back the entire receipts earned / received during the assessment without taking into consideration the related expenditure Incurred in relation to earning of such receipt, i.e. surplus/deficit as per the receipts and payments account, the consequential re-computation of taxable - total income was wrong, erroneous, incorrect, invalid, unjustified and not sustainable both on facts and in law.
5. The NFAC, Delhi erred in impliedly confirming the assumption of jurisdiction under Section 147 of the Act and the consequently erred in impliedly confirming the passing of the re-assessment order dated 28.03.2022 without assigning proper reasons and justification and further ought to have appreciated that the order of re-assessment under consideration was pa