Back


2025 Supreme(Online)(ITAT) 4128
IN THE INCOME TAX APPELLATE TRIBUNAL DELHI BENCH “A” NEW DELHI BEFORE SHRI CHALLA NAGENDRA PRASAD, JUDICIAL MEMBER AND SHRI M BALAGANESH, ACCOUNTANT MEMBER आ.अ.स/ं .I.T.A No.4053/Del/2024 िनधा(cid:9)रणवष(cid:9)/Assessment Year: 2017-18
बनाम
Assessee by Shri Deepak Upadhyay, CA Revenue by Shri Ajay Kumar Arora, Sr. DR सनु वाईक(cid:8)तारीख/ Date of hearing: 05.06.2025 उ(cid:14)ोषणाक(cid:8)तारीख/Pronouncement on 30.07.2025
For the Appellants/Petitioners: Shri Deepak Upadhyay, CA
For the Respondents: Shri Ajay Kumar Arora, Sr. DR
The validity of assessment is contingent upon compliance with prescribed notice formats under CBDT instructions, failing which the proceedings are void ab initio.
Headnote:This appeal concerns the assessment for AY 2017-18, where the appellant contested the addition made by the Assessing Officer without proper jurisdiction. The Court found merit in the appellant's challenge regarding notice validity under CBDT instructions. The Court ruled that the notice was invalid as it did not comply with the required format, leading to the quashing of the assessment. The final verdict stated that the appeal is partly allowed.
| Table of Content |
|---|
| 1. details regarding the appellant's challenge to the assessment. (Para 2 , 3) |
| 2. arguments on the invalidity of notice and jurisdiction issues. (Para 4 , 5) |
| 3. court observations on prior cases addressing similar issues. (Para 7 , 8) |
| 4. final decision on the validity of the assessment. (Para 11) |
आदेश/ORDER
PER C.N. PRASAD, J.M.
This appeal is filed by the Assessee against the order of the Ld. Commissioner of Income Tax (Appeals)-NFAC, Delhi dated 13.6.2024 for the AY 2017-18. The assessee in her appeal raised the following ground:
“The Ld. Assessing Officer is erred in making addition amounting to Rs.2,68,78,500/- without providing an opportunity of being heard in the principles of natural justice.”
2. The assessee also filed application for admission of the following additional grounds:
1. “Ld. AO erred in treating the cash deposit as unexplained cash on basis of books of account without rejecting the same is legally not permissible;
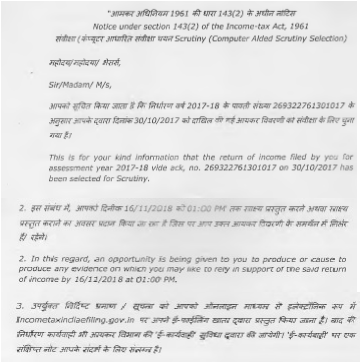
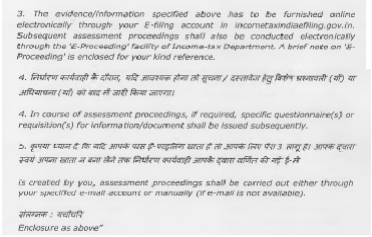
2. On the facts and circumstances of the case, the Assessing Officer erred in issuing notice u/s 143(2) of the Income Tax Act, 1961 dated 09.08.2018 in violation of CBDT Instruction F.No.225/157/2017/ ITA -II dated 23.06.2017. Therefore, the said notice is invalid, and assessment framed pursuant thereto is vitiated in law.”
3. Ld. Counsel for the assessee, at the outset, submits that ground no.2 of additional grounds of appeal filed by the assessee is a legal ground going to the root of the very validity of framing the assessment and therefore the same may be admitted for adjudication. Reliance was placed on the decision of the Hon’ble Supreme Court in the case of NTPC vs. CIT 229 ITR 383.
4. Heard rival submissions. The additional grounds raised by the assessee since going to the root of the very validity of the assessment made based on the notice issued u/s 143(2) the same is admitted for adjudication.
5. Ld. Counsel for the assessee submitted that the notice issued u/s 143(2) by the Assessing Officer on 24.09.2018 is void ab initio having been issued in violation of the binding CBDT Instruction No. F.No.225/157/2017/ ITA -II dated 23.06.2017. Ld. Counsel submits that the CBDT u/s 119 of the Act issued the above instructions prescribing mandatory revised formats for all scrutiny notices issued u/s 143(2) of the Act. He submitted that these instructions are binding on all the Income tax authorities and placed reliance on the decision of the Hon’ble Supreme Court in the case of UCO Bank vs. CIT (237 ITR 889) and Back Office IT Solution Pvt. Ltd. vs. Union of India (2021) SCC OnLine (Del) 2742. Ld. Counsel for the assessee referring to para 3 of the above instructions of CBDT submitted that the Board has directed that all scrutiny notices u/s 143(2) of the Act shall henceforth be issued in the revised formats only. The Ld. Counsel for the assessee submits that in the present case the Assessing Officer did not issue the notice in the prescribed revised format and this is a direct violation of the CBDT’s binding instructions. Ld. Counsel placed reliance on the following decisions:
1. “ Hind Ceramics Pvt. Ltd. vs. DCIT , Circle - 10(1) [ ITA Nos. 608 & 610/KOL/2024] dated 06.05.2025;
2. Tapas Kumar Das v. ITO, Ward-50(5), Kolkata [ ITA No. 1660/KOL/2024] dated 11.03.2025;
3. Sajal Biswas v. I.T.O, WD 24(1), HOOGHLY [I.T.O, WD 24(1), HOOGHLY] [ ITA No.1244/KOL/2023] dated 26.03.2025; and
4. Srimanta Kumar Shit vs. Assistant Commissioner of Income Tax [I.T.A. No.1911/KOL/2024].”
6. The Ld. Counsel for the assessee further submitted that the issuance of notice u/s 143(2) in proper format is a jurisdictional requirement and any defect therein goes to the root of the assessment proceedings. A notice issued in violation of law cannot confer jurisdiction on the Assessing Officer to proceed with scrutiny assessment. Therefore, he submits that the notice dated 22.09.2018 issued u/s 143(2) is invalid and un-enforceable in law.
7. Heard rival contentions, perused the materials placed before us and the case laws