Back


2025 Supreme(Online)(ITAT) 4171
, , आयकरअपीलीयअिधकरण इंदौर(cid:586)ायपीठ इंदौर IN THE INCOME TAX APPELLATE TRIBUNAL INDORE BENCH, INDORE BEFORE SHRI B.M. BIYANI, ACCOUNTANT MEMBER AND SHRI PARESH M. JOSHI, JUDICIAL MEMBER IT(SS)A Nos.58 to 62/ Ind/ 2023 (AY:2017-18 to 2021-22)
For the Appellants/Petitioners: Shri Ram Kumar Yadav, Shri Anoop Singh, CIT-DRs
For the Respondents:Shri Ashish Goyal, Advocate, Shri N.D. Patwa, Advocate, CA Ms. Shelly Maheshwari, ARs
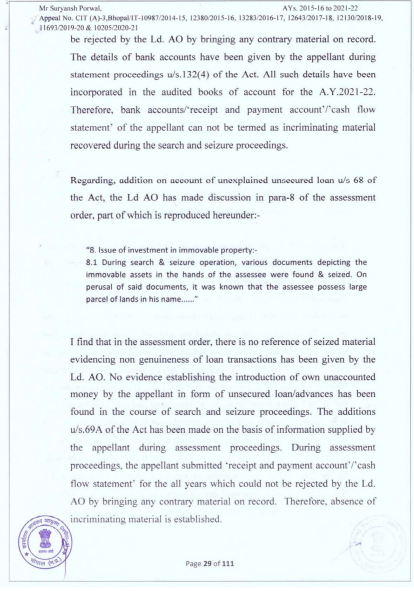
The appellate authority's determinations on unexplained deposits require the presence of incriminating material for successful assessment under the Income Tax Act.
Headnote:In the Income Tax Appellate Tribunal, prosecution was undertaken based on a consolidated appeal regarding income assessment made by the DCIT against the respondent Suryaansh Porwal for various assessment years. The primary legislation involved is section 153A/143(3) of the Income Tax Act, 1961. The court analyzed the incriminating material related to unexplained cash deposits and affirmed the CIT(A)'s decisions of deleting additions based on the absence of incriminating evidence, relying on the landmark case of PCIT Vs. Abhishar Buildwell Pvt. Ltd. The final ruling concludes with the appeals being partly allowed for statistical purposes.
आदेश/ORDER
Per Bench:
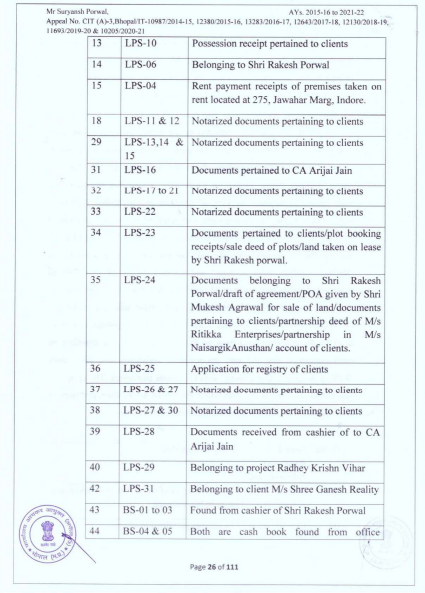
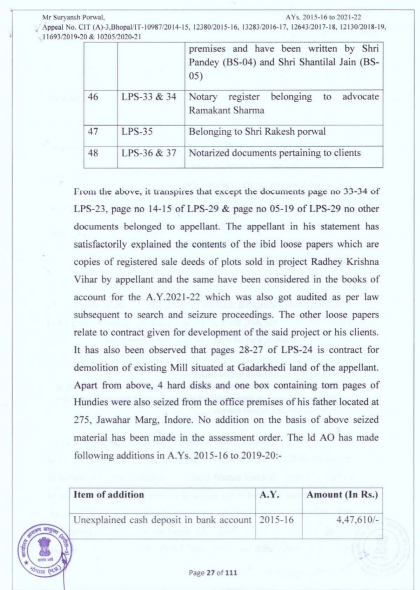
The captioned five (5) appeals are filed by revenue against a consolidated order of first-appeal dated 11.08.2023 passed by learned Commissioner of Income-tax (Appeals)-3, Bhopal [“CIT(A)”], which in turn arises out of a consolidated assessment-order dated 08.09.2022 passed by ACIT (Central)- 1, Indore [“AO”] u/ s 153A/ 143(3) of the Income-tax Act, 1961 [“the Act”] for five Assessment-Years [“AY”] 2017-18 to 2021-22.
-
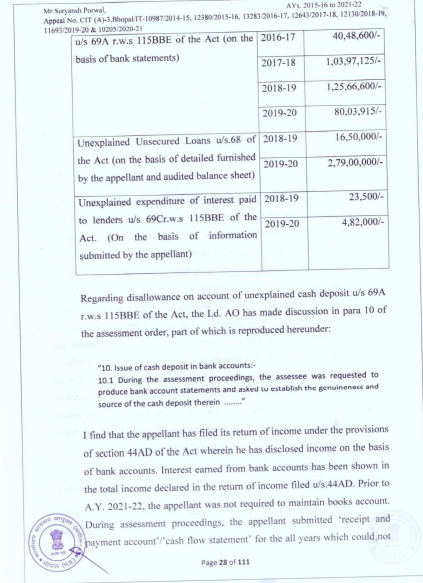
2. The background facts leading to present appeals are such that the assessee is an individual deriving income from business and profession, interest and other sources. A search u/ s 132 was conducted upon “JRG Group” including assessee on 12.01.2021. Pursuant to search proceeding, the assessments of assessee were framed for six preceding AYs 2015-16 to 2020-21 u/ s 153A/ 143(3) and for current AY 2021-22 u/ s 143(3). Presently, in these five appeals, we are concerned with AYs 2017-18 to 2021-22 for which the AO made assessments after making certain additions as under:
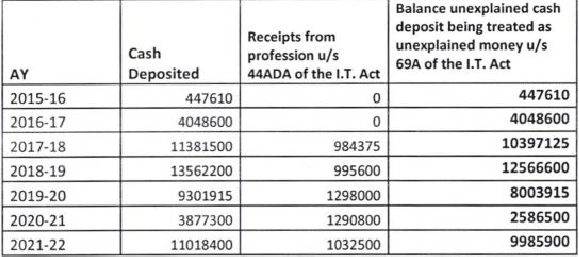
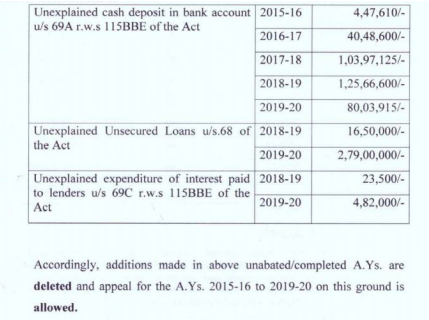
| Natu re of addition | AY 2017-18 | 2018-19 | 2019-20 | 2020-21 | 2021-22 | |
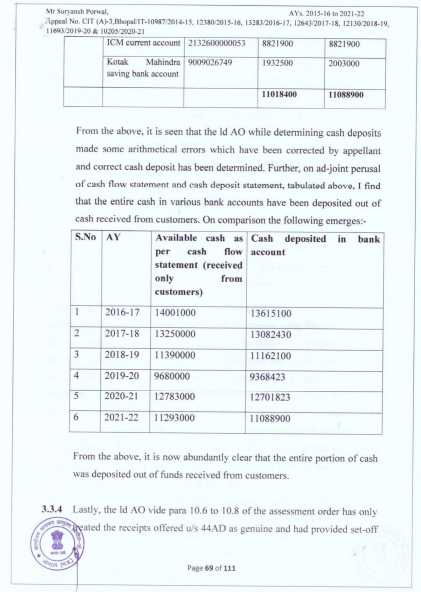
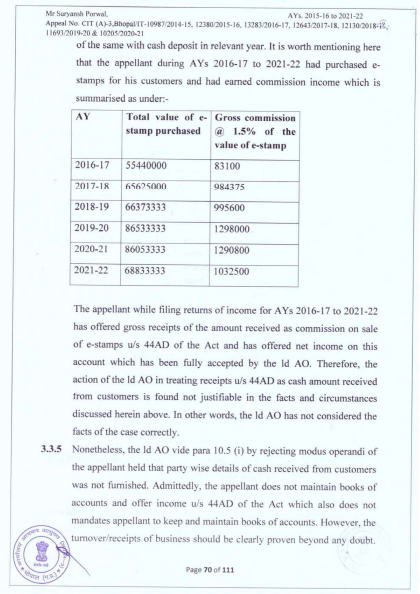
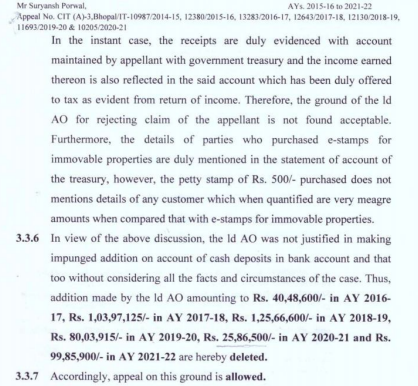
| 1 | Unexplain ed deposi ts in Ban k A/ cs | 1,03,97,125 | 1,25,66,600 | 80,03,915 | 25,86,500 | 99,85,900 |
| 2 | Unexplain ed cash credit s | -- | 16,50,000 | 2,79,00,000 | 76,00,000 | -- |
| 3 | Interest on u n explain ed credit s | -- | 23,500 | 4,82,000 | 5,69,000 | 4,01,597 |
2.1 Aggrieved, the assessee carried matters in first-appeals before CIT(A) and succeeded. Now, the revenue has come in next appeals assailing the orders of first-appeals passed by CIT(A).
3. The assessee also filed three (3) Cross-Objections No. 20/ Ind/ 2024 to 22/ Ind/ 2024 for AYs 2017-18, 2020-21 and 2021-22 but subsequently requested to withdraw those Cross-Objections. Therefore, we have already dismissed those Cross-Objections vide a separate order dated 30.04.2025.
-
4. Since these five appeals emanate from common orders of lower- authorities and the issues raised are also common, they were heard together at the request of parties and are being disposed of by this consolidated order for the sake of convenience, brevity and clarity.
5. The grounds raised in this appeals are as under:
ITA No. 58/Ind/2023 – A.Y. 2017-18:
“1. Whether on the facts and on the circumstances of the case and in law, Ld. CIT(A) was justified in deleting the addition of Rs. 1,03,97,125/ - made on account of unexplained cash deposit u/ s 69A?
2. [2A] Whether on the facts and on the circumstances of the case and in law, Ld. CIT(A) was justified in deleting the addition of Rs. 1,03,97,125/ - made on account of unexplained cash deposit by holding that no incriminating material found?
3. [2B] Whether on the facts and on the circumstances of the case and in law, Ld. CIT(A) was justified in deleting the addition of Rs. 1,03,97,125/ - made on account of unexplained cash deposit by holding that no incriminating material found, ignoring that a)As per ITR filed by theassessee (refer Annex-1 & 2), the assessee has disclosed only one account maintained in Axis Bank, while the addition has been made on the basis of cash deposits in the two other accounts maintained in Axis Bank and State Bank of India, which were not disclosed in the ITR and were found / disclosed during the course of search and seizure operation during the assessee's statement recorded u/ s 132(4) (refer Annex-3), which constituted incriminating material?
4. [2B] b) Apex court in B Kishore Kumar 234 Taxman 771(SC) and Delhi High Court in Best Infrastructure (India) P Ltd [2017] 84 taxmann.com 287 (Delhi) have held that even a statement given during search u/ s 132(4) can be incriminating? c)Though the assessee maintained various bank accounts, only one bank account was disclosed by the assessee in his ITR and it is due to search & seizure operation other bank accounts were disclosed by the assessee in his statement recorded u/ s 132(4) (refer Annex-3), thereby Ld. CIT(A) erred in holding that no incriminating material was found? d) The assessee disclosed only one bank account in his ITR and he disclosed his further set of bank accounts, d