Back


2025 Supreme(Online)(ITAT) 4475
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
C V BHADANG, CJ
Assessee – Appellant
Versus
Revenue – Respondent
I.T.A. No. 4172/Mum/2013 (Assessment Year: 2009-10) | I.T.A. No. 110/Mum/2016 (Assessment Year: 2010-11) | I.T.A. No. 5749/Mum/2015 (Assessment Year: 2010-11) | I.T.A. No. 5750/Mum/2015 (Assessment Year: 2011-12) | I.T.A. No. 111/Mum/2016 (Assessment Year: 2011-12)
For the Appellants/Petitioners: Shri Nitesh S. Joshi, AR
For the Respondents: Shri Rakesh Ranjan-CIT-DR, Shri Leyaqat Ali Aafaqui, Sr. DR
Disallowance under section 14A is not permissible when no exempt income is earned, emphasizing taxation of real income over anticipated income.
Headnote:(A) Income Tax Act, 1961 - Section 14A and Rule 8D - Disallowance of expenditure related to exempt income - The appeals concern the disallowance under section 14A for different assessment years, with the Tribunal admitting additional grounds relating to ESOP deductions and establishing that disallowances must account for actual exempt income and not anticipated earnings - The Tribunal held that disallowance under section 14A is not warranted for AYs when no exempt income was earned, allowing for partial relief in ESOP claims based on fair market value - The Tribunal emphasized that real income, not notional, must be taxed. (Paras 10.1, 13, 40, 54)
(B) Appeals filed by revenue dismissed due to monetary limits set by the CBDT Circular. (Paras 34, 48, 56)
Facts of the case:
The appellant, a manufacturing company, filed revised income returns for AY 2009-10 to 2011-12, resulting in a disallowance of specific expenses under section 14A and associated rules during scrutiny assessments. The Assessing Officer disallowed significant amounts based on scrutiny procedures, prompting appeals by the assessee for reduced disallowances and the revenue for retained disallowances.
Findings of Court:
The Tribunal scrutinized procedural claims, reiterating that no disallowance should occur when the assessee earns no exempt income, ordering reductions in disputed amounts.
Issues: The Tribunal focused on determining the authenticity of claimed expenses, the apportionment of disallowed expenses relative to earned income, and the application of statutory provisions for ESOPs.
Ratio Decidendi: The Tribunal ruled that real income must be considered for tax purposes, with provisions for estimating expenses linked to exempt income limited by actual realized income.
Result: Appeals allowed for AY 2009-10, partially allowed for AY 2010-11, with revenue appeals dismissed.
| Table of Content |
|---|
| 1. background of the appeals. (Para 1 , 2) |
| 2. assessee's arguments on disallowances. (Para 3 , 4 , 5) |
| 3. assessee's additional grounds. (Para 6) |
| 4. court's findings on section 14a. (Para 7 , 8 , 9 , 10 , 20) |
| 5. procedural observations on appeals. (Para 11 , 12) |
| 6. court's rationes regarding disallowances. (Para 13 , 14 , 15) |
| 7. court's findings on commissions. (Para 16 , 17 , 18) |
| 8. observations on esop expenses. (Para 21 , 22) |
| 9. court's ruling on prior period expenditure. (Para 23) |
| 10. court decision on tax effect and dismissals. (Para 25 , 26 , 27 , 32 , 36 , 39) |
| 11. final conclusions and orders. (Para 40 , 42 , 48 , 50 , 56) |
ORDER
Per Padmavathy S, AM:
These cross appeals by the assessee and the revenue are against the separate orders of the Commissioner of Income Tax (Appeals)-4, Mumbai [In short 'CIT(A)'] passed under section 250 of the Income Tax Act, 1961 (the Act) dated 14.03.2013 for AY 2009-10, dated 07.09.2015 for AY 2011-12, dated 04.09.2015 for AY 2010- 11.
AY 2009-10 ITA
No. 4172/Mum/2013
2. The assessee is a company engaged in the business of manufacturing of Fans, Telecommunication, Transmission Line Towers, Hot Dip Galvanizing and trading in electrical appliances, Lamps, Lighting, engineering and project services and generation of wind energy. The assessee filed the return of income for AY 2009-10 on 30.09.2009 declaring a total income of Rs. 144,68,01,374/-. Subsequently the assessee filed a revised return of income on 08.02.2010 and also second time on 30.03.2011 declaring total income of Rs. 160,06,53,482/- and Rs. 145,57,22,635/- respectively. The assessee's case was selected for scrutiny and the statutory notices were duly served on the assessee. The Assessing Officer (AO) completed the assessment by making the following disallowance:
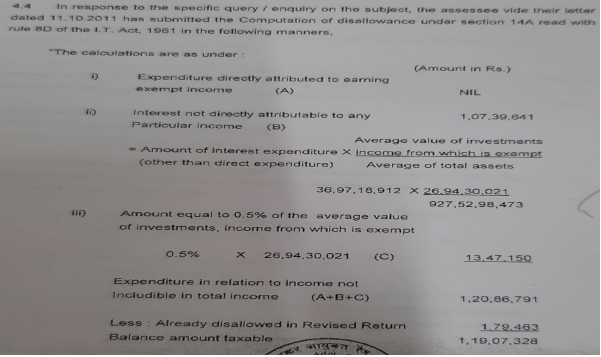
(i) Disallowance under section 14A r.w.r. 8D - Rs. 1,19,07,328/-
(ii) Disallowance of Expenditure towards ESOP - Rs. 7,35,861/-
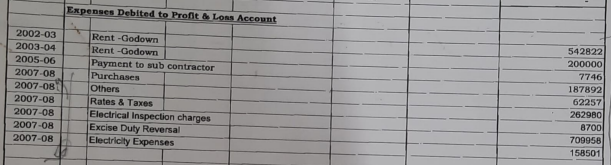
(iii) Disallowance of prior period expenses - Rs. 7,50,558/-
(iv) Difference in TDS information - Rs. 72,254/-
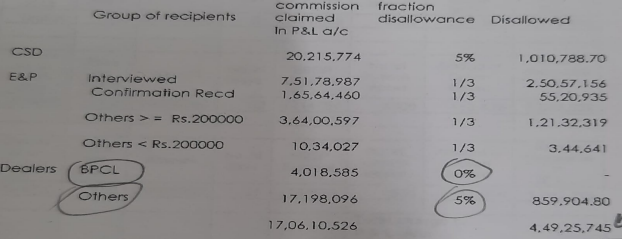
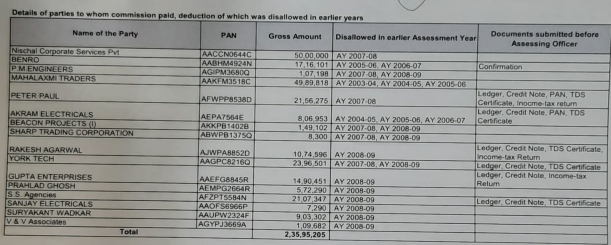
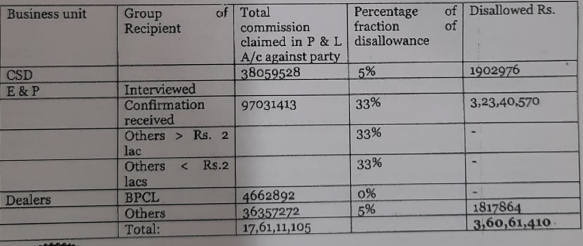
(v) Disallowance of commission - Rs. 1,07,47,659/-
3. Aggrieved the assessee filed further appeal before the CIT(A). The CIT(A) gave partial relief towards the disallowance made under section 14A r.w.r. 8D and confirmed the other additions/disallowances made by the AO. Aggrieved the assessee is in appeal before us contending the following issues:
(i) Additional disallowance under section 14A - Ground No. 1.1 to 1.4
(ii) Ad-hoc disallowance of commission expenses - Ground No. 2
(iii) Disallowance of ESOP expenses - Ground No. 3
(iv) Disallowance of prior period expenses - Ground No. 4
4. The assessee vide letter dated 30.04.2015 has raised the following additional ground with regard to disallowance under section 14A.
(i) On the facts and in the circumstances of the case and in law the appellant prays that investments in shares of domestic companies, dividend from which is subject to tax under section 115-O ought to be excluded for the purpose of computing disallowance under section 14A of the Act.
(ii) Without prejudice to ground no.1 the appellant prays that the strategic investments made in group companies made without the intention of earning exempt dividend income ought to be excluded while computing the disallowance under section 14A of the Act.
(iii) Without prejudice to ground no.1 the appellant prays that investments capable of yielding taxable income ought to be excluded while computing the disallowance under section 14A of the Act.
iv) Without prejudice to ground no.1 the appellant prays that amount of disallowance under section 14A of the Act ought to be restricted to the amount claimed as exempt.
5. The assessee vide letter dated 10-04-2017 & 04.12.2018 raised additional ground with regard to ESOP expenses –
On the facts and circumstances of the case and in law, the appellant prays that deduction in respect of ESOP expenditure of Rs. 3,36,85,160/-ought to be allowed as a deduction while computing the business income which is computed as the