Back


2024 Supreme(Online)(ITAT) 2750
INCOME TAX APPELLATE TRIBUNAL (CHANDIGARH BENCH)
SHRI A.D.JAIN, VP, SHRI VIKRAM SINGH YADAV, AM
Apeejay Education Society – Appellant
Versus
Revenue – Respondent
Income Tax Appeal No. 706/CHD/2022 | Assessment Year: 2012-13
For the Appellants/Petitioners:Shri Salil Kapoor, Advocate
For the Respondents: Smt. Amanpreet Kaur, Sr.DR
The imposition of penalties without adherence to principles of natural justice and absence of a reasoned order undermines legal proceedings, necessitating the reversal of such penalties.
Headnote:(A) Income Tax Act, 1961 - Sections 271(1)(b) and 142(1) - Penalty for non-compliance with notice issued for reassessment proceedings - Assessment was reopened by the Assessing Officer with failure to provide necessary documentation from the assessee leading to penalty of Rs.10,000/- - The court considered whether the principles of natural justice were upheld during the penalty proceedings. (Paras 1-9)
(B) Natural Justice - Requirement of a speaking order - The CIT(A) erroneously affirmed penalty without considering whether the objections of the assessee were addressed adequately - The need to provide a reasoned judgement is fundamental in a quasi-judicial process - The absence of a speaking order renders the penalty order void. (Paras 5.1-9)
Facts of the case:
The assessee, a charitable educational society, contested penalties imposed under Section 271(1)(b) after it was alleged that it failed to comply with notices issued. Multiple requests for clarification from the AO were noted but were not sufficiently addressed, leading to disputes regarding fairness in the proceedings. (Paras 1-9)
Findings of Court:
The penalty was found to be imposed without proper consideration of compliance, and the order was deemed a non-speaking order which is null and void; thus, the penalty was deleted. (Paras 5.1-9)
Issues: Whether the AO upheld the principles of natural justice by addressing the objections raised by the assessee and providing a speaking order as mandated by law.
Ratio Decidendi: The Tribunal ruled that penalties cannot be imposed if the mandatory procedures are not followed and reinforced the importance of a separate speaking order when objections are made against reassessment; such procedural flaws render the case against the assessee invalid. (Paras 5.1-9)
Result: Appeal allowed; penalty of Rs.10,000/- imposed under Section 271(1)(b) is deleted.
ORDER
PER A.D.JAIN, VICE PRESIDENT
This is assessee's appeal for assessment year 2012-13 against the order dated 28.09.2022 passed by the ld. CIT(A) NFAC, Delhi. The following grounds have been taken :
“1. That the learned CIT(A) fell in grave error by passing the order without giving opportunity of hearing to the assessee inspite of his request to do so.
2. That the learned CIT(A) fell into grave error passing a non-speaking order without commenting/adjudicating on the submissions of the assessee.
3. That the learned CIT(A) fell into grave error by not passing a proper speaking order. He fell in grave error by relying oh decision of Hon'ble Apex Court which has no connection with penalty under Section 271 (1)(b).
4. That the learned Commissioner of Income Tax (A)fell into grave error by confirming the penalty of Rs. 10,000/-.
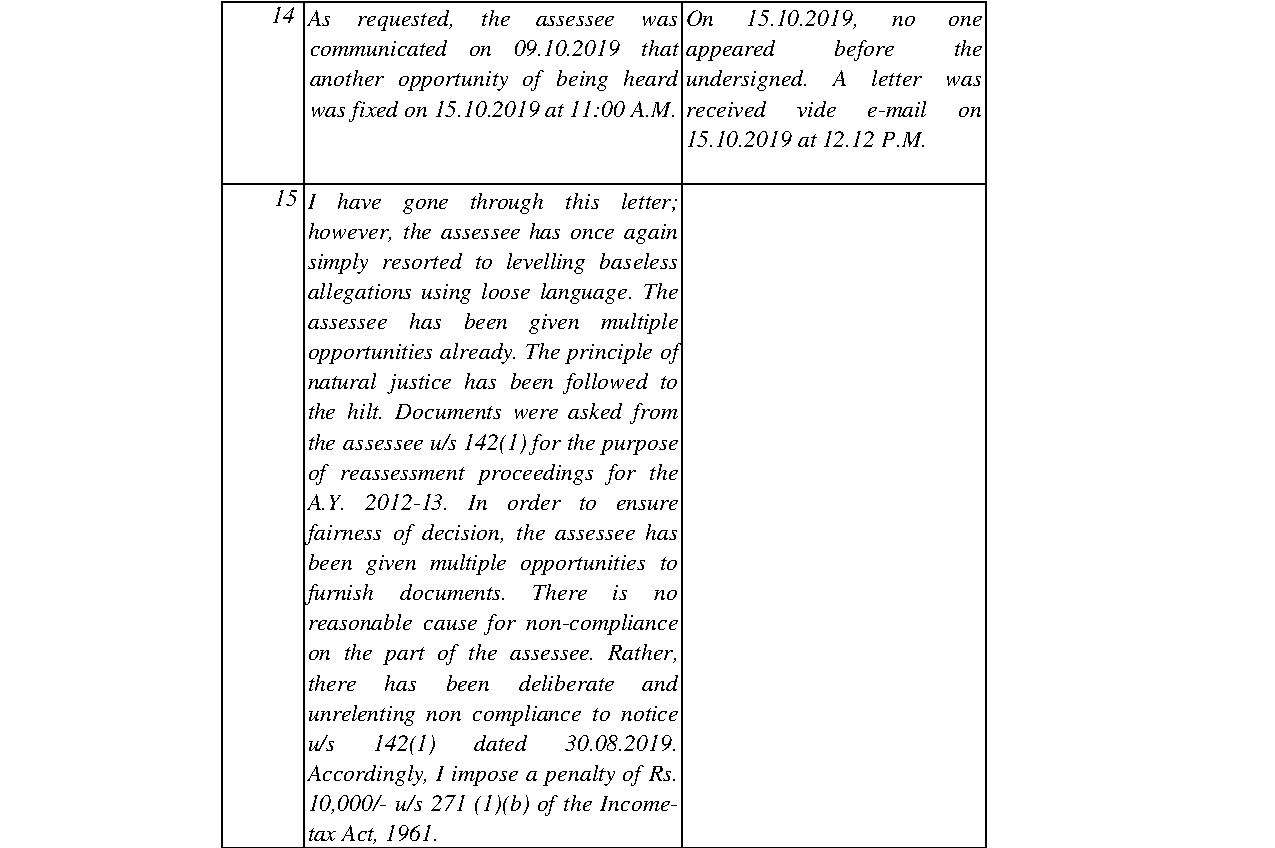
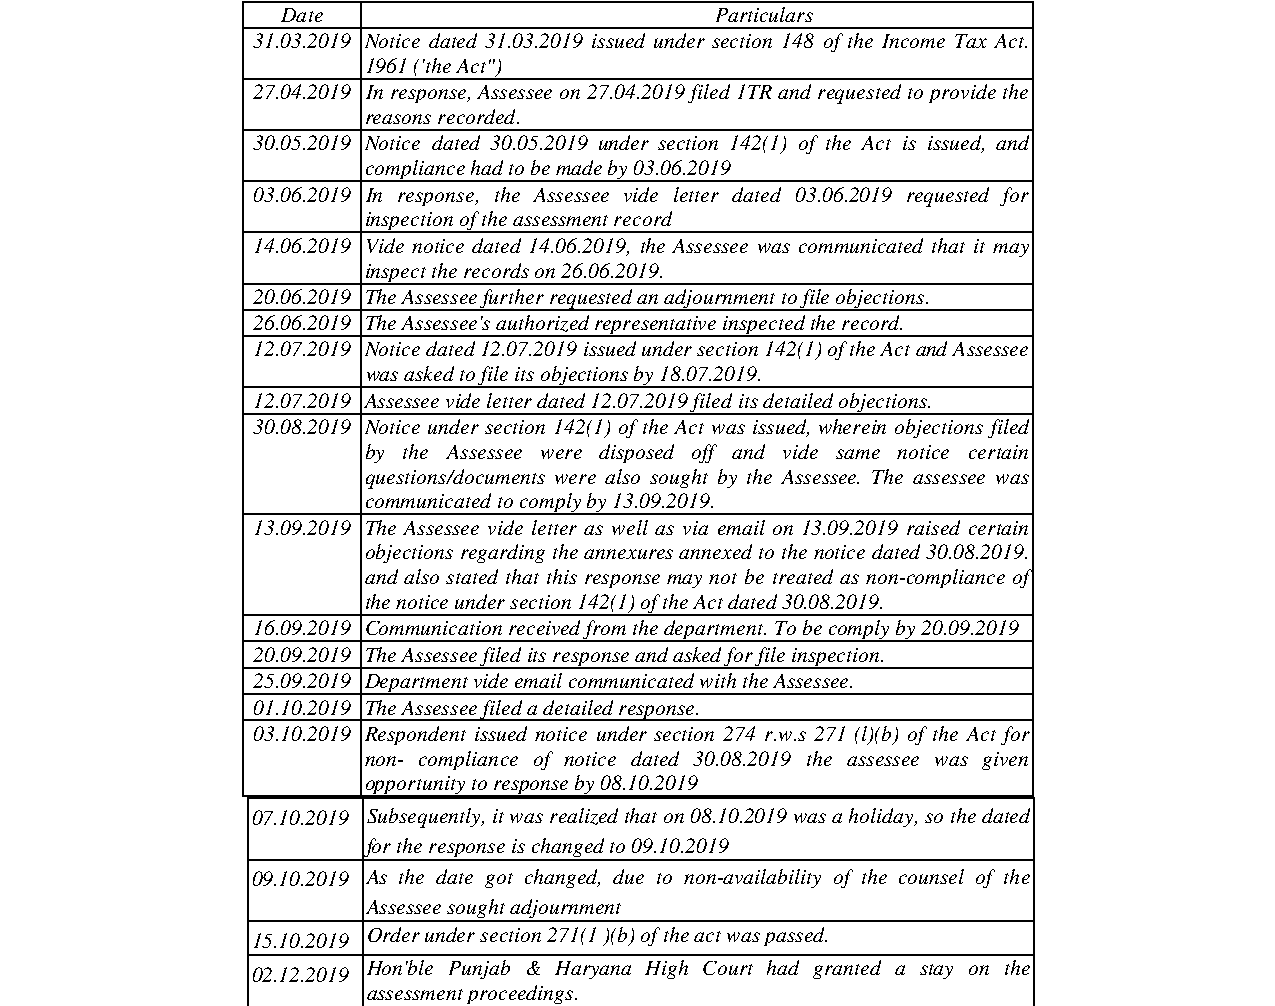
2. The Assessing Officer (in short ‘the AO’), while imposing penalty in question, vide order dated 15.10.2019, observed as follows :
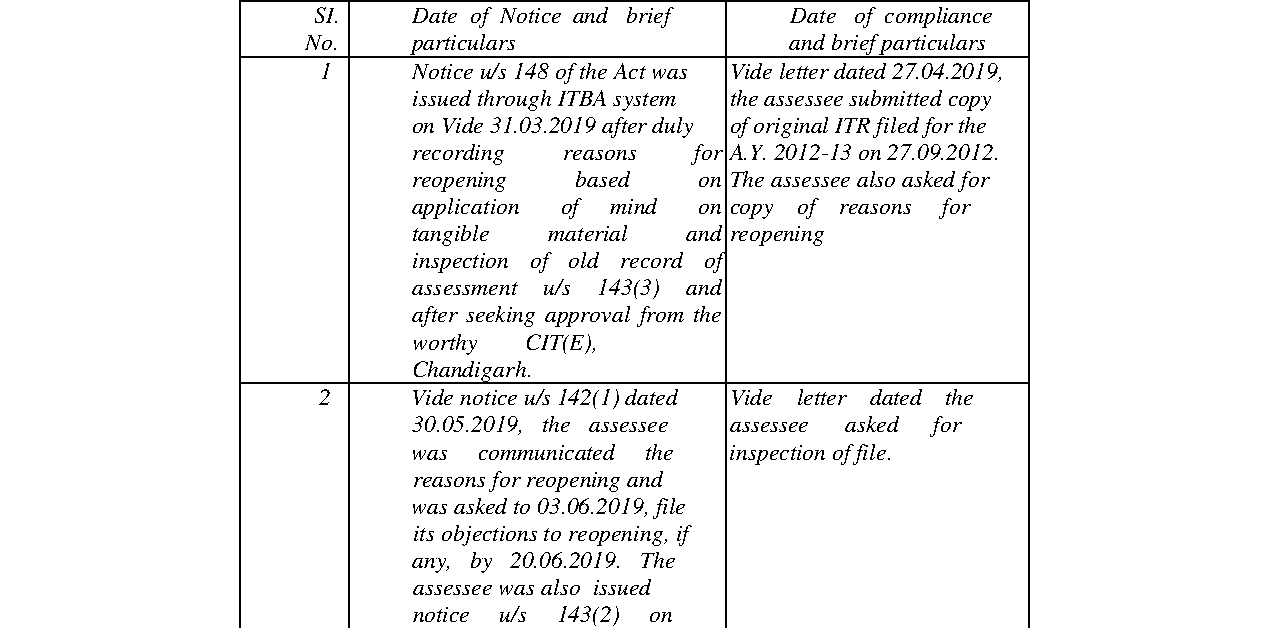
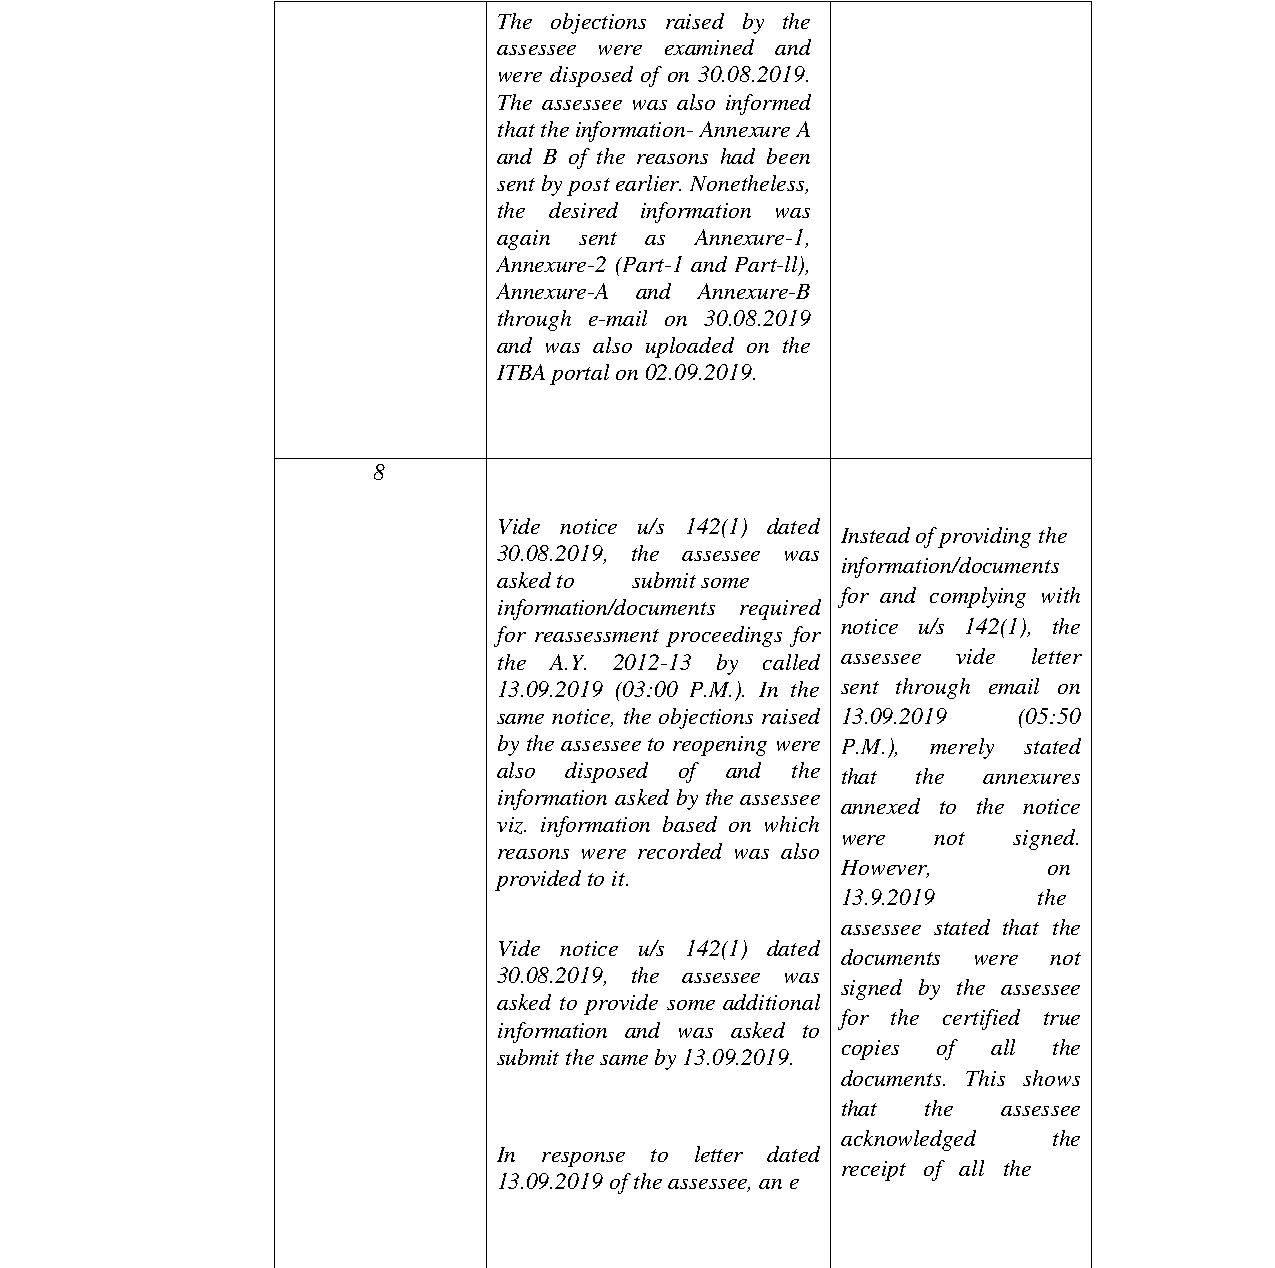
"Vide notice u/s 142(1) dated 30.08.2019 the assessee was asked to submit some information/documents required for reassessment proceedings for the A.Y. 2012-13 by 13.09.2019 (03:00 PM). In the same notice, the objections raised by the assessee to reopening were also disposed of and the information asked by the assessee viz. information based on which reasons were recorded was also provided to it.
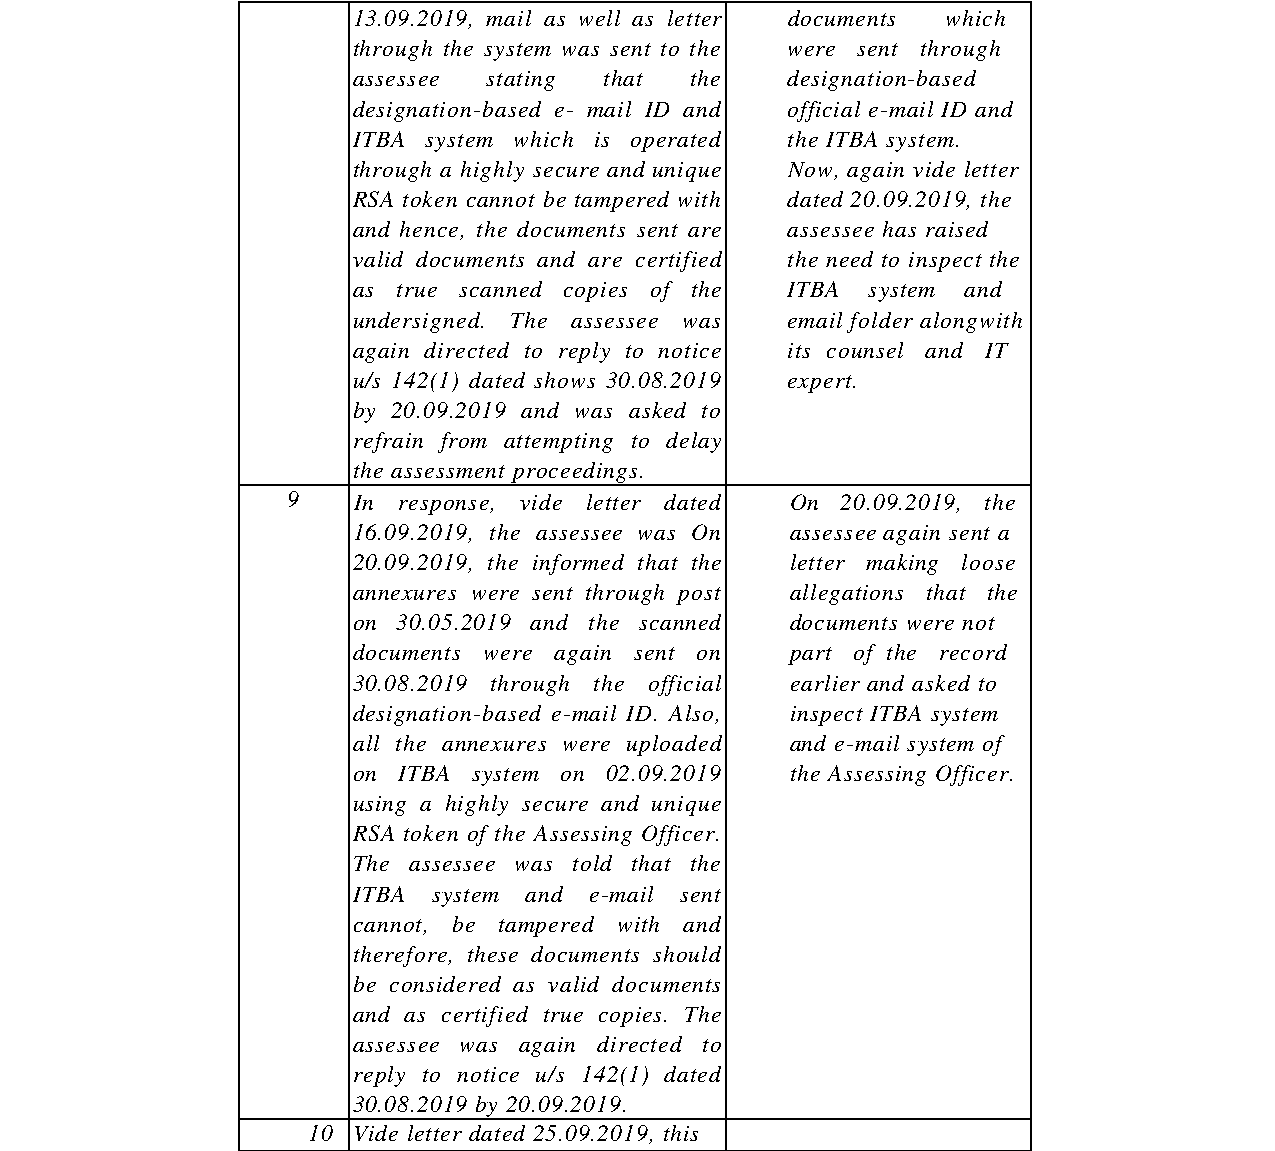
Instead of providing the information/documents called for and complying with notice u/s 142(1), the assessee vide letter sent-through email on 13.09.2019 (05:50 P.M.), merely stated that the annexures annexed to the notice were not signed.
In response, vide letter dated 16.09.2019, the assessee was informed that the annexures were sent through post on 30.05.2019 and the scanned documents were again sent on 30.08.2019 through the official designation-based e-mail ID. Also, all the annexures were uploaded on ITBA system on 02.09.2019 using a highly secure and unique RSA token of the Assessing Officer. The assessee was told that the ITBA system and e- mail sent cannot be tampered with and therefore, these documents should be considered as valid documents and as certified true copies. The assessee was again directed to reply to notice u/s 142(1) dated 30.08.2019 by 20.09.2019.
On 20.09.2019, the assessee again sent a letter making loose allegations that the documents were not part of the record earlier and asked to inspect ITBA system and e-mail system of the Assessing Officer.
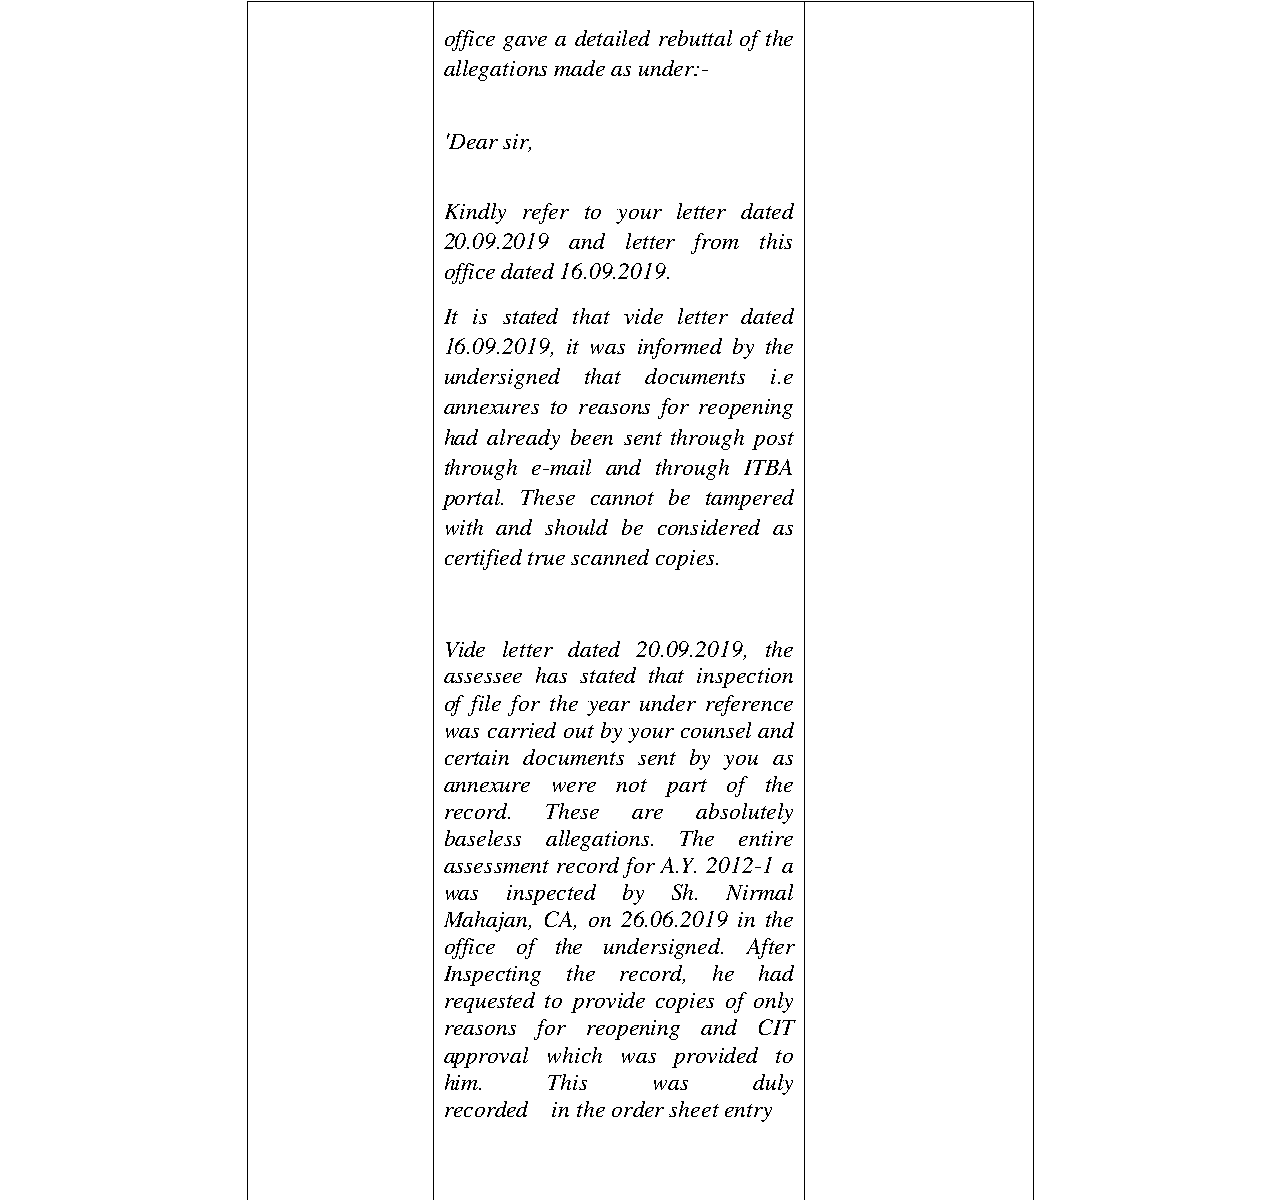
Vide letter dated 25.09.2019, this office gave a detailed rebuttal of the allegations made as under:
Dear sir, Kindly refer to your letter dated 20.09.2019 and letter from this office dated 16.09.2019.
It is stated that vide letter dated 16.09.2019, it was informed by the undersigned that documents i.e. annexures to reasons for reopening had already been sent through post, through e-mail and through ITBA portal. These cannot be tampered with and should be considered as certified true scanned copies.
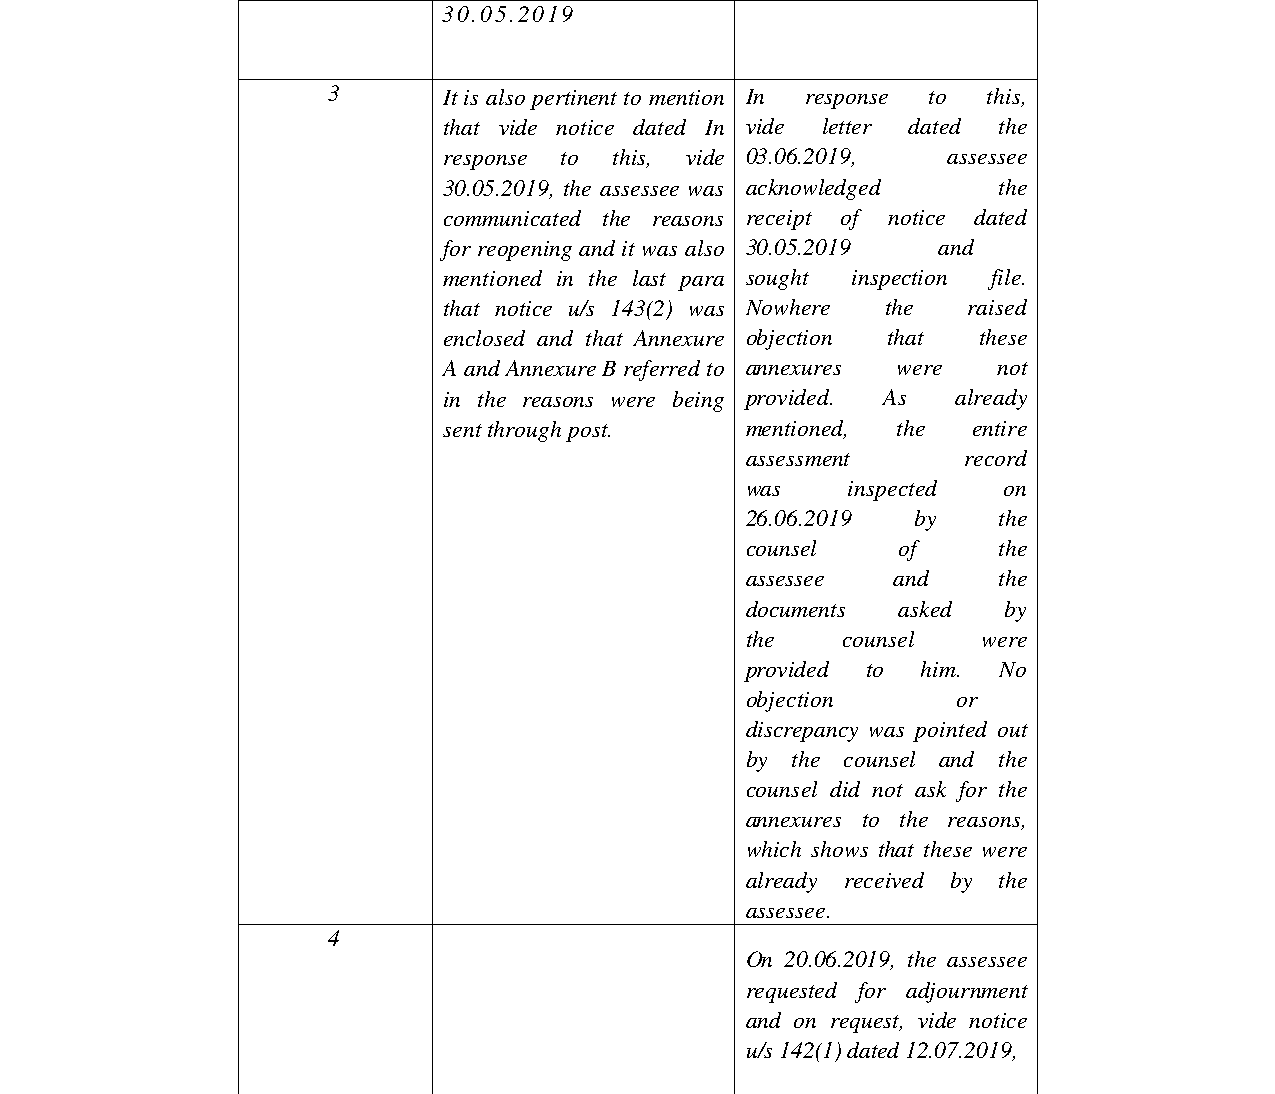
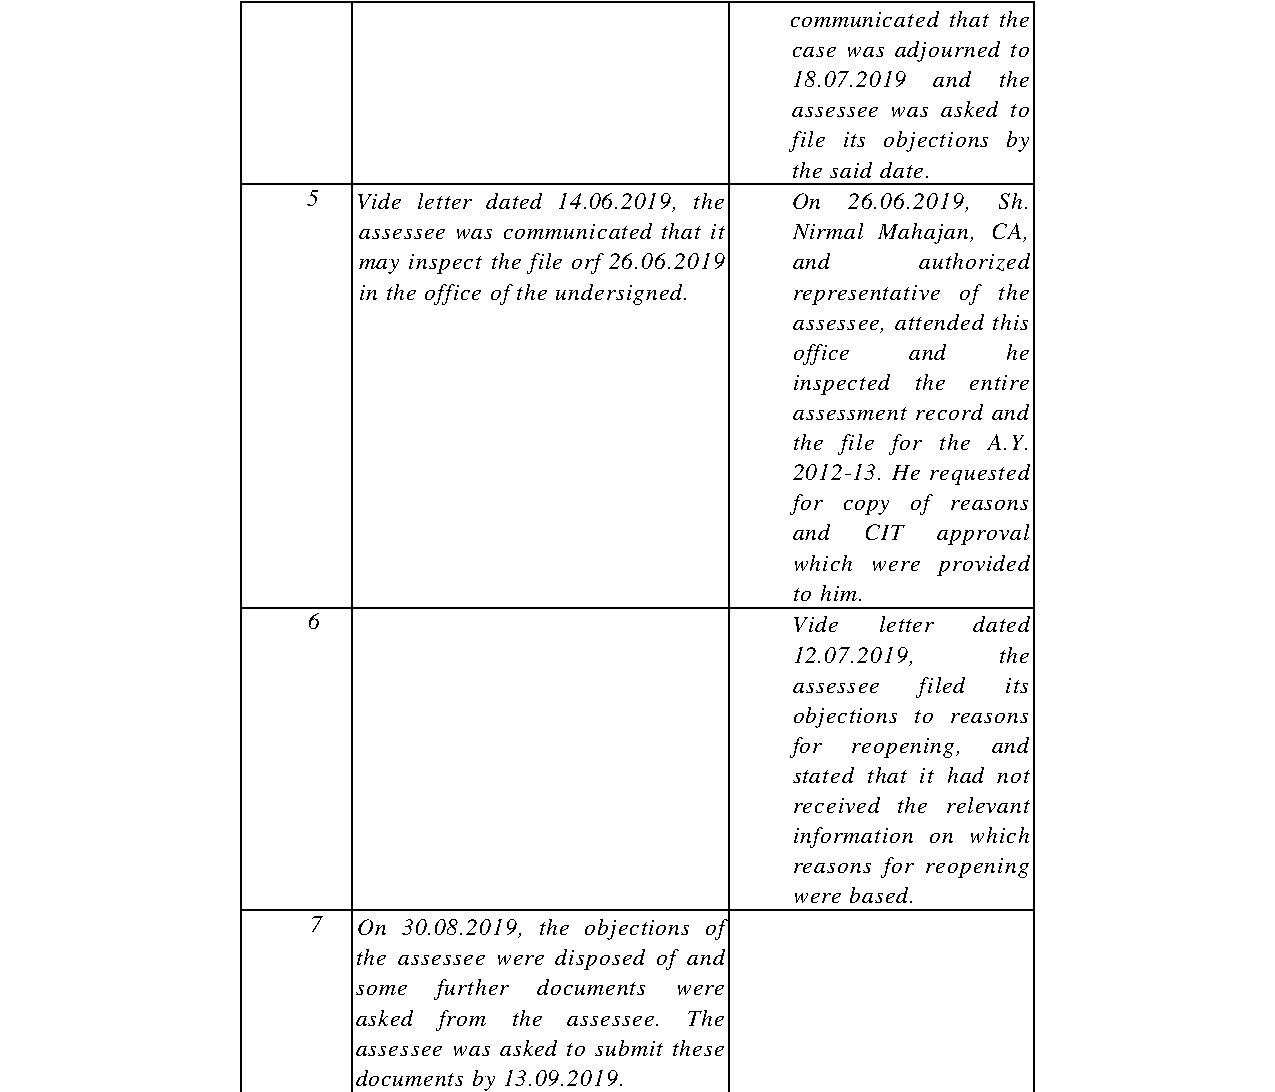
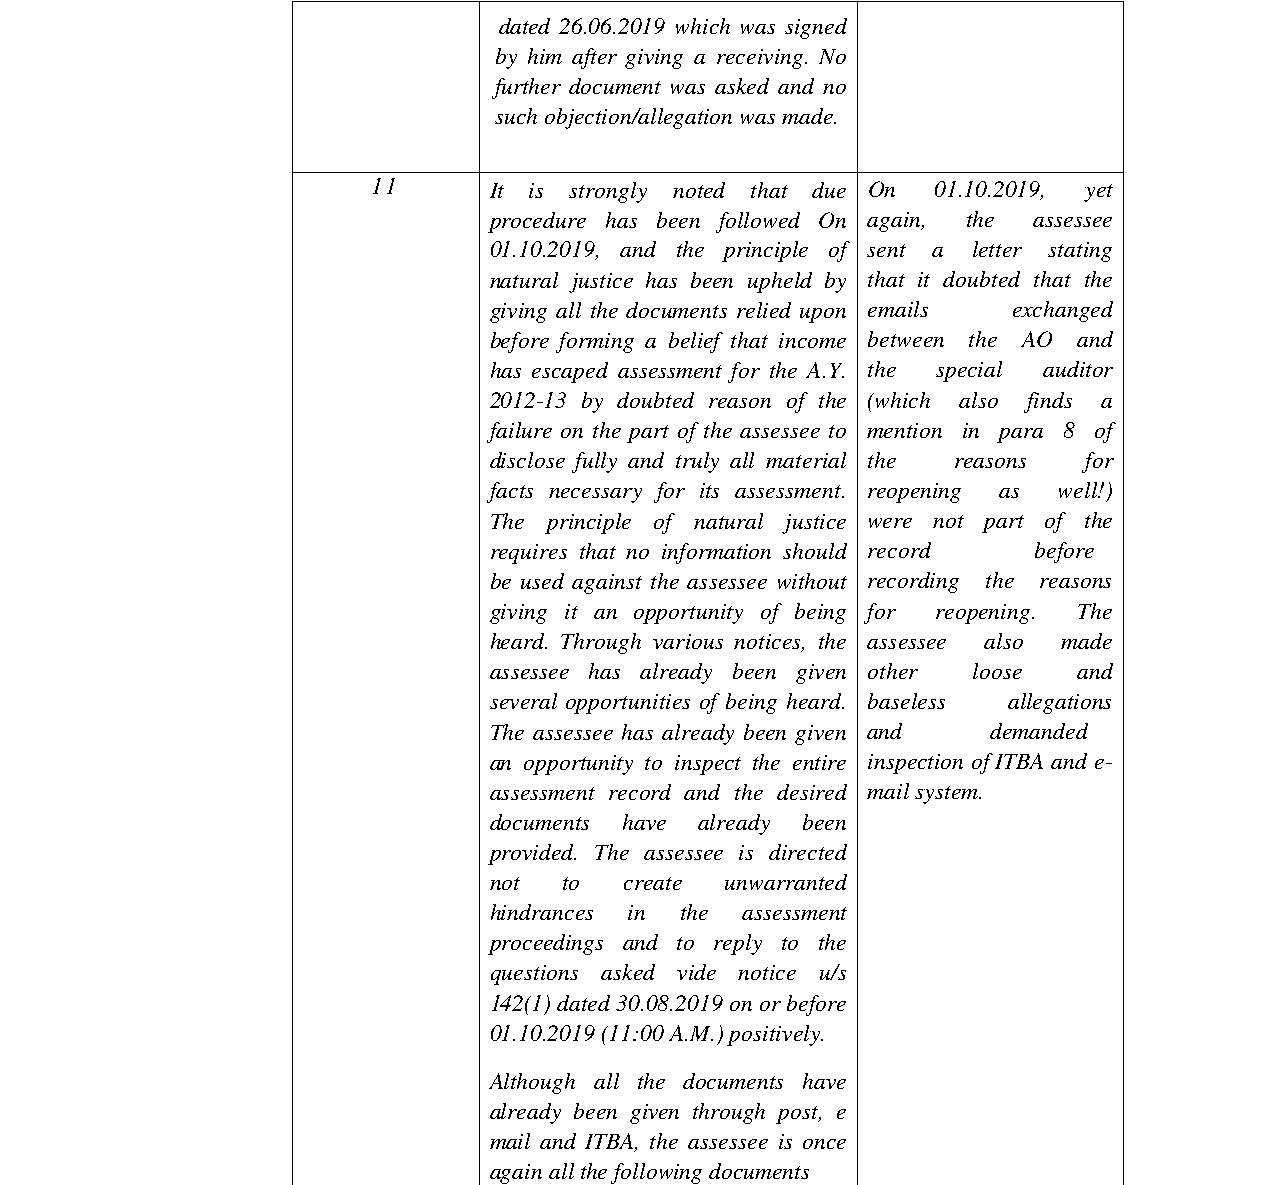
Vide letter dated 20.09.2019, the assessee has stated that inspection of file for the year under reference was carried out by your counsel and certain documents sent by you as annexure were not part of the record. These are absolutely baseless allegations. The entire assessment record for A.Y. 2012-13 was inspected by Sh. Nirmal Mahajan, CA, on 26.06.2019 in the office of the undersigned. After inspecting the record, he had requested to provide copies of only reasons for reopening and CIT approval which was provided to him. This was duly recorded in the order sheet entry dated 26.06.20^9 which was signed by him after giving a receiving. No further document was asked and no such objection/allegation was made.
It is also pertinent to mention that vide notice dated 30.05.2019, the assessee was communicated the reasons for reopening and it was also mentioned in the last para that notice u/s 143(2) was enclosed and that Annexure A and Annexure B referred to in the reasons were being sent through post.
In response to this, vide letter dat