Back


2024 Supreme(Online)(ITAT) 4073
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
SHRI OM PRAKASH KANT, AM, SHRI SUNIL KUMAR SINGH, JM
ACIT 32(1) – Appellant
Versus
VKT Ventures LLP – Respondent
ITA Nos. 2322 & 2349/MUM/2024
For the Appellants/Petitioners: None
For the Respondents: Ms. Rajeshwari Menon, Sr. DR
The court ruled that interest deductibility under Section 36(1)(iii) must consider commercial expediency, rejecting arbitrary disallowances of genuine business expenses.
Headnote:(A) Income Tax Act, 1961 - Section 36(1)(iii) - Disallowance of interest - The appellant firm, engaged in investment and finance, had elected to disallow interest on loans advanced interest-free to parties; however, the Assessing Officer disallowed further interest payment beyond 11%, citing lack of justification for higher rates. The Ld. CIT(A) overturned this decision, observing that the loans' genuineness was not disputed, emphasizing that the AO's scrutiny should focus on commercial expediency rather than simply imposing a reasonableness test. (Paras 4, 7, 7.3, 7.4)
(B) Legal commercial expediency - The court clarified that assessment of interest deductibility relates predominantly to whether funds were employed for business purposes; mere interest-free lending to a subsidiary does not constitute grounds for automatic disallowance, provided it aligns with commercial expediency (Paras 19-32).
Facts of the case:
The appeals challenge disallowance of interest claimed by the appellant firm on borrowed capital due to claims of improper management of funds allocated to interest-free loans, with competing evaluations from the Assessing Officer and appellant. The appellant's previous disallowance of Rs. 7,70,05,688 was argued as adequate against additional claims (Paras 2, 3, 7.2).
Findings of Court:
The Ld. CIT(A) reasoned that once it was established that interest had been paid and the loans were genuine, subsequent disallowance was unjust, resulting in a favorable outcome for the appellant (Paras 8, 8.1).
Issues: The principal issue was whether the expenses claimed by the assessee as interest payments met the criteria of business purpose and if the additional disallowance effort was valid (Paras 4, 5).
Ratio Decidendi: The court held that interest should not be disallowed without sufficient justification on the grounds of commercial expediency, guarding against overreach by tax authorities in probing genuine business inputs (Para 7.5).
Result: Both appeals are allowed for statistical purposes.
| Table of Content |
|---|
| 1. overview of appeals against cit orders. (Para 1 , 2) |
| 2. disallowance of interest under scrutiny. (Para 3 , 4) |
| 3. analysis of commercial expediency in interest deductions. (Para 7) |
| 4. final adjudication of appeals. (Para 8 , 9) |
ORDER
PER OM PRAKASH KANT, AM
These appeals by the Revenue are directed against two separate orders dated 06.03.2024 and 07.03.2024 passed by the Ld. Commissioner of Income-tax (Appeals) — National Faceless Appeal Centre, Delhi [in short ‘the Ld. CIT(A)’] for assessment year 2013-14 and 2014-15 respectively.
2. The sole ground involved in both these appeals is in respect of the disallowance of interest u/s 36(1)(iii) of the Income-tax Act, 1961 (in short ‘the Act). Therefore, both these appeals were heard together and disposed off by way of this consolidated order for convenience. For Brevity the ground raised by the assessee in assessment year 2013-14 is reproduced as under:
1. On the facts and in the circumstances of the case and in law, the Ld. CIT(A) erred in deleting the disallowance of interest of Rs.123046063/- u/s 36(1)(iii) of the Income Tax Act.
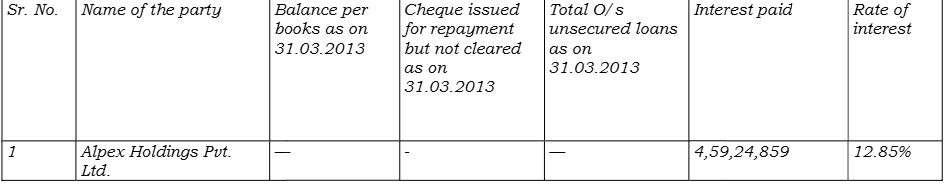
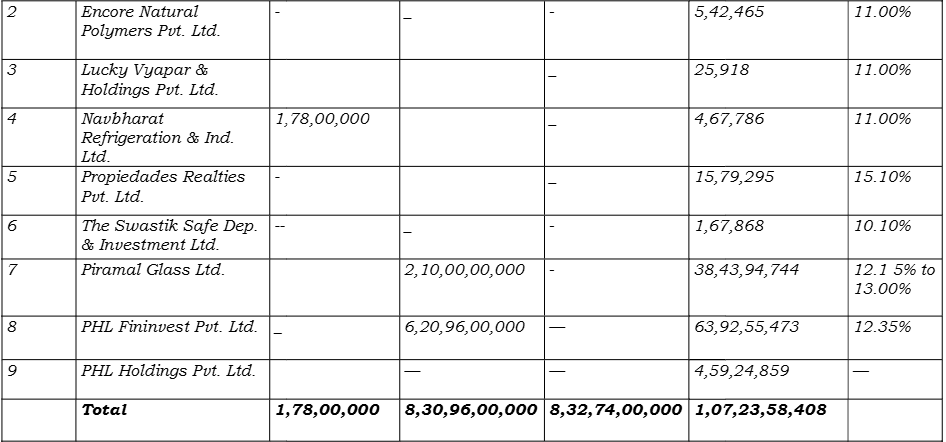
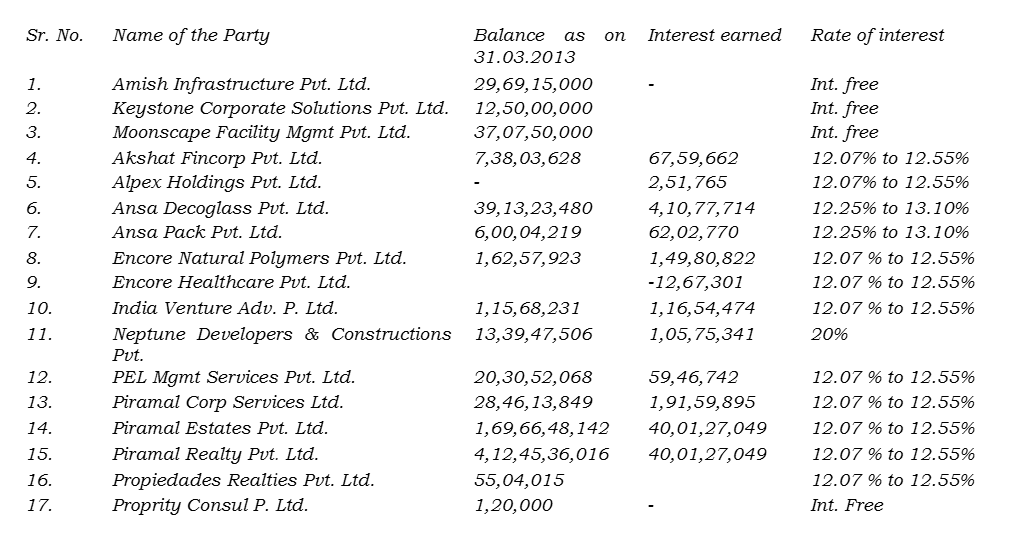
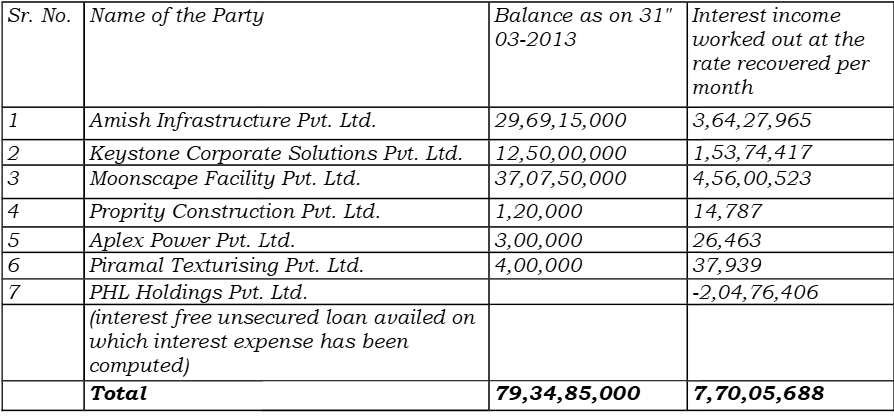
3. Briefly stated facts of the case are that the assessee firm is in the business of investment and finance activity along with trading in goods and commodities. The assessee filed return of income electronically on 29.09.2013 declaring total income _ at Rs.35,99,660/-. The return of income filed by the assessee was selected for scrutiny and statutory notices under the Act were issued and complied with. During scrutiny proceedings, the Assessing Officer noted that partner’s capital in the firm was only to the extent of Rs.1,00,000/- and the assessee borrowed interest bearing funds and advanceed those funds on interest, however part of the loans given were interest free. At the year end i.e. 31.03.2013 the borrowed fund stood at Rs.832.74 crores and interest paid was of Rs.107.24 crores. Against which the assessee has shown balance outstanding of the advances given at Rs.828.04 crores and shown interest received during the year at Rs.99.47 crores. The Assessing Officer accordingly observed that assessee incurred losses in the business of advancing loans. The Assessing Officer analyzed party- wise interest paid in respect of funds borrowed and interest earned in respect of loans advanced. The Assessing Officer has mentioned that assessee has paid interest on borrowed funds in the range of 10.10% to 15.10%, whereas, the interest received was almost same but in some cases it was even lower and in also few cases interest free funds have been advanced by the assessee. Accordingly, the Assessing Officer issued show cause to the assessee as why the interest may not be disallowed out of the interest paid on the borrowed funds. It was submitted by the assessee that it had advanced interest free loans to six entities and therefore, the assessee himself had disallowed interest of Rs.7,70,05,688/- which was worked out on notional basis. A chart of such disallowance by the assessee is reproduced as under: Sr. No. |Name of the Party Balance as on 31" |Interest income 03-2013 worked out at the rate recovered per month 1 Amish Infrastructure Put. Ltd. 29,69, 15,000 3,64,27,965 2 Keystone Corporate Solutions Put. Ltd. 12,50,00,000 1,53, 74,417 3 Moonscape Facility Put. Ltd. 37,07,50,000 4,56,00,523 4 Proprity Construction Put. Ltd. 1,20,000 14,787 5 Aplex Power Put. Ltd. 3,00,000 26,463 6 Piramal Texturising Put. Ltd. 4,00,000 37,939 7 PHL Holdings Put. Ltd. -2,04, 76,406 (interest free unsecured loan availed on which interest expense has been computed) Total 79,34,85,000 7,70,05,688
3.1 The Assessing Officer however rejected the contention of the assessee and restricted the interest payment up to the 11% and excess amounting to Rs.12,30,46,063/- was disallowed invoking section 36(1)(iii) of the Act.
4. On further appeal, the Ld. CIT(A) deleted the addition observing as under:
“7.1 During, the appellate proceedings, the appellant has given the details of unsecured