Back


2021 Supreme(Online)(ITAT) 6960

INCOME TAX APPELLATE TRIBUNAL, SURAT BENCH, SURAT BEFORE SHRI PAWAN SINGH, JUDICIAL MEMBER AND Dr. ARJUN LAL SAINI, ACCOUNTANT MEMBER (Virtual Hearing)
I.T.(SS)A’s No.14,15,16/AHD/2016, ITA’s No.1302,1303& 3032/AHD/2016 Assessment Years: 2007-08, 09-10, 10-11; 2011-12,12-13& 2013-14 N.R.Agarwal Industries Ltd., Vs The ACIT/DCIT, Circle-3, Plot No.169 to 169, Phase No.1, Surat.
GIDC, Vapi.
[PAN: AAACN 7721 N]
अपीलाथ(cid:334) / Appellant (cid:366)(cid:529)थ(cid:334)/Respondent आ.अ.सं./I.T.(SS).A’s No. 46,47,48,49,1526 & 1527/Ahd/2016 िनधा(cid:330)रणवष(cid:330)/Assessment Years: 2007-08 to 2012-13 The ACIT/DCIT, Circle-3, Surat. Vs N.R.Agarwal Industries Ltd., Plot No.169 to 169, Phase No.1, GIDC, Vapi.
[PAN: AAACN 7721 N]
अपीलाथ(cid:334) / Appellant (cid:366)(cid:529)थ(cid:334)/Respondent Cross Objection’s No:41& 42/Ahd/2016 and 04/Ahd/2016 (Arising out of IT(SS)A’s No.46& 47/Ahd/2016 and ITA No.3032/Ahd/2016)
िनधा(cid:330)रणवष(cid:330)/Assessment Years: 2007-08, 08-09 &2013-14 The ACIT/DCIT, Circle-3, Surat. Vs N.R.Agarwal Industries Ltd., Plot No.169 to 169, Phase No.1, GIDC, Vapi.
[PAN: AAACN 7721 N]
अपीलाथ(cid:334) / Appellant (cid:366)(cid:529)थ(cid:334)/Respondent िनधा१ौरतीकीओरसे /Assessee by Shri SaurabhSoparkar Senior Advocate with Ms Urvashi Shodhan Advocate, Sh. Nitin Gheewala&Pareen Shah– CA राज(cid:738)कीओरसे/Revenue by Shri Ritesh Mishra – CIT-DR सुनवाई की तारीख/ Date of hearing: 08.04.2021 उद्घोषणाकीतारीख/Pronouncement on: 05.07.2021 आदेश /
ORDER
PER PAWAN SINGH, JUDICIAL MEMEBER:
1. This group of fifteen appeals, including cross appeals and cross objections, are directed against the order of learned Commissioner of income tax (Appeals), Surat, hereinafter referred as “ld. CIT(A)” for assessment years (AYs) 2007-08 to 2013-14. Out of which five appeals by assessee for AYs 2007-08, 2009-10 to 2012-13 being ITA No.(s) 14, 15, 16, 1302 & 1303/Ahd/2016 and seven appeals by revenue being ITA (s) No. 46,47,48,49,1526 & 1527/Ahd/2016 for AYs 2007-08 to 2012-13 & ITA No. 3032/Ahd/2017 for AY 2013-14,further the assessee also filed its Cross Objections (CO) in appeals filed by Revenue in AYs No. 2007-08, 2008-09 & 2013-14 being C.O. No. 41&42/Ahd/2016 & 4/Ahd/2017. The ld. CIT(A) passed consolidated order dated 27.11.2015 for AY 2007-08 to 2010-11. However, for remaining years the ld. CIT(A) passed separate orders.
2. In appeals for AY 2007-08, 2009-10 to 2013-1 and in CO for AY 2008-09 the assessee vide additional grounds of appeal filed on 14.12.2020, has raised additional grounds of appeal that assessing officer and ld. CIT(A) erred in not allowing the deduction of education cess and higher education cess as allowable expenditure under section 40(a)(ii). The additional grounds of appeal is raised on the basis of decision of Rajasthan High Court in CIT Vs Chambal Fertilizer and Chemicals Ltd (Tax Appeal No. 52/2018) and Circular of Central Board of Direct Taxes (CBDT) dated 18th May 1967 vide F.No.91/58/66-ITJ(19).
3. In all appeal, and cross appeals, the parties have raised certain common grounds of appeal, facts in all years are almost similar except variation of figures of additions/ disallowance on various claims, thus, with the consent of the parties all the appeals were clubbed, heard and are decided by common order to avoid the conflicting decisions /findings on various.
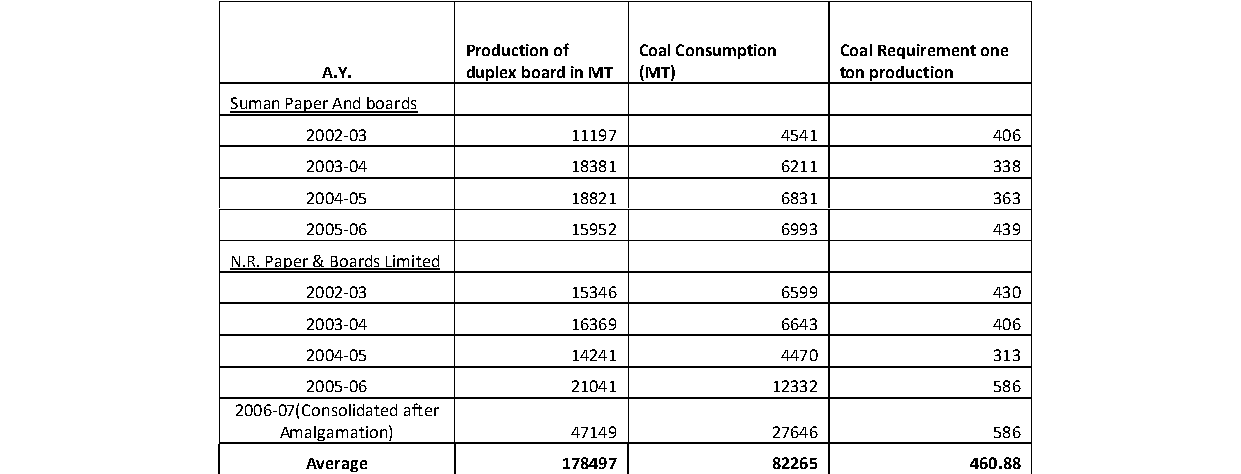
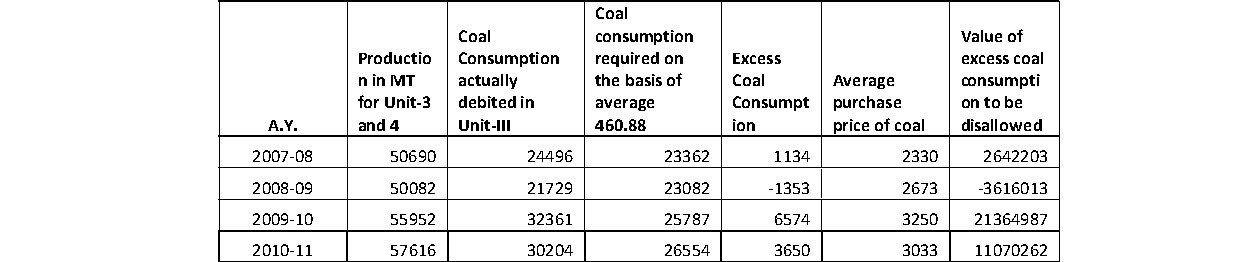
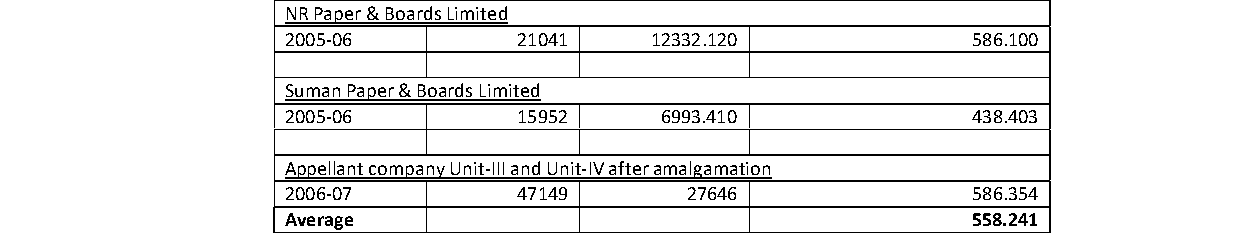
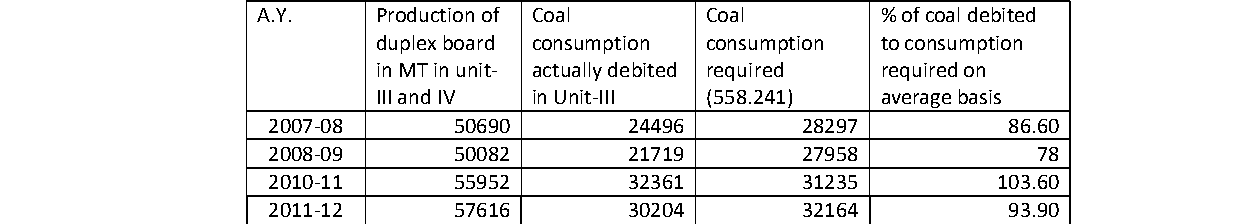
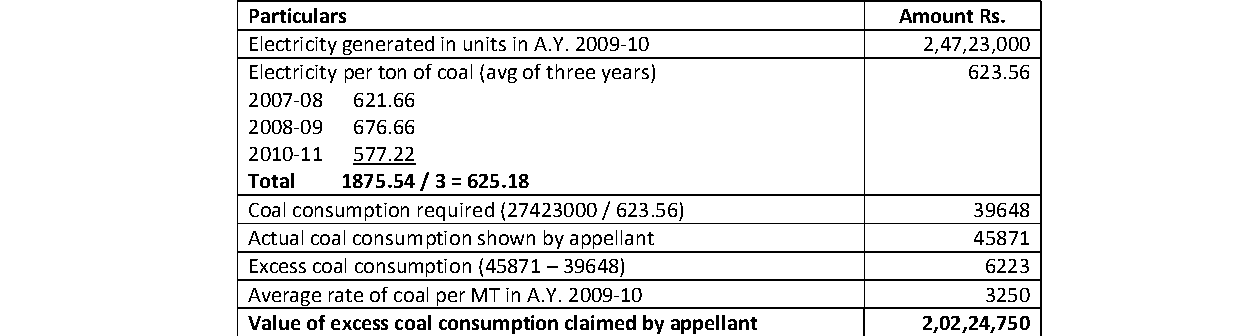
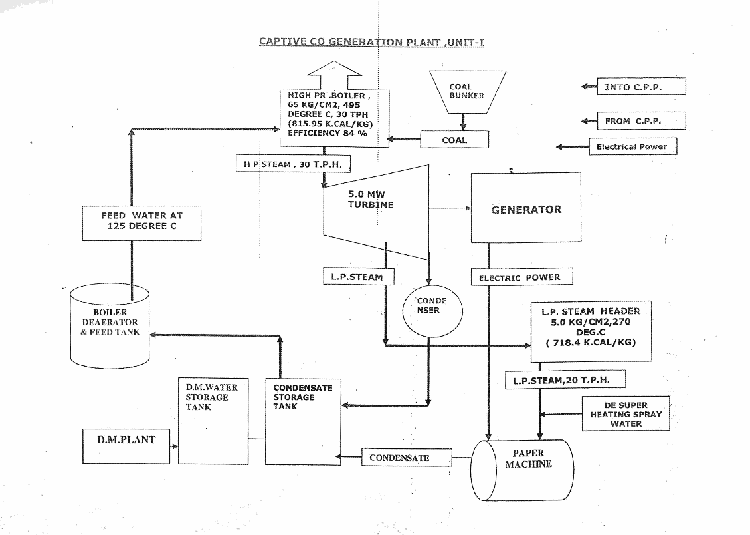
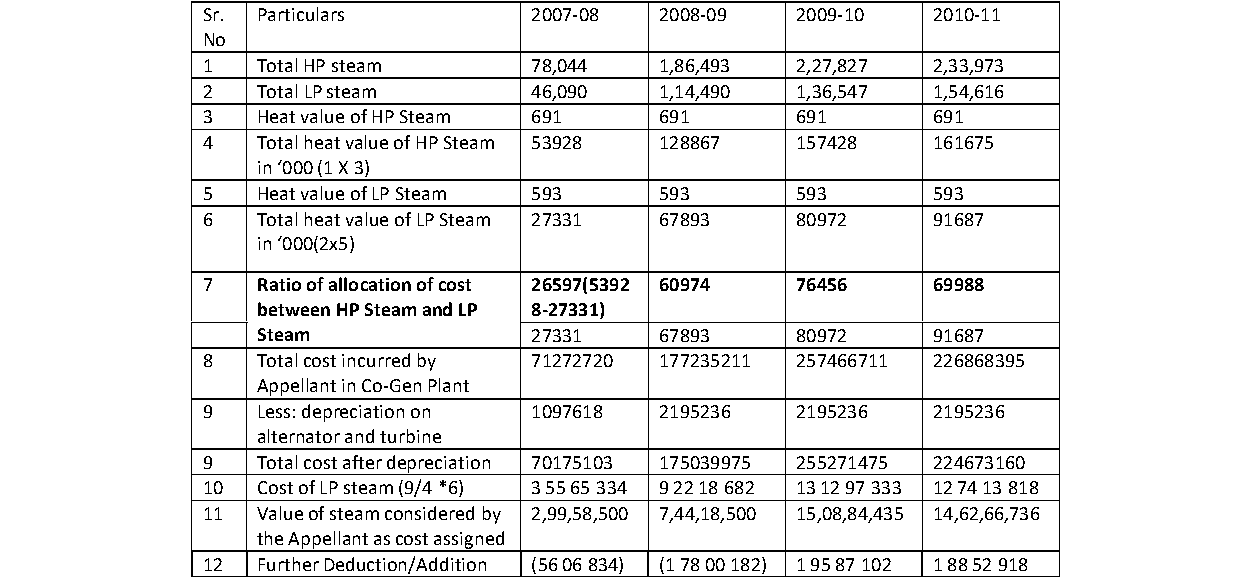
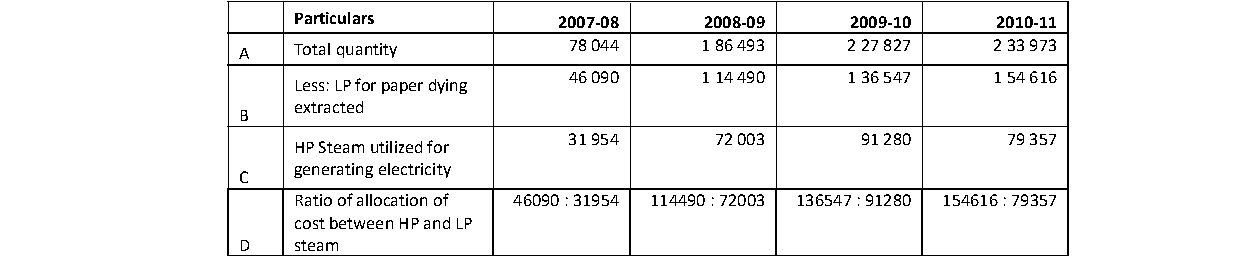
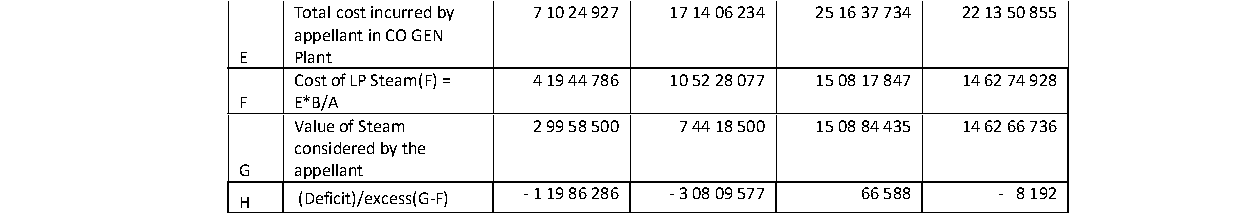
4. Brief facts of the cases as extracted from the orders of the lower authorities are that the assessee is a Public Limited Company, engaged in the business of manufacturing, paper, craft paper, duplex boards and news prints. The assessee also has two captive power generation plants of three Megawatts and five Megawatts of its own use. The assessee generating electricity from its captive power plants by generation of steam. Such generated steam is also used for industrial purpose. In the power plant of five Megawatts (power plant-1), the assessee was claiming benefits of deduction of section 80IA and on other power plant the assessee claimed depreciation @ 80%. During the period relevant to the AY 2008-09, Suman Paper & Board and NR Paper & Board, the group companies of the assessee were amalgamated with the assessee and become third power plant (Unit-III). A search action under section 132 of Income tax Act (Act) was carried out on the assessee group on 16.07.2009. In the search certain discriminatory documents and evidences were allegedly recovered which were inventorised by the search party. Consequent upon the search action, notices under section 153A was served on the assessee. The assessee in response to such notices filed its return of income and assessment order under section 143(3) r.w.s 153A of the Act was passed for A.Y. 2007-08 to 2010-11 on 30.12.2011. The assessing officer made various additions/ disallowances in the assessment orders. Aggrieved by the additions, the assessee filed appeal before CIT(A). The Appeals of the assessee was decided by Ld. CIT(A) vide its appellate order dated 12.06.2012 (First round). The ld. CIT(A) granted part relief to the assessee on various issues. However, during the hearing the ld. CIT(A) issued notice for enhancement on account of Coal consumption in all Units and enhance income by re-computing the working of coal consumption in different Units and also revise the cost allocation of High Power (HP) steam and Low Power (LP) steam.
5. Further aggrieved, the assessee as well as revenue filed appeal before Tribunal. The Tribunal vide order dated 26.07.2013