
 Back


IN THE INCOME TAX APPELLATE TRIBUNAL BENGALURU BENCH 'B', BENGALURU BEFORE SHRI. A. K. GARODIA, ACCOUNTANT MEMBER AND SHRI. LALIET KUMAR, JUDICIAL MEMBER I.T.A Nos.210 to 216/Bang/2013 (Assessment Years : 2001-02 to 2007-08)
Webex Communications India P. Ltd, Divyashree Chambers, B-Wing, No.11, O Shaughnessey Road, Off Langford Road, Bengaluru 560025 .. Appellant PAN : AABCC0256A v.
Deputy Commissioner of Income-tax, Circle – 12(5), Bengaluru .. Respondent Assessee by : Shri. Rajan Vora, CA Revenue by : Smt. Neera Malhotra, CIT &
Shri. K. R. Nayayana, JCIT Heard on : 19.03.2019 Pronounced on : 27.03.2019
ORDER
PER BENCH :
These are seven appeals arising out of separate orders of the CIT (A), dt.27.11.2012, for AYs.2001-02, 2003-04, 2005-06, and orders dt.30.11.2012, for AYs.2002-03, 2004-05, 2006-07 and 2007-08, respectively.
02. The common grounds of appeal raised by the assessee, are as under :
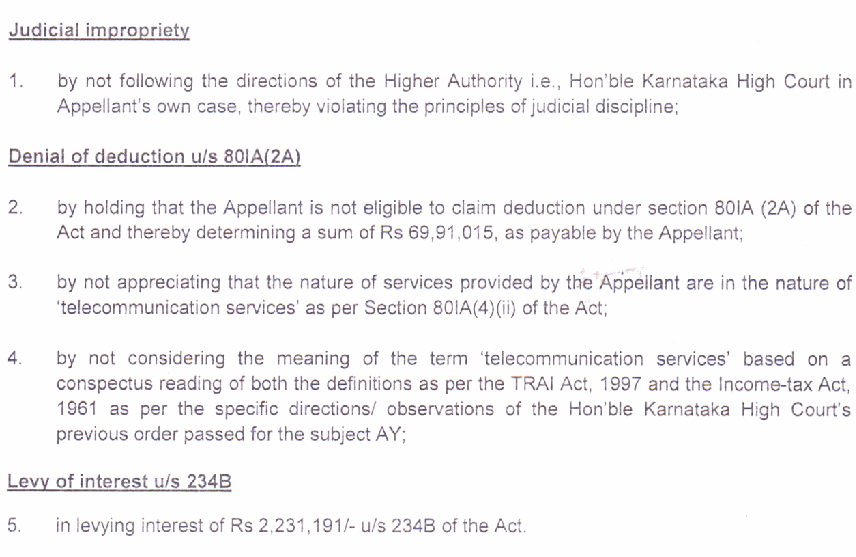
The assessee has also raised additional grounds as under :
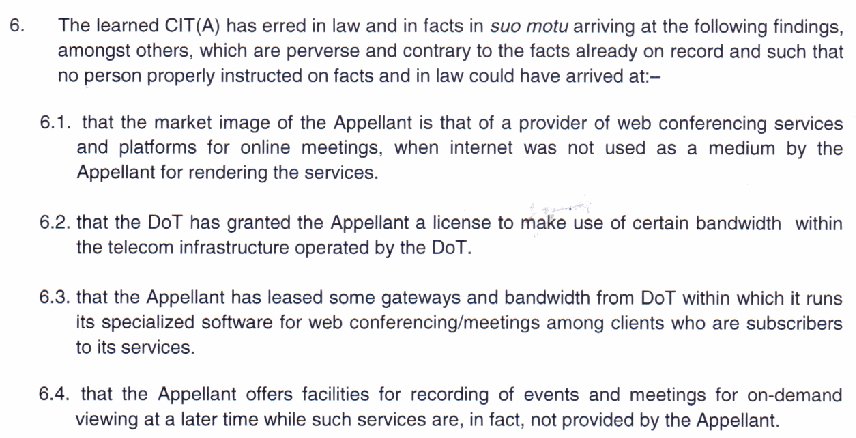
02. The Ld. AR had submitted before us that this is the second round of litigation and has submitted that the Honourable High Court vide its order in I.T.A. No.2775/2005, dated 12.04.2010, in para 9 to 11, reproduced hereinbelow, had remanded the matter back to the AO for deciding this issue in terms of the observation made by the Honourable High Court :
9. Further the question as to whether the services rendered by the assessee comes within the definition of ‘telecommunication service' has also not been taken into consideration in its proper perspective and it has been answered that the assessee's service does not come within the scope of telecommunication service. Though the Income Tax Act does not define as to what telecommunication service, nevertheless, it would be appropriate to re(cid:1)er to the definition of teleco(cid:2)(cid:2)(cid:3)(cid:4)(cid:5)(cid:6)(cid:7)(cid:8)(cid:5)(cid:9)(cid:4)(cid:10) (cid:11)(cid:12)(cid:13)(cid:14)(cid:5)(cid:6)(cid:12)(cid:10) (cid:7)(cid:11)(cid:10) (cid:6)(cid:9)(cid:4)(cid:8)(cid:7)(cid:5)(cid:4)(cid:12)(cid:15) in section 2(k) of the Telecom Regulatory Authority of India Act, 1997. As the said Act directly deals with telecommunication and other such allied matters, the said definition can be referred to for the purpose of interpreting telecommunication service within the meaning of section 80-IA(4)(il) of the Act. The definition of telecommunication services under the said Act, reads as follows:
"Section 2(k) "telecommunication service" means service of any description (including electronic mail, voice mail, data services, audit text services, video text services, radio paging and cellular mobile telephone services) which is made available to users by means of any transmission or reception of signs, signals, writing, images and sounds or intelligence of any nature, by wire, radio, visual or other electro- magnetic means but shall not include broadcasting services.
Provided that the central government may notify other service to be telecommunication service including broad casting services."
10. It is necessary to note that while the (cid:15)(cid:12)(cid:1)(cid:5)(cid:4)(cid:5)(cid:8)(cid:5)(cid:9)(cid:4) of telecommunication service under sec.2(k) of Telecom Regulatory Authority of India Act, 1997 is an exhaustive definition, it expressly includes electronic voice mail, data service, audit text services video text services also. Under sec.80-IA(4)(ji) of the Income Tax Act, the definition is an inclusive definition without specifying the aforesaid services. Therefore on a conspectus reading of both the definition under Telecom Regulatory Authority of India Act as well as sec.80-IA(4)(ii) of the Income Tax Act, the question as to whether the service rendered by the appellant comes within the (cid:1)
meaning of telecommunication service has to be determined by taking into consideration the nature of the service rendered by the assessee.
11. Therefore, we deem it proper to remand the matter to the Assessing Officer to consider the entire issue in the light of the aforesaid observation and give a finding as to whether the appellant-assessee is an undertaking within the meaning of section 80-IA(4)(ii) of the Act and also to decide as to whether the nature of service rendered by the assessee comes within the meaning of telecommunication service.
It was the contention of the ld. AR that despite the specific direction issued by the Honourable High Court neither the AO nor the CIT (A) have decided the specific issue which was remanded by High Court to the AO. The ld. AR has drawn our specific attention to para 9, 9.1, 9.2, 10,11, 12, 13, 19, 20 & 22 o


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


