Back


2025 Supreme(Online)(ITAT) 6781
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
Smt. Beena Pillai, J, Smt. Renu Jauhri, ACJ
Skechers Sarl – Appellant
Versus
The Assistant Commissioner of Income Tax- 4(2)(1) – Respondent
I.T.A. No. 2028/Mum/2025
For the Appellants/Petitioners: Shri Nikhil Tiwari
For the Respondents: Shri Krishna Kumar SR. D.R.
Identification of the nature of income as FTS or business income is crucial under the Income Tax Act and DTAA, emphasizing the necessity for specific service definitions and procedural compliance in tax assessments.
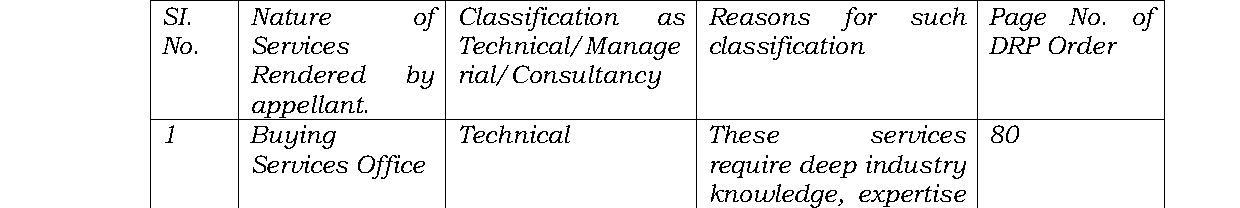
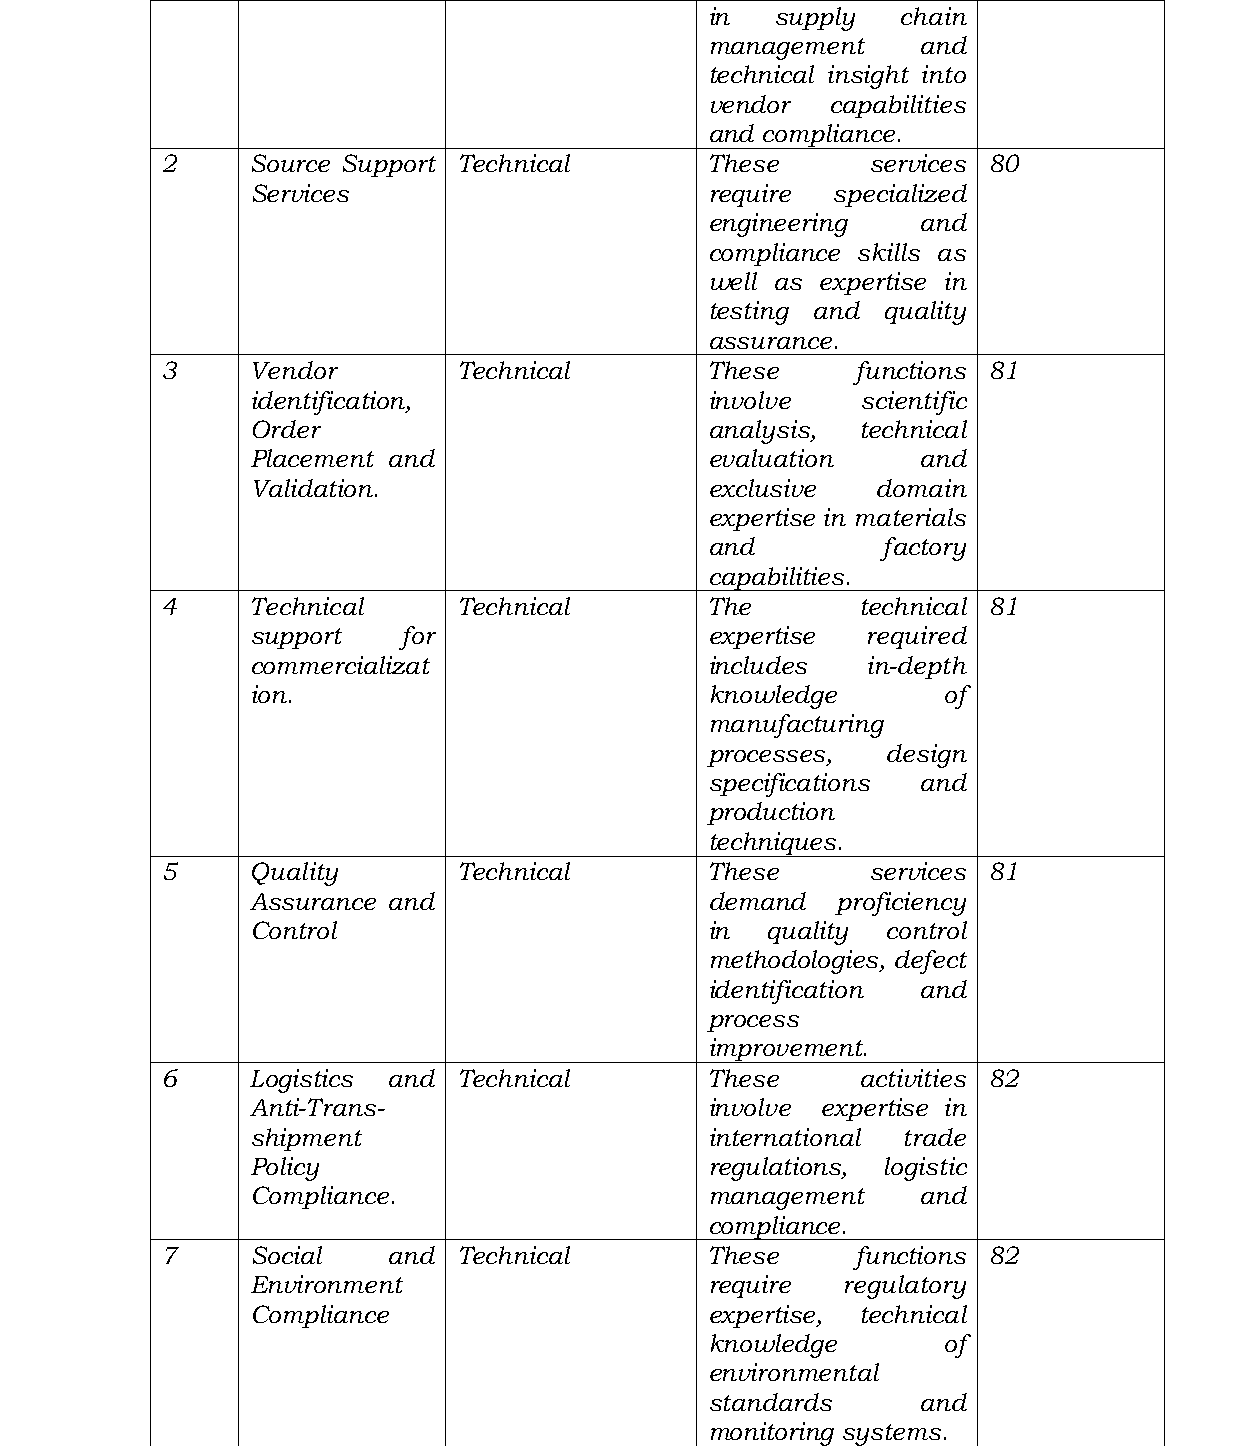
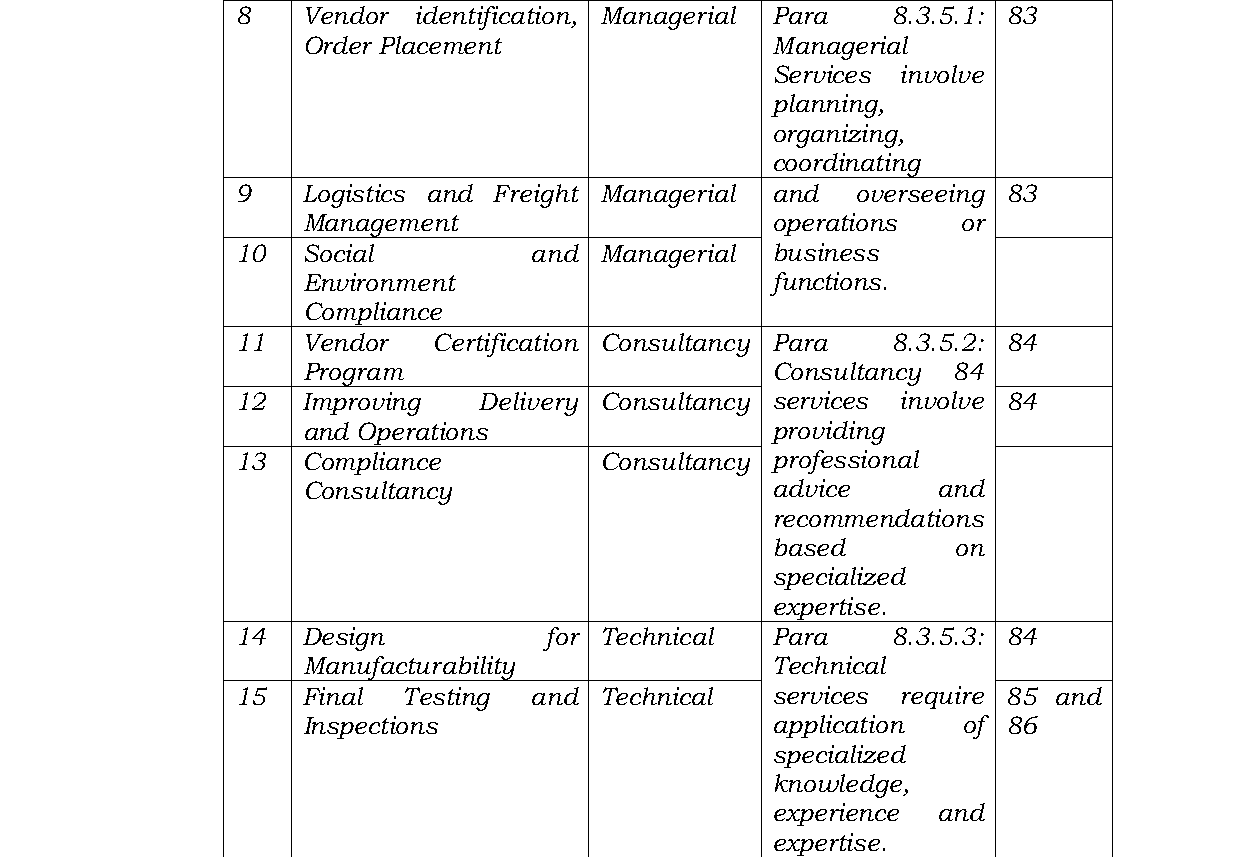
Headnote:(A) Income Tax Act, 1961 - Sections 143(3), 144C(13), 9(1)(i), and 9(1)(vii) - Double Taxation Avoidance Agreement between India and the Swiss Confederation - Classification of income from buying commission - The court emphasized that the services rendered did not constitute 'managerial', 'technical', or 'consultancy' services, thus not qualifying as FTS under Article 12 of the DTAA. The DRP's re-characterization was challenged on the grounds of jurisdiction and procedural compliance. (Paras 7 and 8)
(B) The powers of the Dispute Resolution Panel (DRP) - The DRP's jurisdiction includes the authority to enhance proposed assessments if proper opportunity for rebuttal is given. The amendment of Section 144C(8) clarifies the DRP's powers. (Paras 8.1 to 8.12)
| Table of Content |
|---|
| 1. nature of appeal and assessment details (Para 1 , 2) |
| 2. observations on services rendered by assessee (Para 5 , 6) |
| 3. conclusions on nature of services and tax obligations (Para 7 , 8) |
| 4. final adjudication of appeal and counsel arguments (Para 9 , 10) |
ORDER
Per: Smt. Beena Pillai, J.M.:
The present appeal filed by the assessee arises out of final assessment order dated 15/01/2025 passed by ACIT 4(2)(1), Mumbai for assessment year 2022-23 on following grounds of appeal:
“ On being aggrieved by the order dated 15 January 2025 passed by the Assistant Commissioner of Income Tax, International Tax Circle 4(2)(1), Mumbai ('herein referred to as the Ld. AO') under section 143(3) read with section 144C(13) of the Income-tax Act, 1961 ('the Act'), the present appeal is preferred on the following grounds, which it is prayed may be considered without prejudice to one another
On the facts and circumstances of the case and in law, the Ld. AO and the Hon'ble Dispute Resolution Panel-2, Mumbai ('DRP'):
General Ground:
1. erred in assessing the total income at INR 52,06,95,454 instead of income offered to tax as per Return of Income ('ROI') at INR 16,93,95,185, Final assessment order barred by limitation:
2. erred in not appreciating that the time limit prescribed under section 153 is the outer time limit for passing the final assessment order, and hence, the final assessment order dated 15 January 2025 is time barred and liable to be quashed; Addition of Buying Commission of INR 35,13,00,269:
3. erred in making addition in respect of Buying Agency Commission of INR 35,13,00,269 as Fees for Technical Services ('FTS') as per Article 12 of the Double Taxation Avoidance Agreement between India and the Swiss Confederation ('India-Swiss DTAA');
4. erred in holding that the services rendered by Skechers SARL are in the nature of 'managerial", technical' or 'consultancy' services as per Article 12 of India-Swiss DTAA;
5. ought to have held that the buying commission income constitutes business income as per the provisions of Article 7 of India-Swiss DTAA, and in the absence of any Permanent Establishment in India, it would not be chargeable to tax in India, and hence, not liable to tax in India, Levy of interest under section 234B of the Act
6. erred in levying interest of INR 1,19,85,816 under section 234B of the Act, Initiation of penalty proceedings under section 270A of the Act:
7. erred in initiating penalty proceedings under section 270A of the Act, without appreciating the fact that the Appellant has not misreported any income.
The Appellant craves leave to add, alter, omit or substitute any or all of the above grounds of appeal, at any time before or at the time of the appeal.”
2. The assessee raised following additional grounds challenging the powers of DRP in re-characterising the taxability of buying agency commission as FTS as against Business Income by the Ld.AO. The Ld.AR submitted that the assessee filed application dated 25/07/2025 for admission of additional ground that reads as under:
“With respect to the subject appellate proceedings, the Appellant respectfully submits the following additional grounds of appeal.
Based on the facts and circumstances of the case and in law, the Appellant has preferred an appeal before Your Honours against the final assessment order passed by the Assistant Commissioner of Income Tax, Int Tax Circle 4(2)(1), under section 143(3) read with section 144C(13) of the Income Tax Act, 1961 ('the Act'), dated 15 January 2025.
On the facts and in circumstances of the case and in law, the Ld. AO/ Hon'ble DRP Hon'ble DRP directions bad in law, hence final assessment order bad in law
8. erred in exceeding its jurisdiction provided under Section 144C of the Act by reviewing the issue on taxability of buying agency commission as FTS which has been already examined by the Ld. AO during assessment proceedings and thereby, this issue cannot be adjudicated again by Hon'ble DRP as it has been already accepted by Ld. A