Back


2025 Supreme(Online)(ITAT) 6864
INCOME TAX APPELLATE TRIBUNAL (GUWAHATI BENCH)
RAJESH KUMAR, AM, MANMOHAN DAS, JM
Shri Likha Saaya – Appellant
Versus
ITO, Ward-North, Lakhimpur – Respondent
ITA Nos.49 & 50/GTY/2021
For the Appellants/Petitioners: Sarala Agarwal
For the Respondents: Shri Kausik Ray
The Tribunal ruled that cash deposits totaling Rs.1,75,00,000/- were not to be treated as undisclosed income because they originated from the assessee's own withdrawals, supporting the exemption under Section 10(26).
Headnote:(A) Income Tax Act, 1961 - Section 10(26) - Assessments under scrutiny - Appeals filed against orders of CIT(A) - Cash deposits treated as income from undisclosed sources - Assessee, a member of Scheduled Tribe, claimed exemption for transport income - Assessing Officer made additions on deposits not explained, totaling Rs.1,75,00,000/- - CIT(A) upheld the additions - Tribunal found that the revenue failed to provide substantive evidence proving the deposits were unexplained - The Tribunal ruled that since the cash deposits were from withdrawals, they were not income - Appeal allowed - Exemption under Section 10(26) reaffirmed. (Paras 4, 10, 19, 21)
(B) Jurisdiction under Section 263 - The exercise of revisionary jurisdiction by CIT is barred when appeals are pending - The Tribunal found the revisionary order under Section 263 invalid due to lack of jurisdiction and pending appeal before CIT(A). (Paras 14, 20)
| Table of Content |
|---|
| 1. summary of procedural context (Para 1 , 2 , 3 , 4) |
| 2. arguments regarding cash deposits (Para 6 , 8 , 9) |
| 3. court observations on cash deposit sources (Para 10 , 12 , 21) |
| 4. legal principles regarding section 263 (Para 13 , 15 , 19) |
| 5. final decision on appeals (Para 22) |
ORDER
PER RAJESH KUMAR, AM
Both the appeals filed by the assessee are against the separate orders of ld. Commissioner of Income Tax (Appeals), Guwahati-1 dated 30.12.2019 in Appeal No.NLP-1/2013-14/346 & Appeal No.NLP-9/2014- 15/347 passed for Assessment Years 2010-2011 &2011-12, respectively.
ITA No.49/GTY/2021: Asst.Year-2010-2011
2. Ground No.1 of the assessee’s appeal is general in nature and hence, does not require separate adjudication.
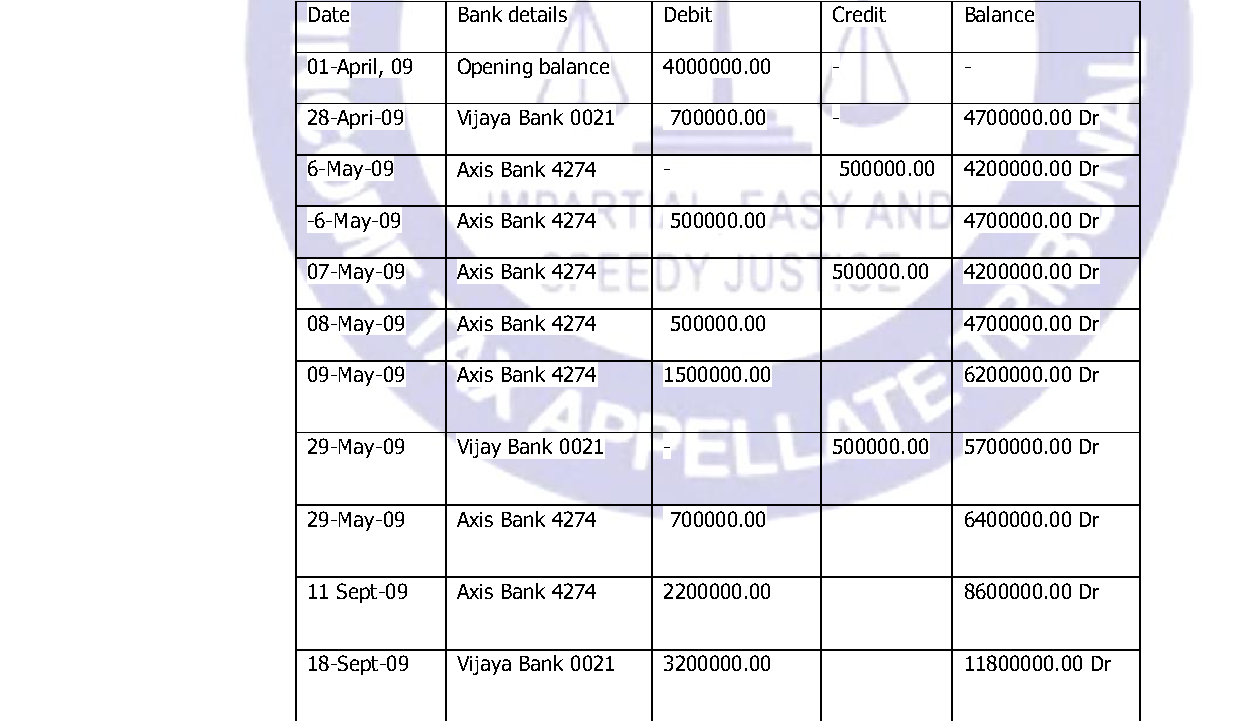
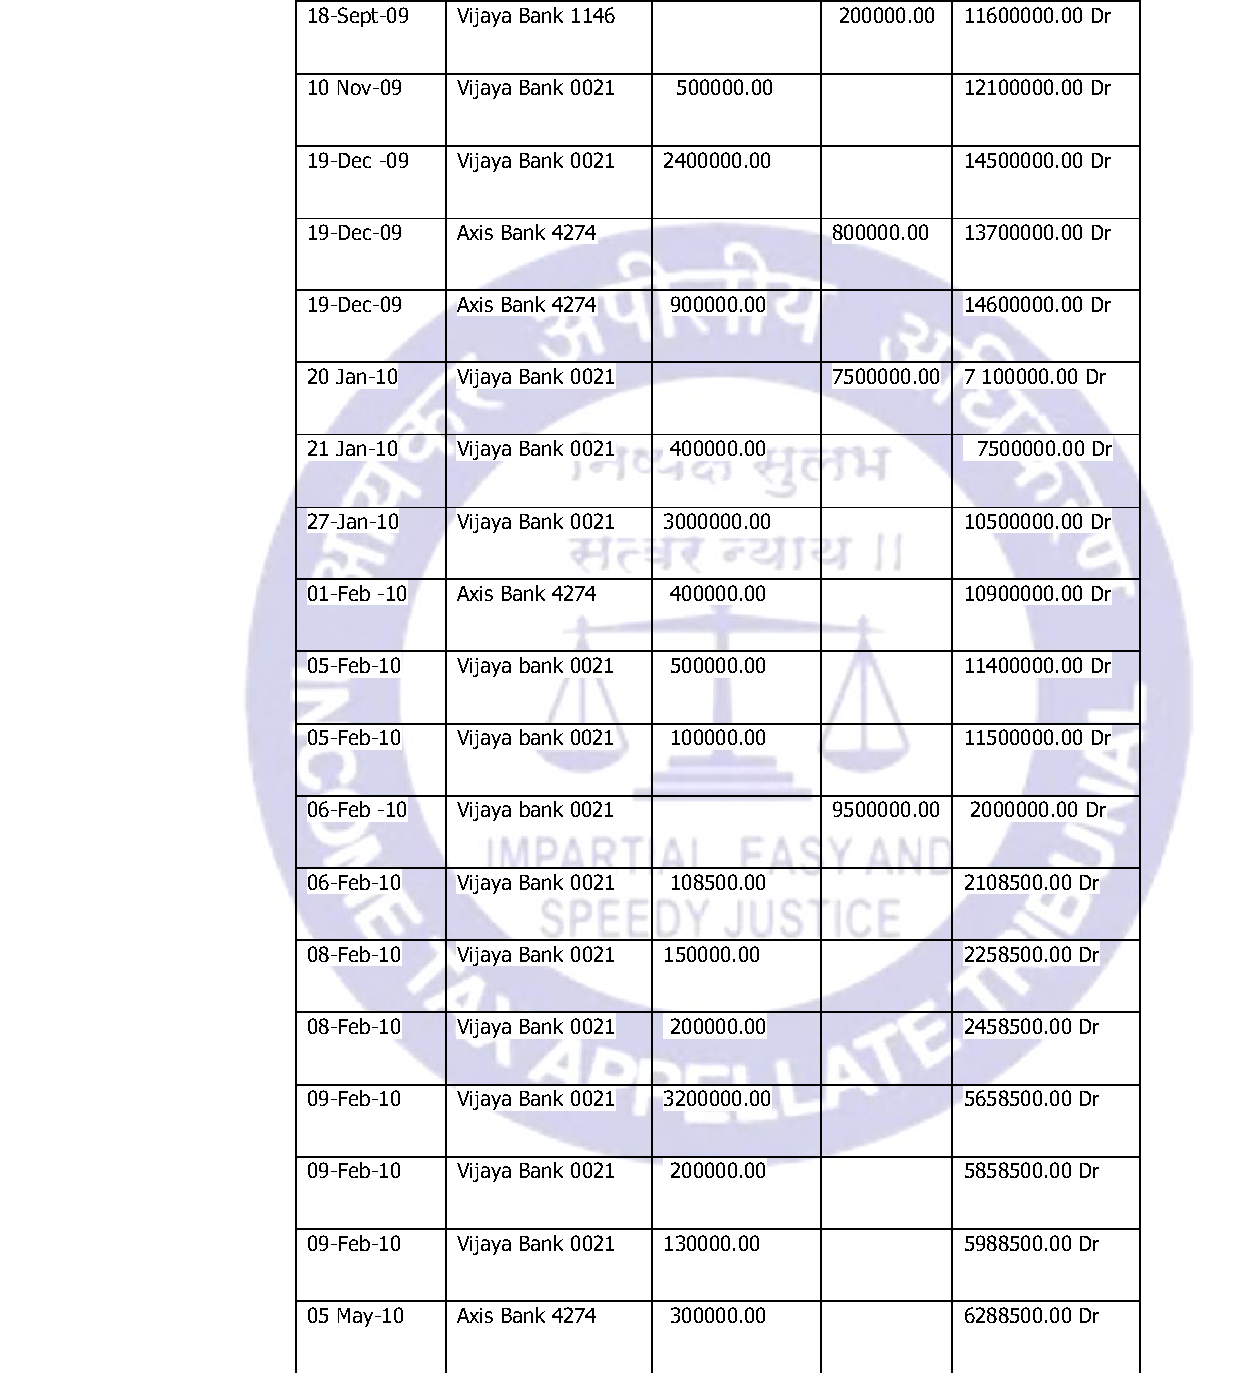
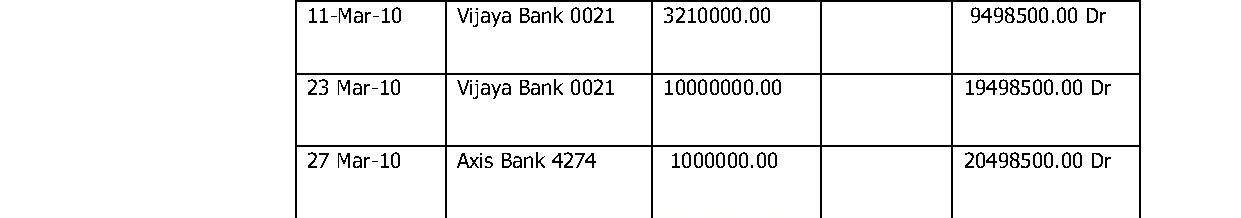
3. The issue raised in Ground No.2 & 3 of appeal is against the action of the ld. CIT(A) in confirming the addition of Rs.1,75,00,000/- as made by the Assessing Officer on account of cash deposits in Vijaya Bank treating the same as income from undisclosed sources.
4. The facts in brief are that the assessee is a Member of Scheduled Tribe of Arunachal Pradesh and is engaged in the business of contract carriage (Transportation) in the state of Arunachal Pradesh providing transport services the Director of Supply and Transport, Nagharlagun, Govt of Arunachal Pradesh during the year. The assessee is a resident of Arunachal Pradesh and filed the return of income on 6.4.2011 showing total income at Nil by claiming income to be exempt u/s.10(26) of the Act. The return was processed u/s.143(1) of the Act on 7.2.2012. Thereafter, the case of the assessee was selected for scrutiny through CASS followed by issuance of notices u/s.143(2) and 142(1) of the Act along with questionnaire, which were duly served upon the assessee. Ld. AR of the assessee complied with the said notices by appearing personally before the Assessing Officer and submitting various documents such as Trade Licenses, ST certificate, photocopies of TDS certificates, Bank statements of Vijaya Bank, Itanagar Branch in respect of A/C No.880100300001451 and Axis Bank A/c No.015010100564274. Ld. AO further directed the assessee to furnish the details/evidences in support of cash transactions explaining the source. Thereafter, there was no compliance on couple of occasions on the ground there had been change of address of the assessee since the date of filing of the return of income. Accordingly, the Assessing Officer was informed the correct address of the assessee. Thereafter, notices were issued again but there was no compliance and the AO at page 2 para 4 noted that the assessee being a carriage contractor had received contract receipts from the Transport Department of Government of Arunachal Pradesh of Rs.13,44,00,000/- as is apparent from the TDS certificate. The Assessing Officer also noted that the income of the assessee is exempt from tax on the ground of being a Member of Scheduled Tribe of Arunachal Pradesh. The Assessing Officer also estimated the transport income out of total transport contract receipts, at Rs.1,34,40,000/- after deducting all expenses by applying flat rate of 10%, which had been allowed to be exempt u/s.10(26) of the Act. The AO also observed from the bank statement that there was cash deposits on different dates in Vijaya Bank A/c No.1000021 aggregating to Rs.1,75,00,000/-. The AO also found from the perusal of bank account with Axis Bank A/c No.015010100564274 that the assessee has deposited Rs.18.00 lakhs during the year. Similarly, the AO observed from the Vijaya Bank account that there were credits of interest aggregating to Rs. 7,12,168/- on 3 FDRs. The AO noted that there was credit of Rs.749/- in ICICI Bank Account No.032201500276 in respect of interest. Consequently, the AO made addition in respect of all these deposits to the income of the assessee vide order dated 20.3.2013 passed u/s.144 of the Act.
5. Ld. CIT(A) in the appellate proceedings also dismissed the appeal of the assessee by passing a very detailed and compreh