Back


2025 Supreme(Online)(ITAT) 6921
INCOME TAX APPELLATE TRIBUNAL (PUNE BENCH)
Shri R.K. Panda, VP, Ms. Astha Chandra, J
Wockhardt Limited – Appellant
Versus
Assistant Commissioner of Income Tax – Respondent
Income Tax Appeal No: ITA Nos.837, 835 & 836/PUN/2025
For the Appellants/Petitioners: Shri Manthan Shah
For the Respondents: Shri Amit Bobde
Expenditures contravening public policy or statutory regulations, such as illicit benefits to medical professionals, are inadmissible under tax law, and consolidated satisfaction notes across assessment years are invalid.
Headnote:(A) Income Tax Act, 1961 - Section 132, 153C and Explanation 1 to Section 37(1) - Medical Council of India Regulations - Disallowance of expenditure - Assessee's claims related to educational grants to a trust for organizing medical conferences were disallowed due to evidence indicating such grants were utilized for providing illegal freebies to medical practitioners, illustrating violations of the guidelines set forth by the Medical Council and subsequent CBDT Circular. The court emphasized expenditures that contravene public policy and statutory regulations are inadmissible in tax calculations. (Paras 1, 2, 16, and 20)
(B) Validity of proceedings - The consolidating nature of satisfaction notes for different assessment years was deemed improper, with precedents established by the Karnataka High Court leading to the quashment of the assessment proceedings. The court affirmed a clear separation of satisfaction must be maintained for each assessment year to uphold due process. (Paras 16 to 24)
Facts of the case:
The assessee, engaged in pharmaceuticals, faced scrutiny following a search revealing that funds granted were misused for incentivizing medical professionals, raising questions of legality and policy.
Findings of Court:
The court found the claims made for educational purposes reflected an intention to disguise illegitimate gifts and thus disallowed Rs.1,75,68,000 as non-deductible expenses.
Issues: Main issues involved included the legality of the satisfaction note process and assertion of grant misuse for providing illegal benefits to healthcare providers.
Ratio Decidendi: The court held that expenses representing violations of the law regarding medical ethics cannot be interpreted as legitimate deductible expenditures. Moreover, the necessity for each AY to have a separate satisfaction note was reaffirmed for lawful proceedings.
Result: Appeals partly allowed, assessment quashed for lack of proper legal framework in the satisfaction note.
| Table of Content |
|---|
| 1. claim of assessment based on search findings (Para 2) |
| 2. validity of satisfaction notes under section 153c (Para 3 , 4) |
| 3. legal argument on consolidated satisfaction notes (Para 6 , 7) |
| 4. historical context from case law for consolidated notes (Para 8 , 9) |
| 5. court's adherence to precedent on consolidated satisfaction notes (Para 10 , 12 , 14 , 15) |
| 6. final ruling quashing assessment due to procedural invalidity (Para 21 , 22) |
आदेश / ORDER
PER ASTHA CHANDRA, JM :
The above three captioned appeals filed by the assessee are directed against the separate order(s) all dated 27.01.2025 of the Ld. Commissioner of Income Tax (Appeals)-12, Pune [“CIT(A)”] pertaining to Assessment Years (“AYs”) 2016-17, 2017-18 and 2018-19. Since, the issue(s) involved are identical, these were heard together and are being disposed of by this common order.
ITA No. 837/PUN/2025, AY 2016-17
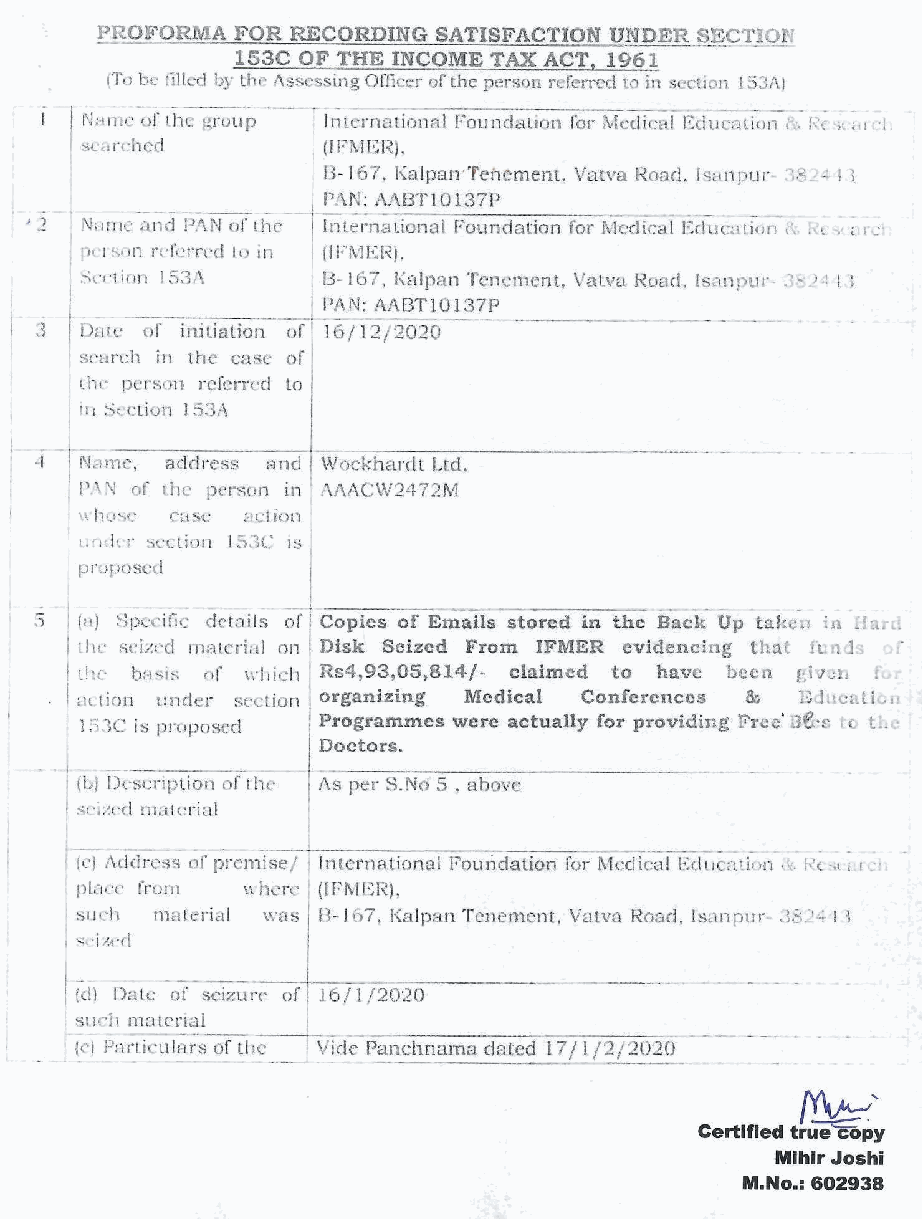
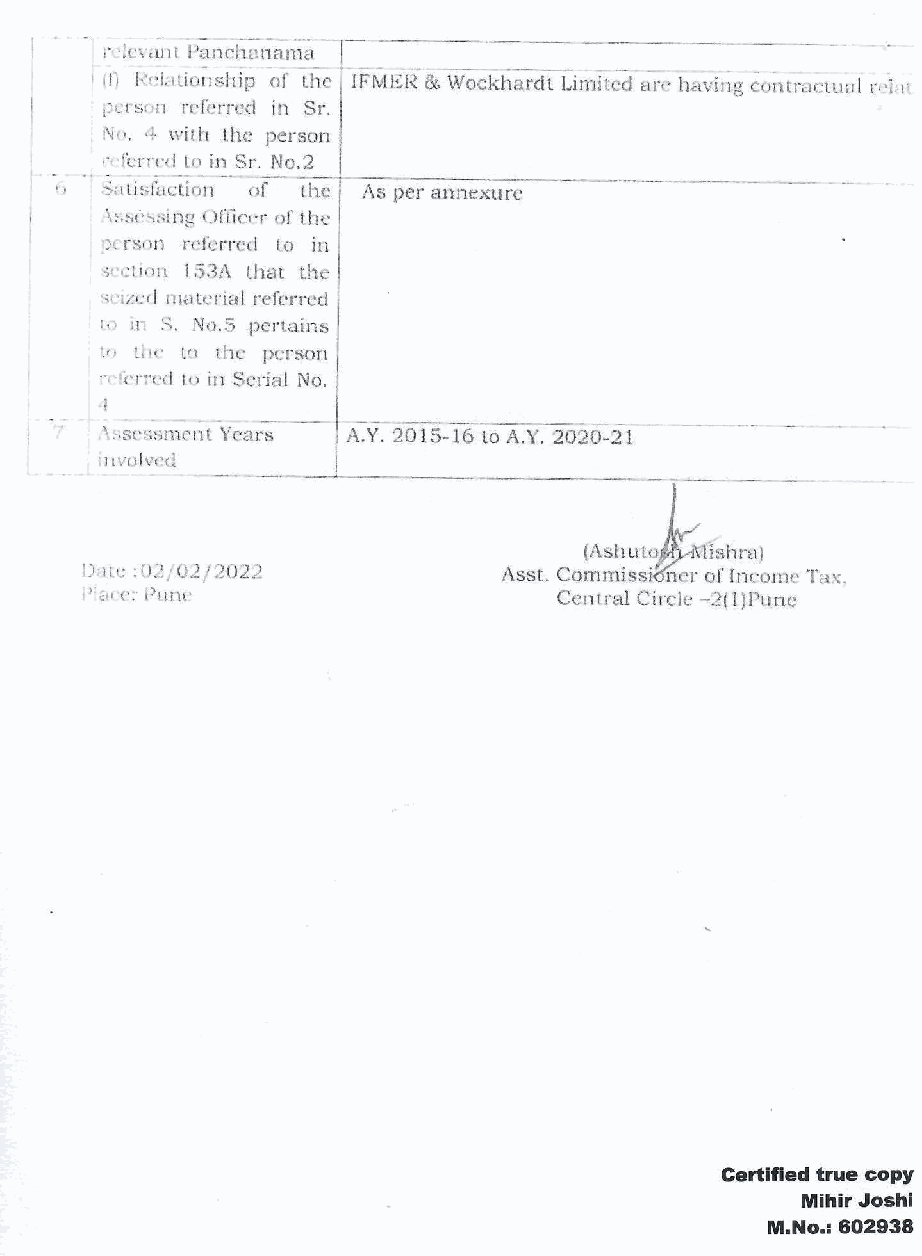
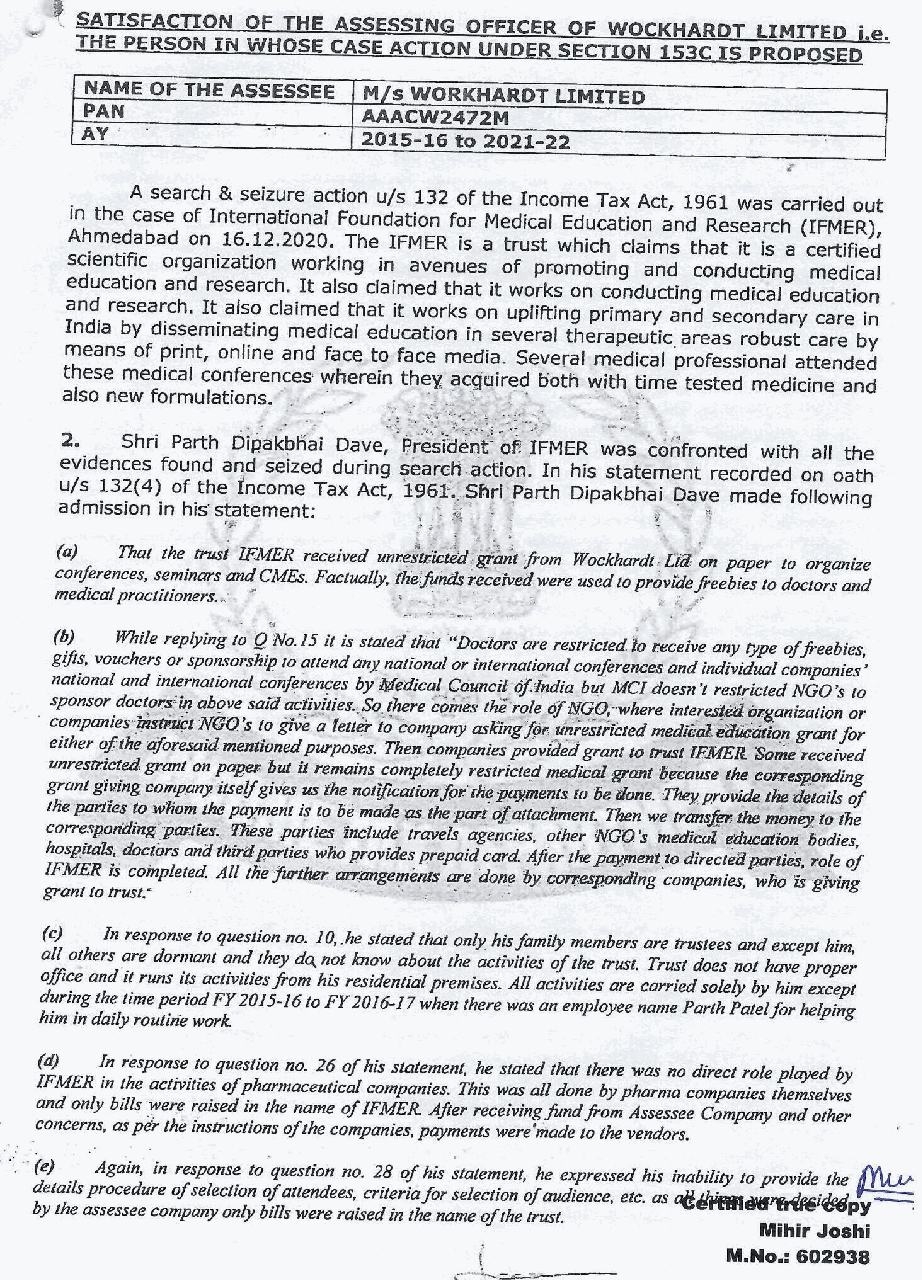
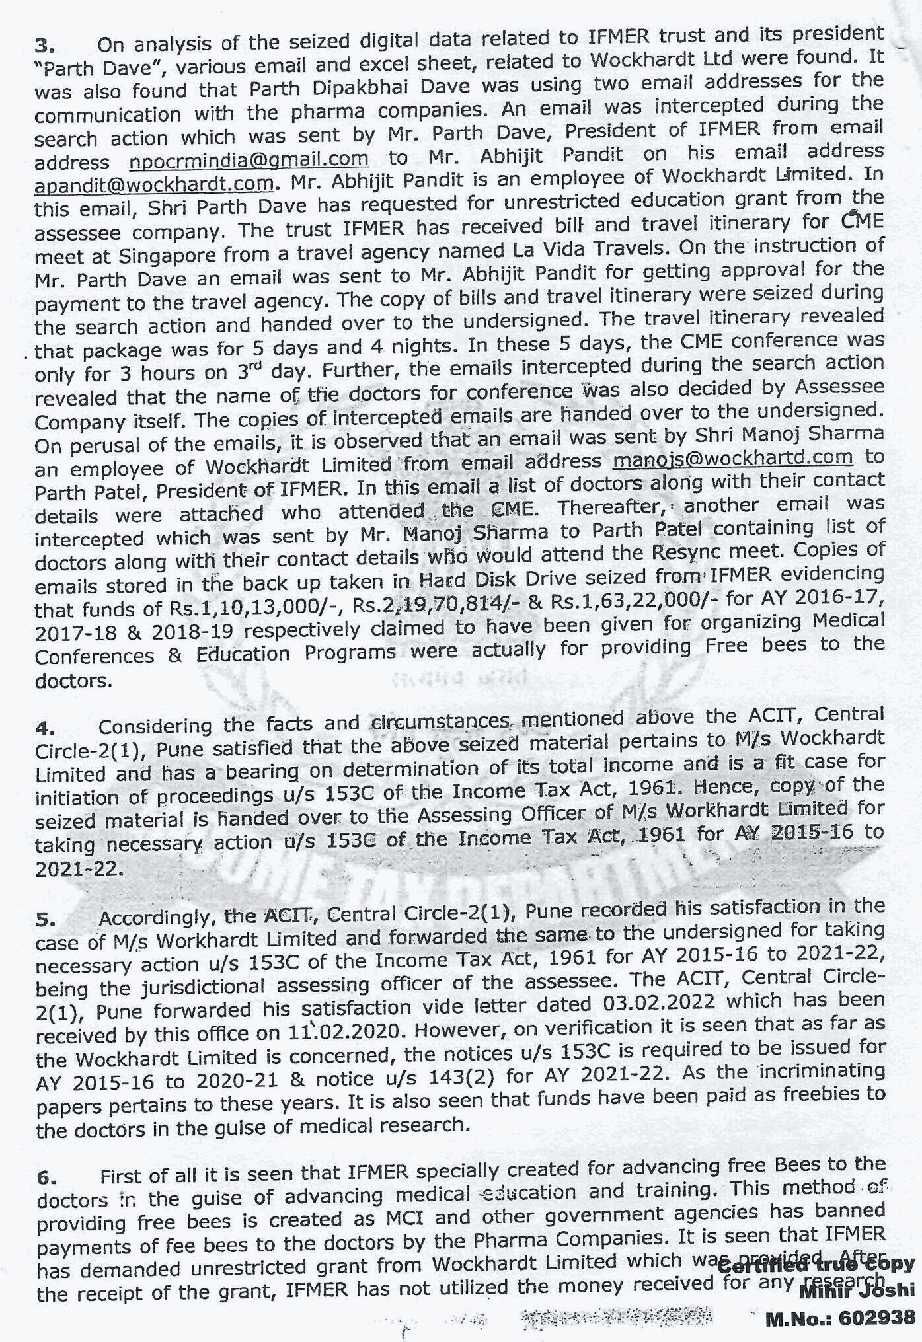
2. Briefly stated, the facts of the case are that the assessee is a company engaged in the business of manufacturing and trading of pharmaceutical products. A search and seizure action u/s 132 of the Income Tax Act, 1961 (the “Act”) was carried out on 16.12.2020 in the case of International Foundation for Medical Education and Research, Ahmedabad (“IFMER”). During the search action as per the statement of Shri Parth Dipakbhai Dave, President of IFMER recorded on oath u/s 132(4) of the Act on 16.12.2020 and evidences found and seized during the course of search action, Shri Parth Dipakbhai Dave, admitted that IFMER received unrestricted grant from Wockhardt Limited (the assessee in the instant case) in paper to organize conference, seminars and CME’s. Factually, the funds received were used to provide freebies to the doctors and medical practitioners. A satisfaction note by the Assessing Officer of IFMER in whose hands the material was seized was recorded on 02.02.2022 stating that the material was relevant to the case of Wockhardt Ltd., the assessee company and it was communicated to the then Assessing Officer of the assessee i.e. the DCIT, Circle-1, Aurangabad (“the Ld. AO-Aurangabad”). Pursuant thereto, the Ld. AO-Aurangabad recorded his satisfaction note in the case of the assessee on 23.03.2022. Consequently, notice u/s 153C of the Act was issued and served upon the assessee on 24.03.2022 by the Ld. AO-Aurangabad requiring the assessee to file the return of income for the relevant AYs involved. In response to the said notice, the assessee filed return of income u/s 153C of the Act on 13.04.2022 for the respective AYs. Thereafter, the Pr. Commissioner of Income Tax, Nashik transferred the case of the assessee from the Ld. AO- Aurangabad to the ACIT, Circle-2(1), Pune (“the Ld. AO”) vide transfer order passed u/s 127 of the Act, dated 16.11.2022. During the assessment proceedings u/s 153C of the Act, statutory notice(s) u/s 143(2)/142(1) of the Act along with questionnaire were issued and served upon the assessee calling for various details, in response to which the assessee submitted its reply from time to time. Dissatisfied with the submissions of the assessee, the Ld. AO proceeded to pass the order u/s 153C of the Act on 30.03.2023 making disallowance in respect of educational grants provided to IFMER amounting to Rs.1,75,68,000/-. The relevant observations and findings of the Ld. AO is as under :
“Thus, in guise of the use of funds for Medical Education the funds were used for providing freebies to doctors like travel, stay etc. It is clear that the grant was not utilized for the purposes of Medical Education of doctors as claimed. This shows that the grants are nothing but a façade used to camouflage the freebies provided to doctors as quid pro quo for the business provided to the assessee company in the form of increased prescriptions of its medicines by such doctors and thereby increased sales for it.
(c) Thus, there is clearly documented violation of the Medical Council of India Guidelines. Also with respect to other two emails shared by the empl