Back


2025 Supreme(Online)(ITAT) 7192
INCOME TAX APPELLATE TRIBUNAL (CHENNAI BENCH)
S.S. VISWANETHRA RAVI, J, S. R. RAGHUNATHA, AM
M/s. Updater Services Limited – Appellant
Versus
Central Circle -2(3) – Respondent
ITA No.:1339/Chny/2025 | ITA No.: 1616/Chny/2025 | C.O.No.66/Chny/2025
For the Appellants/Petitioners: Shri. K. Prasanna, C.A.
For the Respondents: Ms. E. Pavuna Sundari, C.I.T.
Court clarifies buyback transactions are governed by distinct tax provisions, emphasizing that internal share repurchases do not invoke tax liabilities intended for third-party transfers.
Headnote:(A) Income Tax Act, 1961 - Sections 36(1)(iii), 56(2)(viia), and 115QA - Assessment Year 2017-18 - Central authorities questioned the tax implications of a buyback transaction conducted by a company under a scheme sanctioned by court. The CIT(A) ruled on the applicability of various sections; however, the ITAT found the assessment process flawed due to insufficient scrutiny. (Paras 19-32)
(B) Taxation during buyback transactions - Under Section 56(2)(viia), benefits are taxable only when shares are transferred from one entity to another, not in case of buybacks of own shares. (Paras 2.1.1, 26)
(C) Court-approved buybacks versus Section 77A compliance - It was established that buybacks executed through court-approved schemes must be distinctly assessed and are not governed by the limits of Section 77A. (Paras 2.3.1, 23)
(D) Interest deduction disallowance - Disallowance of interest under Section 36(1)(iii) was challenged due to the presence of equity funds. However, the usage of working capital was significant in the transaction. (Paras 2.2.1, 28)
| Table of Content |
|---|
| 1. the factual background of the case and procedural history. (Para 1 , 5 , 6 , 7 , 8 , 9 , 10 , 21) |
| 2. the parties’ contentions regarding tax implications and decisions. (Para 2 , 3 , 4 , 15 , 16 , 25 , 28) |
| 3. the court’s analysis and observations on procedural fairness. (Para 17 , 18 , 19 , 20 , 29) |
| 4. conclusion and order of the tribunal. (Para 32 , 33) |
आदेश/ORDER
PER S. R. RAGHUNATHA, AM:
These appeals filed by the assessee and revenue and cross objections filed by the assessee are directed against the order of the learned Commissioner of Income Tax (Appeals), Chennai, (in short “ld.CIT(A)”) for the assessment year (A.Y.) 2017-18, vide order dated 27.03.2025. Since, facts are identical and issues are common, for the sake of convenience, these appeals filed by the assessee and revenue are being heard together and disposed of by this consolidated order.
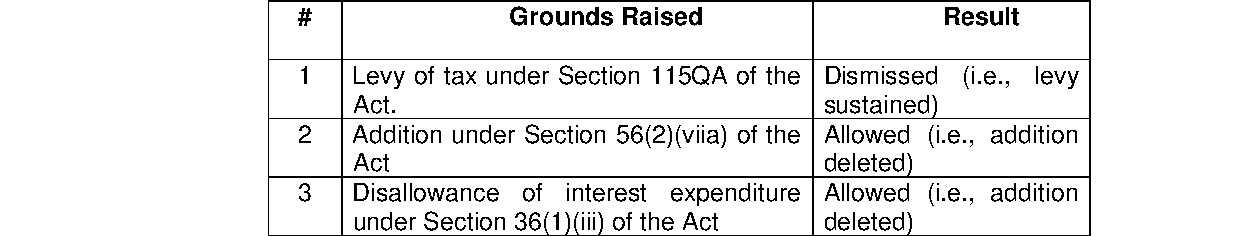
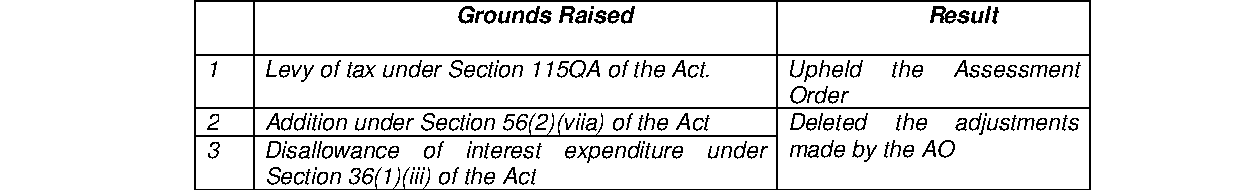
2. The grounds raised by the assessee are as follows:
ITA 1339/Chny/2025:
1. General
1.1 The order passed by the learned Deputy Commissioner of Income Tax, Central Circle 2(3), Chennai (learned AD) and to the extent confirmed by the Commissioner of Income-tax (Appeals) Chennai -19 (learned CIT(A)') under Section 250 of the Income Tax Act, 1961 (the Act) to the extent prejudicial to the Appellant is erroneous, bad in law, and contrary to the facts and circumstances of the case.
2. Non-applicability of Section 115QA of the Act
2.1 The learned CIT(A) erred in interpreting that the order of the jurisdictional ITAT against the directions of the Principal Commissioner of Income Tax under Section 263 of the Act curtails the rights of the Appellant to raise grounds on applicability of Section 115QA .
2.2 The learned CIT(A) failed to appreciate the fact that the Hon'ble Chennai ITAT has addressed only the grounds raised in respect of the jurisdictional validity of the revisionary proceedings and not the merits of the case.
2.3 The learned CIT(A) erred in law and facts by arriving at a conclusion merely relying on the observations of the learned AD and the learned Principal Commissioner of Income Tax and without independent examination / application of mind on the grounds raised by the Appellant.
2.4 The leamed CIT(A) erred in law in applying the provisions of Section 115QA of the Act to buy-back of shares undertaken prior to 01 June 2016 under Section 391 -394 of the Companies Act, 1956 .
2.5 The learned CIT(A) erred in law in holding that the provisions of Section 77A of the Companies Act, 1956 apply to the buyback of shares undertaken by the Appellant under Section 391 -394 of the without appreciating the fact that the limits, procedure, and compliances prescribed under both the regimes are different.
2.6 The learned CIT(A) failed to appreciate that the scheme approved by the Hon'ble Madras High Court is binding on them in all aspects, and the taxability has to be evaluated in light of the scheme approved and cannot be interpreted in a different manner.
2.7 The leamed CIT(A) failed to appreciate the fact that the total amount of buy-back undertaken by the Appellant is not within the threshold prescribed under Section 77A of the Companies Act, 1956 and it can only be possible under a scheme of arrangement under Section 391 -394 of the .
2.8 The learned CIT(A) failed to appreciate the fact that the Appellant has challenged the levy of tax under Section 115QA and therefore the need to challenge the quantum/ computation is not warranted.
2.9 The learned CIT(A) erred in law in holding that buy-back tax under Section 115QA of the Act would apply in respect of the said buy-back transaction.
3. The Appellant craves leave to add, alter, vary, omit, amend or delete one or more of the above grounds of appeal at any time before, or at the time of, hearing of the appeal.
3. The grounds raised by the revenue are as follows:
ITA 1616/Chny/2025:
1. The order of the learned Commissioner of Income Tax (Appeals) is erroneous on facts of the case and in law.
2 The LA CIT(A) erred in deleting