Back


2025 Supreme(Online)(ITAT) 7350
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
SHRI VIKRAM SINGH YADAV, A.M, SHRI ANIKESH BANERJEE, J.M
Ador Welding Limited – Appellant
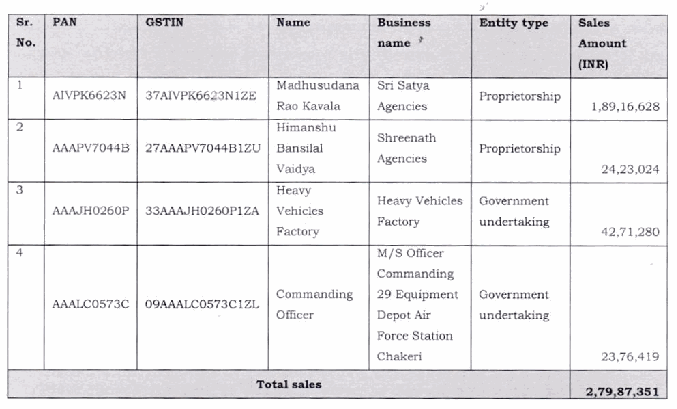
Versus
Deputy Commissioner of Income Tax, Circle-2(1)(1) – Respondent
Assessment Year : 2021-22
For the Appellants/Petitioners: Ms. Rupal Kaku
For the Respondents: Shri Surendra Mohan, Sr.DR
The court emphasized the importance of adhering to procedural fairness and the necessity of a proper basis for tax assessments, focusing on principles of natural justice in administrative proceedings.
Headnote:(A) Income Tax Act, 1961 - Sections 69A and 143(3) - Assessment proceedings - Appeal filed by the assessee against the order of the CIT(A) upholding the AO’s additions of undisclosed sales amounting to Rs. 2,79,87,351/- under section 69A - The court held that the AO violated principles of natural justice by not providing adequate time for response to the show-cause notice regarding allegations based on shifting bases of assessment, failing to establish a cogent basis for the addition - Consequently, the order of the CIT(A) was set aside and the matter was remitted to the AO for verification. (Paras 4, 9, 24)
| Table of Content |
|---|
| 1. appellant's right to fair assessment processes. (Para 1 , 2 , 4 , 5 , 22) |
| 2. natural justice violations must be addressed. (Para 3 , 9 , 23) |
| 3. challenges on shifting allegations in assessment. (Para 6 , 10 , 12 , 21) |
| 4. completeness of evidence is crucial for conclusions. (Para 19 , 20) |
| 5. remand for further examination and verification. (Para 24 , 26) |
ORDER
PER VIKRAM SINGH YADAV, A.M :
This is an appeal filed by the assessee against the order of the Learned Commissioner of Income Tax (Appeals)-National Faceless Appeal Centre (NFAC), Delhi [„Ld. CIT(A)‟], dated 17-12-2024, pertaining to Assessment Year (AY) 2021-22.
2. At the outset, it is noted that there is a delay of 84 days in filing the appeal as pointed out by the Registry. After hearing both the parties and perusing the facts placed on record, we find that there was reasonable cause for the delay in filing the present appeal and hence, the delay is hereby condoned and appeal is admitted for adjudication.
3. Briefly the facts of the case are that the assessment in this case was completed u/s. 143(3) r.w.s. 144B of the Income Tax Act, 1961 („the Act‟) vide order dt. 13-12-2022, wherein the AO has brought to tax undisclosed sales amounting to Rs. 2,79,87,351/- u/s. 69A r.w.s. 115BBE of the Act. Thereafter, the assessee carried the matter in appeal before the Ld.CIT(A), who has since sustained the said findings of the AO and against the said order, the assessee is in appeal before us.
4. During the course of hearing, the Ld.AR submitted that the case of the assessee was selected for complete scrutiny assessment u/s.143(3) of the Act pursuant to notice u/s.143(2) issued on 27-06-2022 by the Faceless Assessment Centre. Subsequently, a notice u/s.142(1) dated 17-08-2022 was issued calling for information such as nature of business, financials, computation of income, etc. During that stage, no questions were raised or clarifications sought with regard to any unexplained transactions or parties. Thereafter, a show cause notice was issued on 30-11-2022, proposing an income variation of Rs.2,79,87,351/- and the assessee was directed to respond before 03-12-2022 i.e., less than three days time, in clear violation of the principles of natural justice and the standard operating procedure requiring a minimum of seven days response time.
5. It was submitted that the show cause notice was based on information uploaded on the Insight Portal, wherein the AO alleged that the assessee had made bogus payments to the following four entities:
i. Heavy Vehicles Factory
ii. Commanding Officer
iii. Sri Satya Agencies (Madhusudan Rao Kavala)
iv. Shreenath Agencies (Himanshu Bansilal Vaidya)
It was alleged that these were non-filers and that the payments were sham in nature.
6. It was further submitted by the Ld.AR that despite the extremely short notice, the assessee submitted a response on 05-12-2022, whereby it was clarified that-
No such expenses were claimed in the income tax return or in the books of accounts maintained under the Companies Act that involved the said parties.
Heavy Vehicles Factory and Commanding Officer are Government undertakings, and cannot, under any reasonable standard, be treated as sham entities. These entities are in fact customers of the assessee and not vendors.
The only payments ever made to these two entities were Earnest Money Deposits (EMD); no business expenditure was claimed in respect of them.
With respect to Sri Satya Agencies and Shreenath Agencies, the assessee clearly stated that no expenses were booked or claimed in relation to these parties.
Accordingly, the assessee requested that the Show Cause Notice be dropped in its entirety, as the very basis of the proposed addition was factually incorrect.
7. It was also submitted that a particularly concerning aspect of the assessment proceedings is the fundamental shift in the basis of the allegation, driven by a change in the information source-from data on the Insight Portal to that from the GST Depar