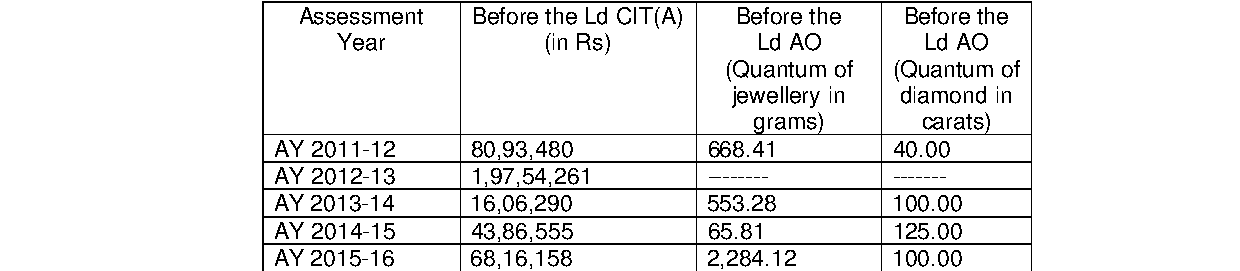
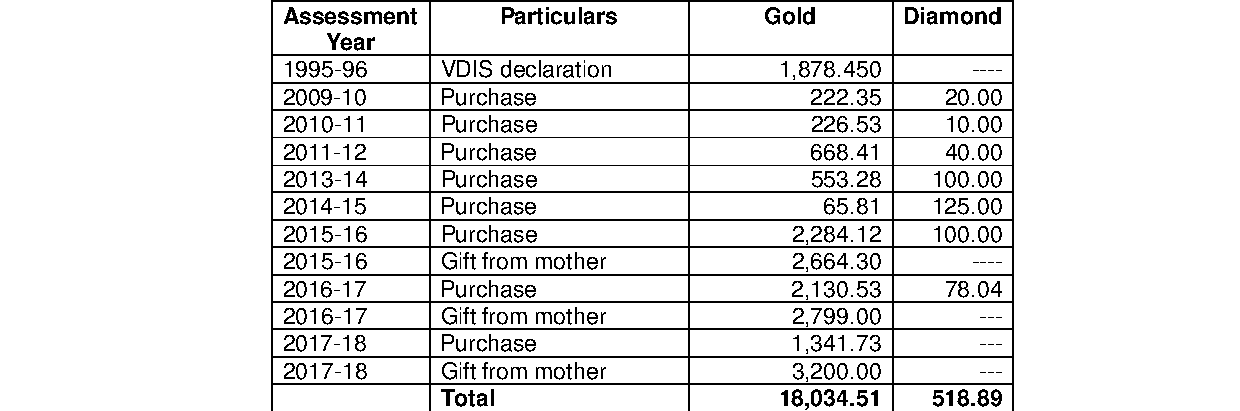
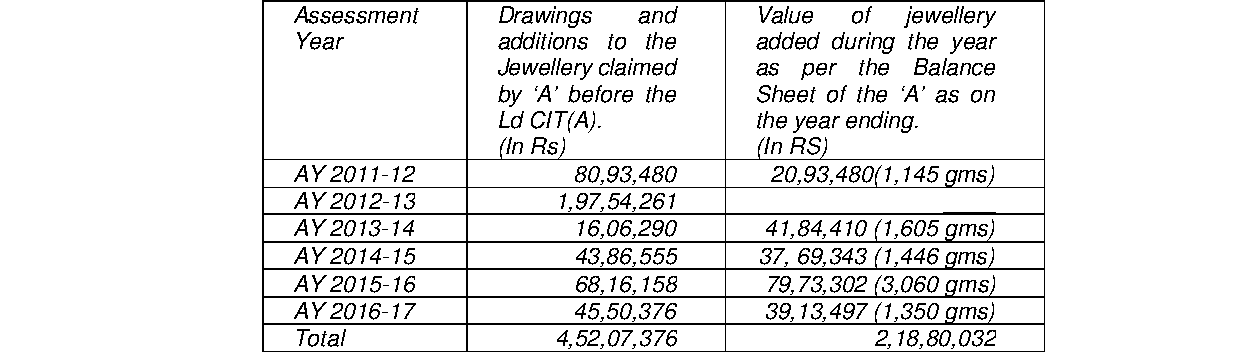
Back


2025 Supreme(Online)(ITAT) 7390
INCOME TAX APPELLATE TRIBUNAL (CHENNAI BENCH)
SHRI ABY T VARKEY, J, SHRI S.R.RAGHUNATHA, ACJ
DCIT CHENNAI – Appellant
Versus
JAGATHRAKSKAN SRINISHA CHENNAI – Respondent
ITA Nos.: 1253, 1264 & 1271/Chny/2025
For the Appellants/Petitioners: Shri. B. Ramakrishnan, FCA, Shri. Shrenik Chordia, CA
For the Respondents: Shri. C.N. Bipin, C.I.T.
Penalties under the Income Tax Act cannot be imposed on amounts assessed based solely on estimations or when insufficient evidence of concealment exists.
Headnote:(A) Income Tax Act, 1961 - Sections 143(3), 270A, 154, and 115BBE - Unexplained investments - Revenue's appeal against CIT(A) decision allowing partial relief by sustaining Rs.72,45,018 as unaccounted business income amidst estimates by AO regarding jewellery worth Rs.14,60,33,144 seized during the search - Taxpayer's rebuttal of ownership presumption without evidence found during the search - CIT(A) justified in deleting sections applied for penalty and affirming estimation as business income rather than unexplained investment. (Paras 1-35)
(B) Penalty - Applicability under sections - It was held that penalties cannot be imposed for assessments based on estimations or in absence of clear findings about misreporting, and the alternative section for penalty should apply; herein, section 271AAC was more pertinent based on nature of income. (Paras 28-34)
Facts of the case:
The appeal arose from an assessment where after a search on the premises of a connected individual, substantial jewellery was seized. The AO labelled these as unexplained investments. CIT(A) found only part of the additions justified after thorough evaluation.
Findings of Court:
CIT(A) evaluated evidence, suggesting many jewellery pieces belonged to family members, rendering the presumption that the items solely belonged to the taxpayer rebuttable, thus necessitating the deletion of large portions of the AO's additions, concluding only Rs.72,45,018 remains taxable.
Issues: The court primarily focused on the ownership of jewellery claimed as unexplained, the impact of VDIS declarations, and the admissibility of penal actions on estimates or assumptions rather than confirmed facts.
Ratio Decidendi: The court concluded that additional taxation must rely on established facts rather than assumptions or estimations, underscoring that penalties cannot be levied where underlying assessments are made on speculative grounds or lack adequate substantiation.
Result: Appeals dismissed.
| Table of Content |
|---|
| 1. filing of revenue's appeal against cit(a) order. (Para 1 , 2) |
| 2. facts regarding seizure of jewellery during search. (Para 3 , 4) |
| 3. revenue's objections to cit(a) findings. (Para 5 , 6) |
| 4. arguments regarding onus of proof for gift claims. (Para 7 , 8) |
| 5. production of documents supporting claims. (Para 9) |
| 6. cit(a)'s conclusions on jewelry ownership. (Para 10 , 11) |
| 7. considering cultural norms for gift claims. (Para 12 , 13) |
| 8. estimates of income and penalties. (Para 14 , 15) |
| 9. cit(a)'s reasoning on penalties. (Para 16) |
| 10. cit(a)'s dismissal of penalty appeals. (Para 20 , 21) |
| 11. arguments about procedural validity in penalty assessments. (Para 30 , 31) |
आदेश /ORDER
PER S.R.RAGHUNATHA, AM:
The present appeal is preferred by the Revenue against the order dated 06.02.2025 passed by the Commissioner of Income Tax (Appeals)-19 (hereinafter referred to as Ld.CIT(A), Chennai, in respect of the assessment order dated 01.03.2019 passed by the Deputy Commissioner of Income Tax, Central Circle -2(3) (hereinafter referred to as AO) for the assessment year 2017-18 (hereinafter referred to as the impugned assessment year) u/s.143(3) of the Income Tax Act, 1961 (hereinafter referred to as the Act).
2. Apart from the above appeal on the quantum assessment, the Revenue is also aggrieved on the appellate orders in respect of the penalty order passed u/s.270A of the Act and the rectification order passed u/s.154 of the Act. We are dealing with them one by one.
2.1 At the outset, we note that the revenue’s appeal in ITA No.1271/Chny/2025 has been filed with a delay of 01 day. After considering the explanation provided, we are of the considered view that the revenue was prevented by sufficient cause from filing the appeal within the prescribed time limit. Accordingly, we condone the delay and the appeal is admitted for adjudication on merits.
Appeal in respect of the assessment order dated 01.03.2019 in ITA No.:1271/Chny/2025:
The brief facts of the case are as follows:
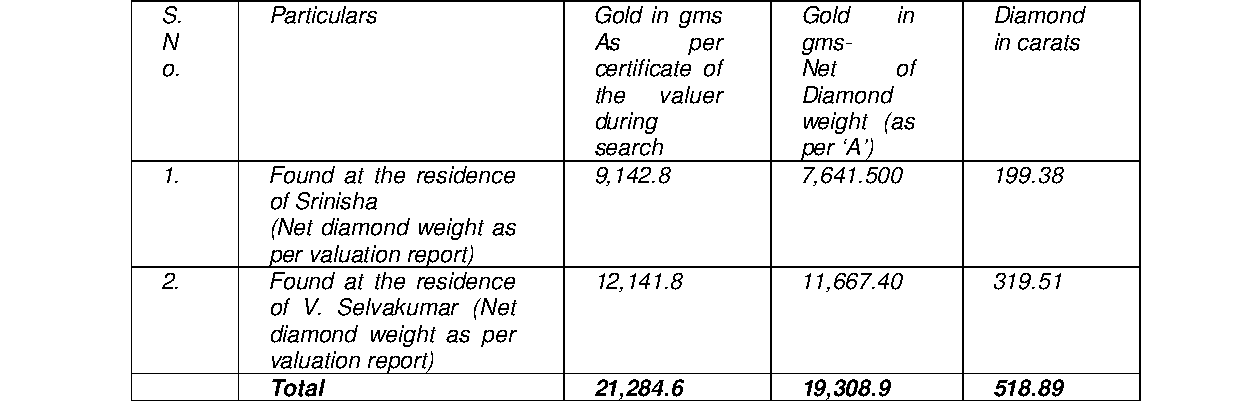
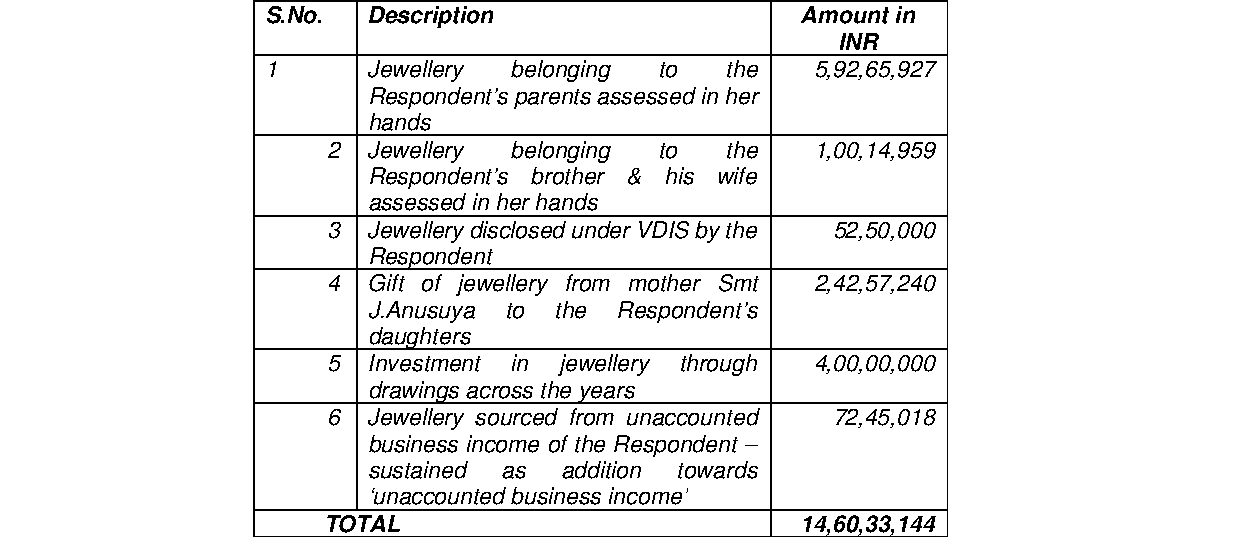
3. The assessee is an individual and is the daughter of Shri. S.Jagathrakshakan. A search was conducted u/s.132 of the Act, in the premises of Shri.Jagathrakshakan and group on 13.07.2016. During the course of search proceedings, gold / diamond jewellery and silver articles to the tune of Rs.10,29,10,676/- (29,121.350 Grams of gold jewellery and 684.79 carats of diamond jewellery) and that of Rs.5,23,15,699/- (12,910.400 grams of gold jewellery, 321.15 carats of Daimond jewellery and 797 grams of silver articles) were found by the Revenue at the residence of Mr.S.Jagathrakshakan and that of Mr.Selvakumar respectively. Based on the statements recorded u/s.131 of the Act, the AO rejected the submissions of the assessee and made an addition of Rs.14,60,33,144/- (Rs.9,37,17,445/- which is out of Rs.10,29,10,676/- seized in the premises of Mr.S.Jagathrakshakan plus Rs.5,23,15,699/- seized in the premises of Mr.Selvakumar) as ‘unexplained investment’ in gold / diamond jewellery by passing an order u/s.143(3) of the Act dated 01.03.2019.
4. Aggrieved by the order of the AO, the assessee preferred an appeal before the Ld.CIT(A), who partly allowed the assessee’s appeal by holding that, out of the addition made to the tune of Rs.14,60,33,144/- under the head ‘unexplained investment’, an estimated sum of Rs.72,45,018/- alone is taxable, however, under the head ‘unaccounted business income’. The Ld.CIT(A) decided the issue in favour of the assessee as follows:
- Out of Rs.14,60,33,144/-, added by the AO, jewellery worth a sum of Rs.6,92,80,886/- belongs to the assessee’s parents and brother & sister-in-law. The Ld.CIT(A) called for valuation report from the AO, who gave the break-up of jewellery belonging to the assessee’s parents and brother & sister-in-law. Based on the valuation report, Rs.6,92,80,886/- was deleted from the addition made.
- Thereafter, jewellery worth a sum of Rs.52,50,000/- was deleted for the reason that value of 1,875 grams of jewellery was already offered u