
 Back


INCOME TAX APPELLATE TRIBUNAL (HYDERABAD BENCH)
SHRI VIJAY PAL RAO, VP, SHRI MADHUSUDAN SAWDIA, AM
Praveen Kumar – Appellant
Versus
The Income Tax Officer – Respondent
ITA No.1370/Hyd/2025
| Table of Content |
|---|
| 1. challenging reassessment validity (Para 1 , 2) |
| 2. arguments on authority for reassessment (Para 3 , 4) |
| 3. court findings on compliance with law (Para 5 , 6) |
| 4. final ruling on appeal outcome (Para 7 , 8) |
आदेश/ORDER
PER VIJAY PAL RAO, VICE PRESIDENT :
This appeal by the Assessee is directed against the order dated 30.06.2025 of learned CIT(A)-National Faceless Appeal Centre [in short “NFAC], Delhi, for the assessment year 2017-2018.
2. The assessee has raised the following grounds : 1. “The learned CIT(A) failed to consider the additional ground and submissions filed on 17.06.2025, wherein the appellant challenged the validity of reassessment u/s 147, since the notice u/s 148 was issued without the valid sanction mandated u/s 151, rendering the reassessment void ab initio.
2. The learned CIT(A) failed to appreciate that the notice u/s 148 issued by the Jurisdictional AO was in contravention of the Faceless Assessment/ Reassessment Scheme notified by CBDT, thereby rendering the reassessment void ab initio.
3. The learned CIT(A) failed to appreciate the fact that the notice u/s.148 did not contain a valid Document Identification Number (DIN) as mandated by CBDT Circular No.19/2019 dated 14.08.2019, thereby rendering the entire reassessment proceedings invalid.
4. The learned CIT(A) is not justified in upholding the reassessment order passed u/s 144 r.w.s. 147 without appreciating the fact that the Assessing officer failed to supply any material relied upon to the appellant which suggest that investment was Rs.35,00,000/-, thereby failed to adhere to the binding directions of the Hon'ble Supreme Court in the case of Union of India v. Ashish Agarwal (2022) 444 ITR 1 (SC).
5. The learned CIT(A) is not justified in not adjudicating upon the legal grounds specifically raised before him, though in law he was required to decide the same himself, instead of remitting the matter to the Assessing Officer.
6. The appellant craves, leave to add amend or alter any of the grounds at the time of the hearing of the appeal.”
3. The assessee has raised a legal issue regarding the validity of the notice issued by the Assessing Officer u/sec.148 of the Act for want of valid sanction/approval u/sec.151 of the Income Tax Act, 1961 [in short "the Act"]. The learned Authorised Representative of the Assessee has submitted that the Assessing Officer has issued notice u/sec.148 of the Act on 30.06.2022 which is beyond three years from the end of the assessment year under consideration. Therefore, as per the provisions of sec.151 of the Act, the approval/sanction was to be granted by the CCIT instead of Pr. CIT. He has filed copy of the notice u/sec.148 exhibiting the fact that approval was taken from the Pr. CIT-2, Hyderabad and, therefore, in the absence of a valid approval u/sec.151 of the Act, the notice issued by the Assessing Officer is invalid and liable to be quashed. In support of his contention, he has relied upon the decision of this Tribunal dated 20.06.2025 in the case of Iqbal Ali Jaweed, Hyderabad vs., The Income Tax Officer, [INT. TAXN]-1, Hyderabad in ITA .Nos.447 & 448/Hyd./2024 for the assessment years 2016-2017 & 2017-2018.
4. On the other hand, the learned DR has relied upon the orders of the authorities below.
5. We have considered the rival submissions as well as relevant material on record. The Assessing Officer has issued notice u/sec.148 of the Act dated 30.06.2022 as under :
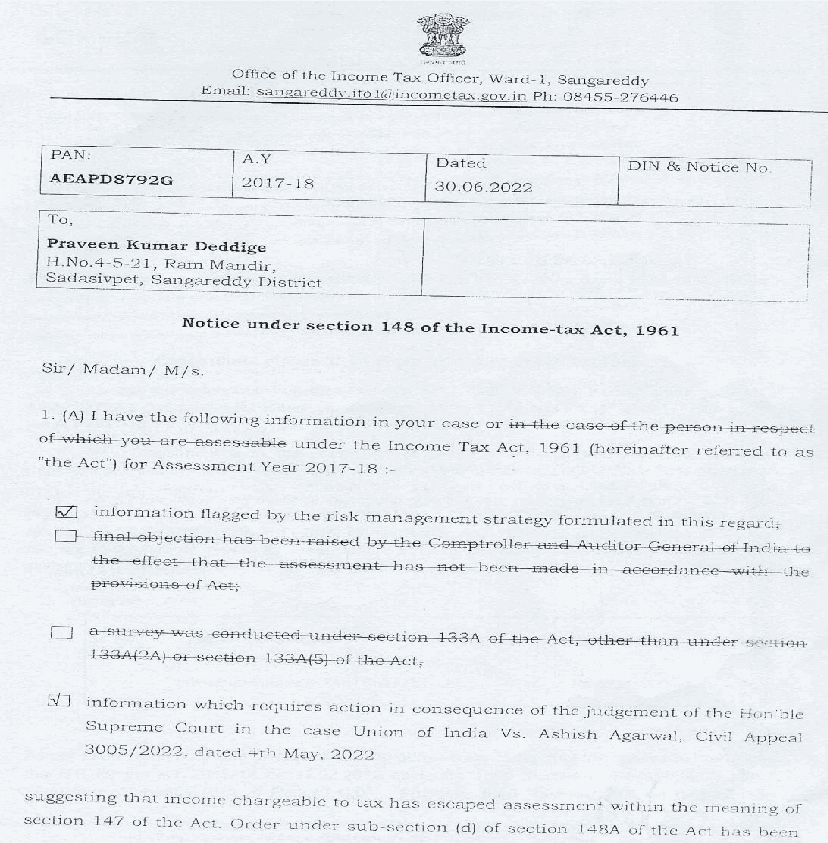
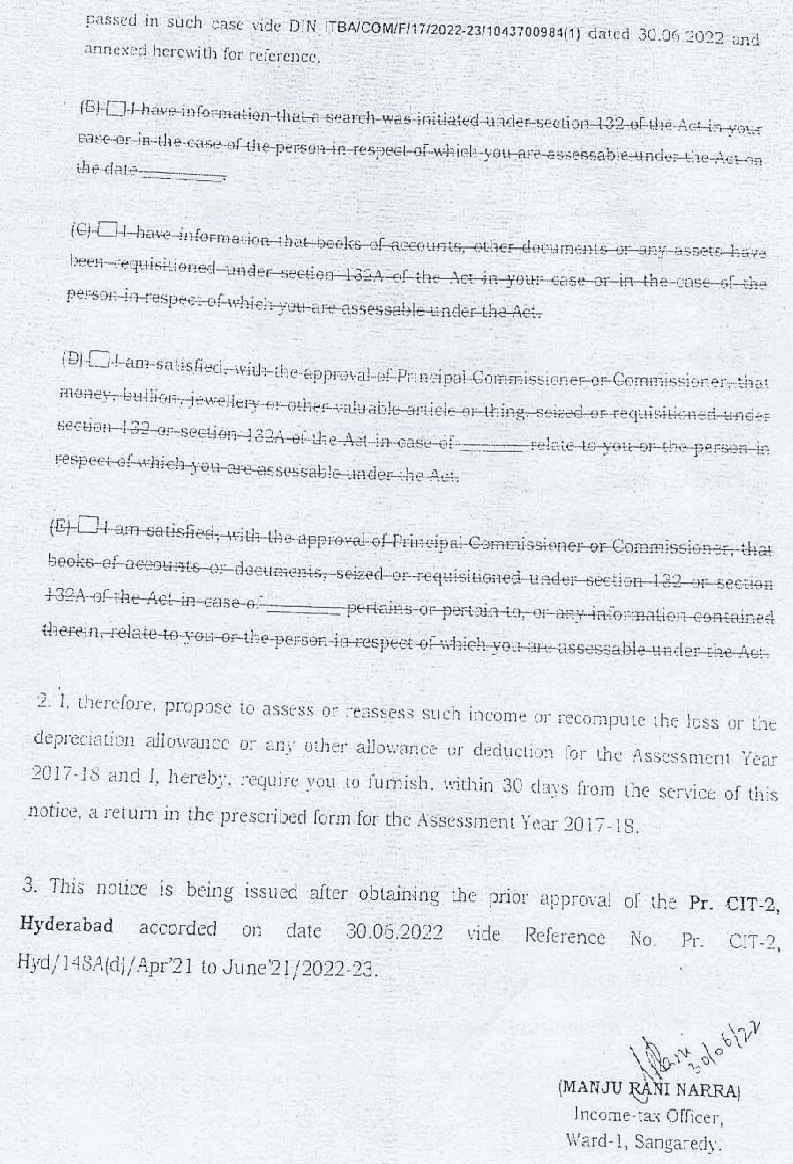
6. It is not in dispute that the said notice u/sec.148 of the Act was issued after the expiry of three years from the end of the relevant assessment year under consideration. It is also not in dispute and also manifest from Para-3 of the notice that an approval was obtained from the Pr. CIT-2, Hyderabad, whereas as per the provisions of sec.151 of the Act, if a notice u/sec.148 is issued after three years from the end of the assessment year, then, the Competent Authority to grant approval is CCIT and not Pr. CIT. An identical issue has been considered


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


