Back


2025 Supreme(Online)(ITAT) 7619
INCOME TAX APPELLATE TRIBUNAL (JAIPUR BENCH)
DR. S. SEETHALAKSHMI, JM, SHRI RATHOD KAMLESH JAYANTBHAI, AM
Shambhu Dayal Soni – Appellant
Versus
Income Tax Officer – Respondent
ITA No. 921/JP/2025
For the Appellants/Petitioners: Sh. S. L. Poddar, Adv.
For the Respondents: Sh. Gautam Singh Choudhary, Addl. CIT
The unexplained cash deposits cannot be taxed if their source is disclosed as part of regular business activities and sales are accepted, highlighting procedural validity in tax assessment notices.
Headnote:(A) Income Tax Act, 1961 - Sections 69A, 147, 148, and 151 - Appeal against assessment order for AY 2017-18 - Assessee challenged addition of Rs. 14,10,000/- made as unexplained cash deposit during demonetization period - The order by the Assessing Officer was predicated on the alleged inability of the Assessee to explain the source of cash deposits - The Court noted that the Assessing Officer had failed to reject the cash book maintained by the Assessee - The cash deposits were supported by cash sales recorded in the cash book and trading account - Court reaffirmed that unexplained cash deposits cannot be taxed if the source of such cash has already been disclosed and subject to tax - Additionally, it ruled that procedural lapses in the issuance of notice under sections 148 and 151 rendered it void, necessitating quashing of the assessment proceedings in part. (Paras 1, 2, 7.1, 7.4, 10)
| Table of Content |
|---|
| 1. background of the case. (Para 1) |
| 2. grounds of appeal stated by the assessee. (Para 2) |
| 3. details of contested assessment and cash deposits. (Para 3 , 5) |
| 4. legal implications of assessment procedures. (Para 4 , 8 , 9) |
| 5. observations on unexplained cash deposits. (Para 7) |
| 6. outcome of the appeal. (Para 10) |
ORDER
PER: RATHOD KAMLESH JAYANTBHAI, AM
By way of present appeal the above named assessee – appellant challenges the order of the National Faceless Appeal Centre, Delhi [ for short CIT(A)] dated 10/06/2025 for assessment year 2017-18. The said order of the ld. CIT(A) arises because the assessee has challenged the assessment order dated 27.04.2023 passed under section 147 r.w.s 144B of the Income Tax Act, 1961 [ for short “AO”] by Assessment Unit of Income Tax Department [ for short AO].
2. In this appeal, the assessee has raised following grounds: -
“1. Under the facts and circumstances of the case the learned CIT(A) has erred in confirming the order passed by learned AO u/s 147 of the IT Act, 1961.
2. Under the facts and circumstances of the case the learned CIT(A) has erred in confirming the addition of Rs. 14,10,000/- u/s 69A of the IT Act, 1961 for cash deposited in bank during demonetarization period.
3. Under the facts and circumstances of the case the learned CIT(A) has erred in confirming the application of provisions of section 115BBE of the IT Act, 1961.
4. The appellant crave to add, amend OR alter all OR any grounds of appeal before OR at the time of hearing of appeal.
2.1 Further, in this appeal, the assessee has raised following additional grounds: -
Additional Ground No.1
On the facts and in the circumstances of the case and in law, the Learned CIT(A) has erred in not quashing the order u/s 148A(d) passed by the Learned Assessing Officer on 25/7/2022 with the approval of Principal Commissioner-1, Jaipur whereas the approval required u/s 151(2) should have been of Pr. Chief Commissioner of Income Tax/Pr. DGIT, hence, the order passed is ab initio void.
Additional Ground No.2
On the facts and in the circumstances of the case and in law, the Learned CIT(A) has erred in not quashing the notice u/s 148 issued on 25/7/2022 by the Learned Assessing Officer with the approval of Principal Commissioner-1, Jaipur whereas the approval required u/s 151(2) should have been of Pr. Chief Commissioner of Income Tax/Pr. DGIT, hence, the notice issued is ab initio void.
Additional Ground No.3
On the facts and in the circumstances of the case and in law, the Learned CIT(A) has erred in not quashing the notice u/s 148 issued on 25/7/2022 by the Jurisdictional Assessing Officer (Jethanand Bhoolchandani, ITO Ward 1(1), Jaipur) whereas after 29/03/2022, notice u/s 148 could have been issued by N.F.A.C.only.
Additional Ground No.4
On the facts and in the circumstances of the case and in law, the Learned CIT(A) has erred in not quashing the notice u/s 148 issued on 25/7/2022 by the Learned Assessing Officer without quoting DIN in the body of the notice. The notice issued is ab initio void.
Additional Ground No.5
On the facts and in the circumstances of the case and in law, the Learned CIT(A) has erred in not quashing the notice u/s 148 issued on 25/7/2022 by the Learned Assessing Officer without meeting the condition laid down in Sec. 149(1)(b) that the amount of escaped income has to be fifty lac or more in cases beyond the period of three years from the end of the relevant assessment year.
Since the above grounds so raised by the assessee are legal in nature and does not require finding of fact and the same are admitted considering the decision of the Apex Court in the case of NTPC Ltd. [ 229 ITR 383]
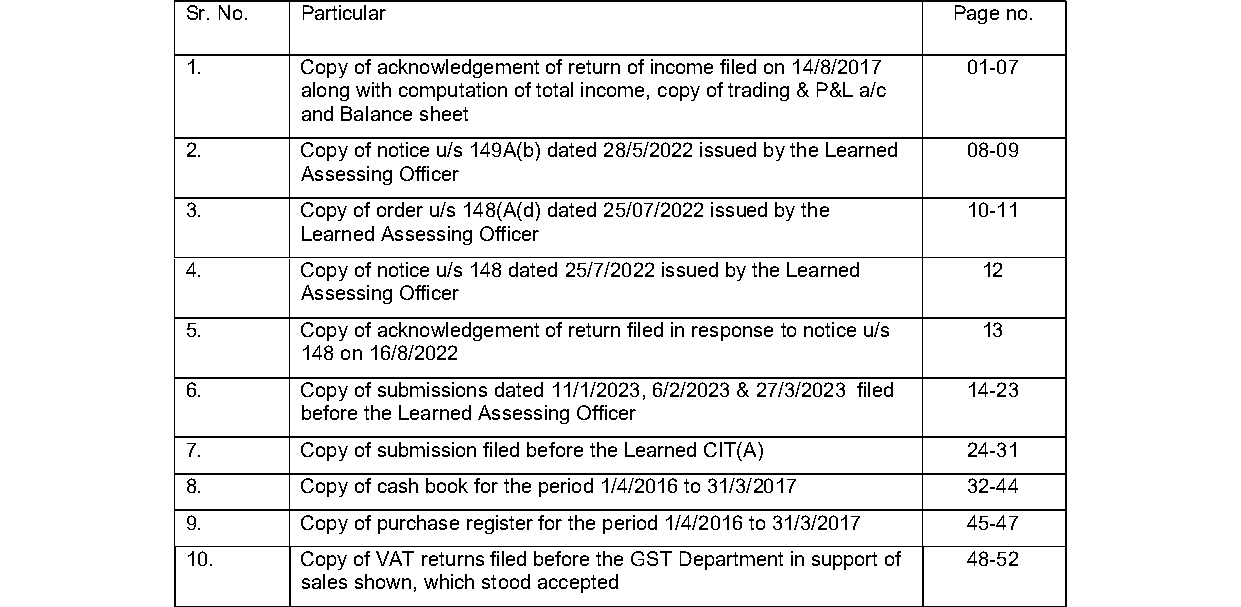
3. Succinctly, the fact as culled out from the records is that in the case of the assessee, a specific information was available that the assessee Shri Shmbhu Dayal Soni (PAN: AFGPS9157M) is an individual, engaged in job work of gold & silver ornaments with trading of gold and silver jewellery and has filed the return of income for AY 2