Back


2025 Supreme(Online)(ITAT) 7709
INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
Shri Rifa Umar Rahman, ACJ, Shri Vimal Kumar, J
M/s. Gold Spice Impex – Appellant
Versus
ITO, Ward 47 (2) – Respondent
Income Tax Appeal
For the Appellants/Petitioners:Shri Rakesh Gupta, Advocate, Shri Deepesh Garg, Advocate
For the Respondents: Shri Rajesh Kumar Dhanesta, Sr. DR
Taxpayers must adequately comply with assessment requirements to avoid unwarranted tax additions; failure to do so may result in part of the assessment being sustained.
Headnote:(A) Income Tax Act, 1961 - Sections 68 and 115BBE - Appeal against assessment order - The assessee challenged the addition of Rs.1,15,00,000/- on account of cash deposits made during demonetization, asserting compliance with tax laws and principles of natural justice - The court observed failures by the assessee to respond adequately to inquiries regarding cash deposits - Ultimately, the court sustained part of the addition while ruling that provisions of section 115BBE could not be applied to the case as they pertain to post-2017 transactions. (Paras 2 to 11)
(B) Compliance - Importance of compliance with notices issued by the Assessing Officer - The court emphasized that the responsibility lies with the taxpayer to submit relevant information, and non-compliance may lead to adverse findings. (Para 8)
Facts of the case:
The appellant filed the income return for AY 2017-18, declaring an income of Rs.68,540/- and faced scrutiny due to large cash deposits during demonetization. The AO made additions u/s 68 without adequate disclosures from the appellant regarding the cash deposits.
Findings of Court:
While acknowledging some compliance, the court permitted a part of the addition, eventually sustaining 10% of the cash deposits as justified. It was concluded that the relevant provisions for taxation under section 115BBE could not be applied retrospectively to the appellant's transactions.
Issues: The appeal delved into the adequacy of the appellant's justification for cash deposits during demonetization and the applicability of section 115BBE for taxing the income attributed to prior transactions.
Ratio Decidendi: The court ruled that assertions of undeclared income must be supported by evidence, and emphasized the importance of compliance with procedural requirements during tax assessments. It was concluded that substantial parts of the cash deposits were legitimate and compliant with tax regulations.
Result: Appeal partly allowed.
| Table of Content |
|---|
| 1. appeal against assessment order (Para 1 , 2 , 3) |
| 2. compliance by appellant (Para 4 , 5) |
| 3. court's evaluation of evidence (Para 6 , 7 , 8 , 9) |
| 4. application of legal provisions (Para 10) |
| 5. outcome of the appeal (Para 11) |
ORDER
PER S. RIFAUR RAHMAN, ACCOUNTANT MEMBER :
1. The assessee has filed appeal against the order of the Learned Commissioner of Income-tax (Appeals)/National Faceless Appeal Centre (NFAC), Delhi [“Ld. CIT(A)”, for short] dated 17.01.2024 for the Assessment Year 2017-18 raising following grounds of appeal :-
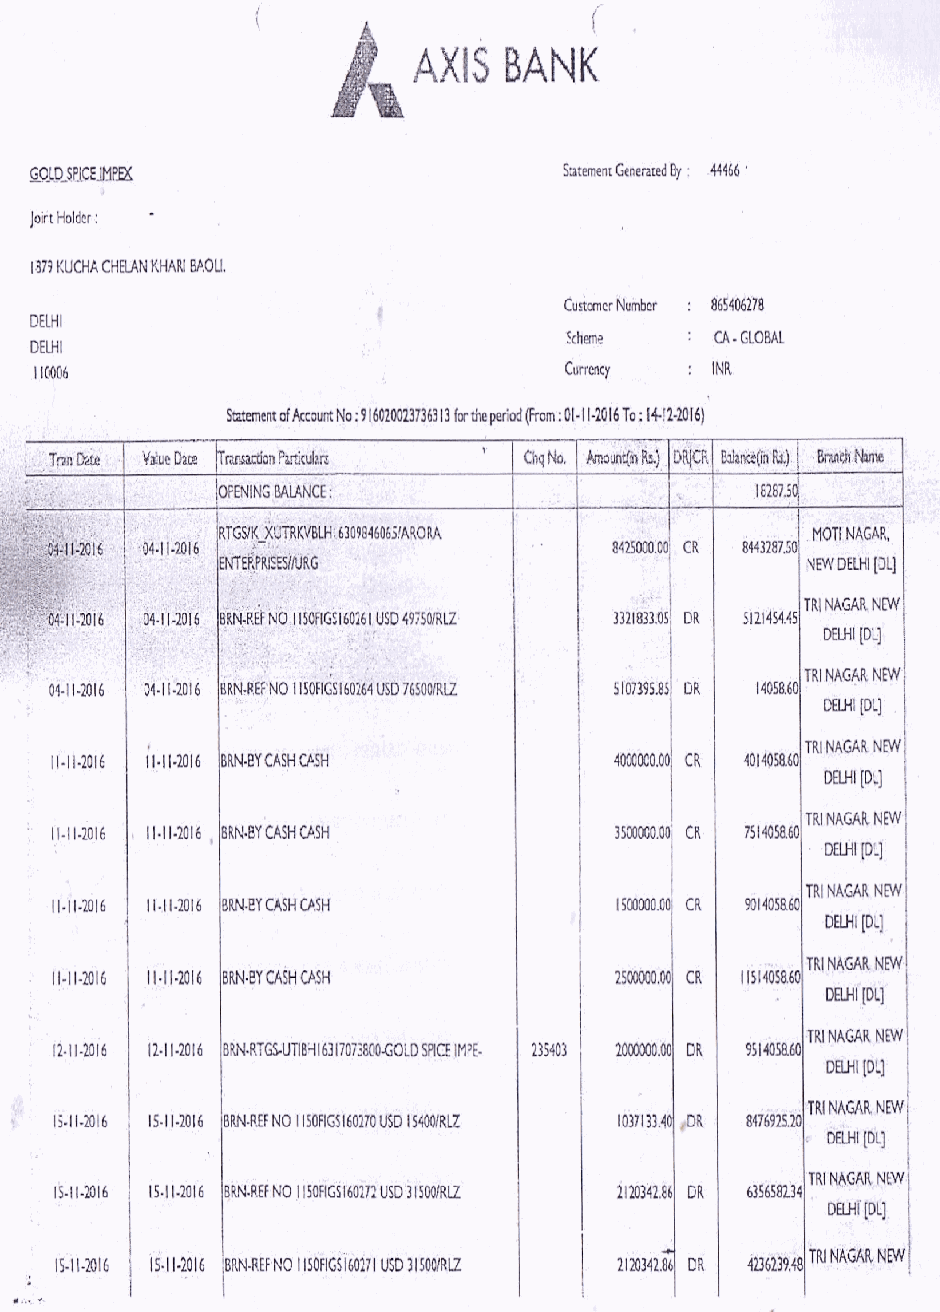
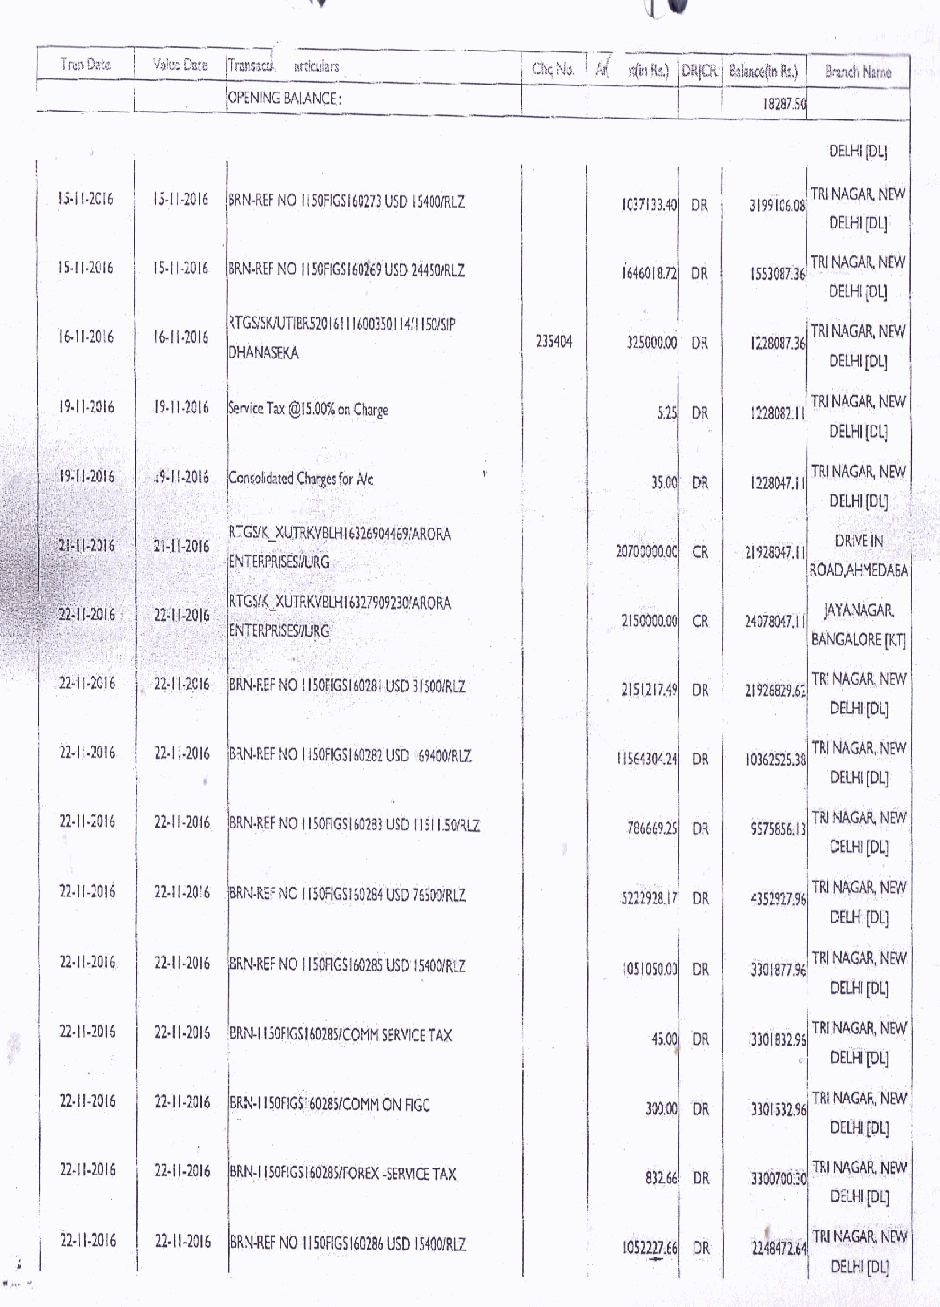
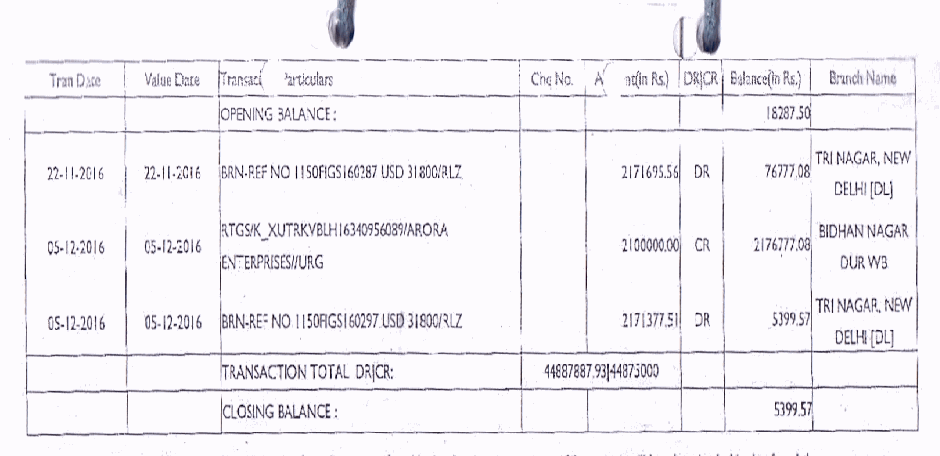
“1. That having regard to the facts and circumstances of the case, Ld. CIT(A) has erred in law and on facts in confirming the action of Ld. AO in making aggregate addition of Rs.1,15,00,000/- on account of cash deposits u/s 68 and taxing the same u/s 115BBE and that too by recording incorrect facts and findings and without following the principles of natural justice.
2. That in any case and in any view of the matter, action of Ld. CITCA) in confirming the action of Ld. AO in making aggregate addition of Rs.1,15,00,000/- on account of cash deposits u/s 68/115BBE, is bad in law and against the facts and circumstances of the case.
3. That having regards to the facts and circumstances of the case, the Ld. CITCA) erred in law and facts, in addition of cash deposited during demonetization period of admitted sales as per the audited books of account as well as per the returns filed under Delhi Value Added Tax leading to double addition and without providing relief of reduced sales and stock as per the Provisions of Income Tax Act, 1961 .
4. That having regards to the facts and circumstances of the case, the Ld. "CIT(A) erred in law and facts, in violating the principles of natural justice by not affording an opportunity before proceeding to pass an order as per the provisions of tile Income Tax Act, 1961 .
5. That having regards to the facts and circumstances of the case, the Ld. CIT(A) erred in law and facts in proceeding with the matter without being reasonable, just and applying his mind.
6. That having regards to the facts and circumstances of the case, the Ld. Assessing Officer erred in law and facts, without prejudice to the above in treating the income of business as Income of Other Sources.
7. That having regard to the facts and circumstances of the case, Ld. CIT(A) has erred in law and on facts in not reversing the action of Ld. AO in charging interest u/s 234B, 234C and 234D of Income Tax Act, 1961 .”
2. The assessee has raised solitary issue of addition made under section 68 of the Income-tax Act, 1961 (for short ‘the Act’) and taxing the same u/s 115BBE of the Act. The relevant facts of the issues raised by the assessee are, assessee filed its return of income for AY 2017-18 on 24.10.2017 declaring an income of Rs.68,540/-. The case was selected for scrutiny through CASS for the following reasons :-
1. Large cash deposit during demonetization period and abnormal increase in sales with decrease in profitability as compared to preceding previous year.
2. Abnormal increase in cash deposits during demonetization period as compared to pre-demonetization period.
3. Custom Duty paid as shown in the ITR is less than the duty paid as per export import data.
3. Accordingly, notices u/s 143(2) and 142(1) of the Act were issued and served on the assessee. Several notices were issued to the assessee to provide the information in particular format about opening stock, purchases, total sales, cash sales, credit sales and closing stock and specifically assessee was asked to provide statement of cash deposit and cash sales for three financial years i.e. 2015-16 to 2017-18. In response, assessee has not submitted the relevant information as asked by the AO in the above said particular format. Due to non-compliance of the above requirement, the AO observed that the case of the assessee was basically selected to verify the cash deposit made by the assessee during demonetization period and he came to the conclusion