
 Back


INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
SHRI ANUBHAV SHARMA, JM, SHRI MANISH AGARWAL, AM
Shokeen Construction Co. – Appellant
Versus
DCIT – Respondent
Income Tax Appeal | ITA No.5971/Del/2024 | ITA No.5972/Del/2024 | ITA No.5973/Del/2024
| Table of Content |
|---|
| 1. procedural integrity in initiation of income assessments. (Para 4 , 5 , 8) |
| 2. judicial requirement for independent judgment in satisfaction recording. (Para 10 , 13 , 18) |
| 3. final ruling on appeals allowed based on procedural invalidity. (Para 19 , 22 , 26) |
ORDER
PER MANISH AGARWAL, AM :
The captioned appeals are filed by assessee against the different orders, all dated 16.12.2024 passed by Ld. Commissioner of Income Tax (A)-30, New Delhi [“Ld. CIT(A)”] in Appeal No. 30/10343/2017-18; Appeal No.30/10575/2018-19; and Appeal No. 30/10736/2019-20 passed u/s 250 of the Income Tax Act, 1961 [“the Act”] arising out of assessment orders, all dated 20.03.2023 passed u/s 153C r.w.s. 143(3) of the Act pertaining to assessment year 2018-19 to 2020-21 respectively.
2. As these captioned appeals filed by the assessee have similar issues which are inter-linked, inter-connected and this fact has been admitted by both the parties during the course of hearing before us, therefore, these three appeals filed by the assessee are decided by a common order.
3. First we take up the appeal of assessee in ITA No.5971/Del/2024 for Assessment Year 2018-19.
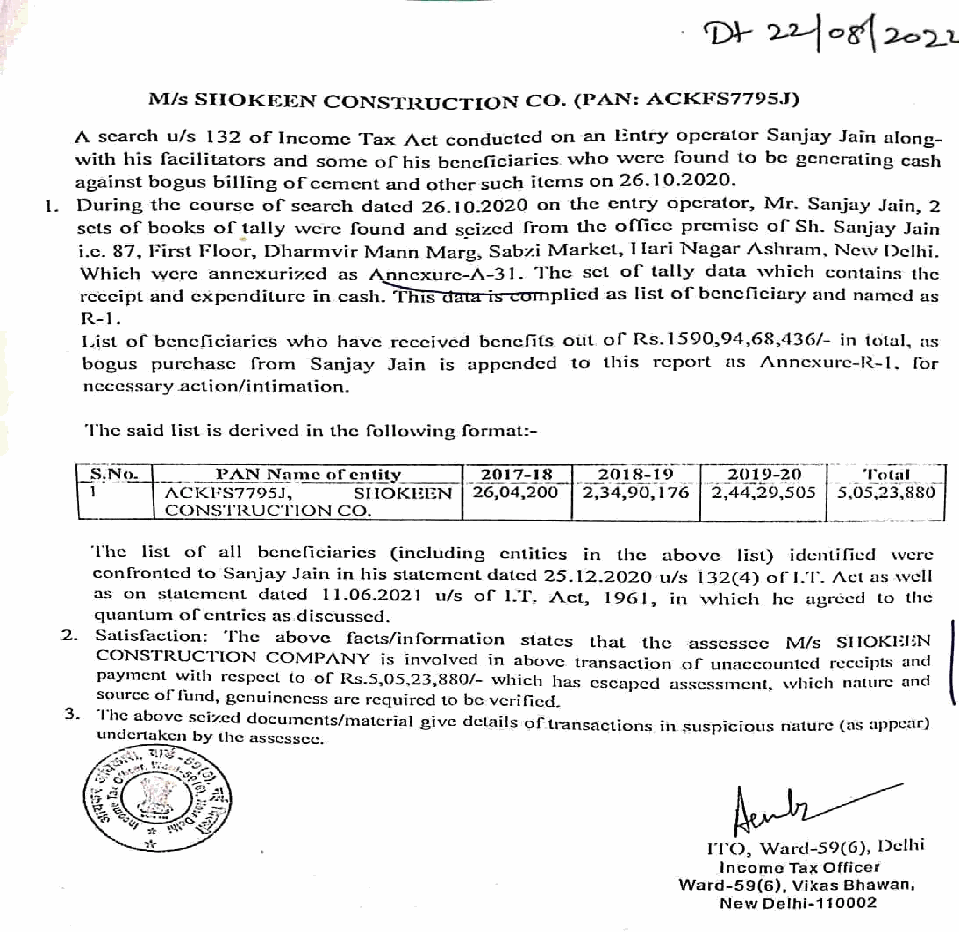
4. Brief facts of the case are that assessee company filed its original return of income on 31.10.2018, declaring income of INR 80,37,460/-. A search and seizure operation u/s 132 of the Act was carried out on 26.10.2020 in the cases of Sanjay Jain & Mehta Group at various residential and business premises. During the course of search two sets of books under tally software were found and seized from the office premises of Shri Sanjay Jain. On the basis of information available, a satisfaction note was prepared by the AO of person searched i.e. DCIT, Central Circle-30, New Delhi proposing for initiation of proceedings u/s 153C of the Act in the case of the assessee. Thereafter, notices u/s 153C was issued on 24.08.2022 by the AO of the assessee. After considering the submissions of the assessee and the documents seized during the course of search in the case of third person, the AO computed the income of the assessee company at INR 1,09,71,991/- vide assessment order dated 20.03.2023 passed u/s 153C r.w.s. 143(3) of the Act.
5. Against the said order, assessee filed an appeal before Ld. CIT(A) who vide order dated 16.12.2024, dismissed the appeal of the assessee.
6. Aggrieved by the order of Ld. CIT(A), assessee is in appeal before the Tribunal by taking following grounds of appeal:-
1. "On the facts and circumstances of the case and in law, the notice u/s153C issued by the assessing officer is bad-in-law, barred by limitation and without jurisdiction and, therefore, the said notice along with the assessment order passed on the foundation of such notice are liable to be quashed and CIT(A) erred in not holding so.
2. On the facts and circumstances of the case and in law, the notice u/s153C issued by the assessing officer is illegal and without jurisdiction. The assessing officer has not complied with the provisions of section 153C and other allied provisions for issuance of such notice. Accordingly, the notice u/s 153C along with the assessment order passed on the foundation of such notice are liable to be quashed and CIT(A) erred in not holding so.
3. On the facts and circumstances of the case and in law, the satisfaction note(s) recorded u/s 153C of the Act are bad-in-law and without jurisdiction and, accordingly, the assessment proceedings initiated on the foundation of such satisfaction note(s) and also the consequent assessment order passed are liable to be quashed and CIT(A) erred in not holding so.
4. On the facts and circumstances of the case and in law, the addition of Rs. 20,34,531/- made by the assessing officer on account of disallowance of purchases u/s 37 of the Act, is beyond the scope/jurisdiction of provisions of section 153C read with section 153A of the Income Tax Act, 1961 and CIT(A) erred in not holding so.
5. On the facts and circumstances of the case and in law, the Id.


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


