Back


2025 Supreme(Online)(ITAT) 8173
INCOME TAX APPELLATE TRIBUNAL (JAIPUR BENCH)
Unknown, J
AKHIL BHARATVARSHIYA PAPEEK ASHRAM TRUST AJMER – Appellant
Versus
CIT EXEMPTION JAIPUR – Respondent
Income Tax Appeal | ITA No. 1184/JP/2024 | ITA No. 1185/JP/2024
For the Appellants/Petitioners: Unknown
For the Respondents: Unknown
The Income Tax Tribunal found that rejection of registration due to alleged non-genuineness and community bias was incorrect, necessitating fresh adjudication after allowing submission of further evidence.
Headnote:(A) Income Tax Act, 1961 - Sections 12AB and 80G - Registration application rejection - The Commissioner of Income Tax (Exemption) erred in rejecting the registration application for being non-genuine and for the benefit of a particular community, which contradicts evidence provided by the assessee showing charitable activities for the entire society - The bench noted the necessity to allow the assessee an opportunity to rectify prior non-submissions. (Paras 9, 10)
(B) Natural justice - The failure to provide adequate opportunity to the assessee constitutes a violation of natural justice principles, warranting reinstatement of the appeal. (Paras 5, 10)
Facts of the case:
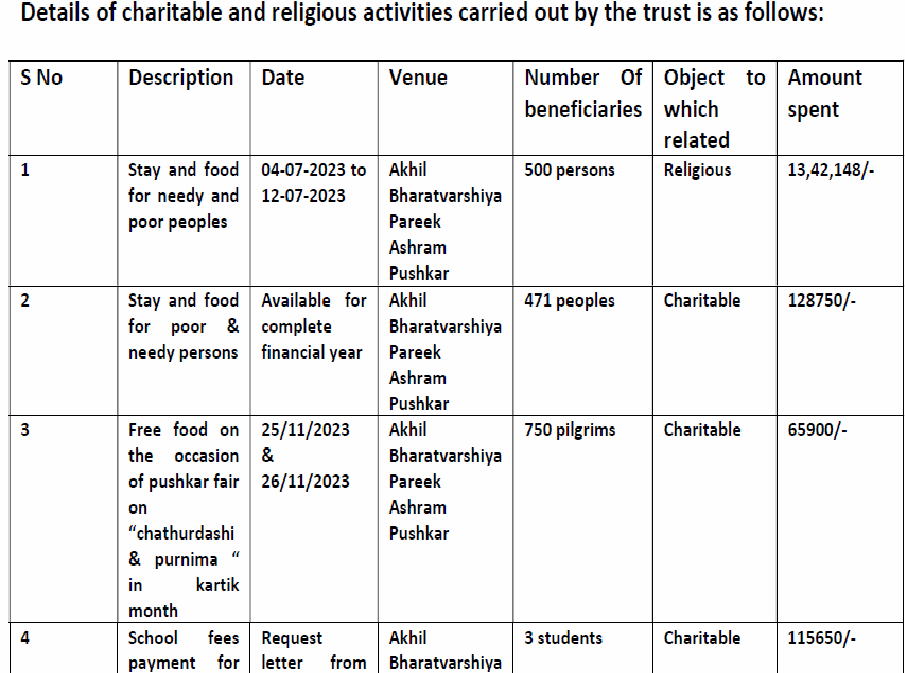
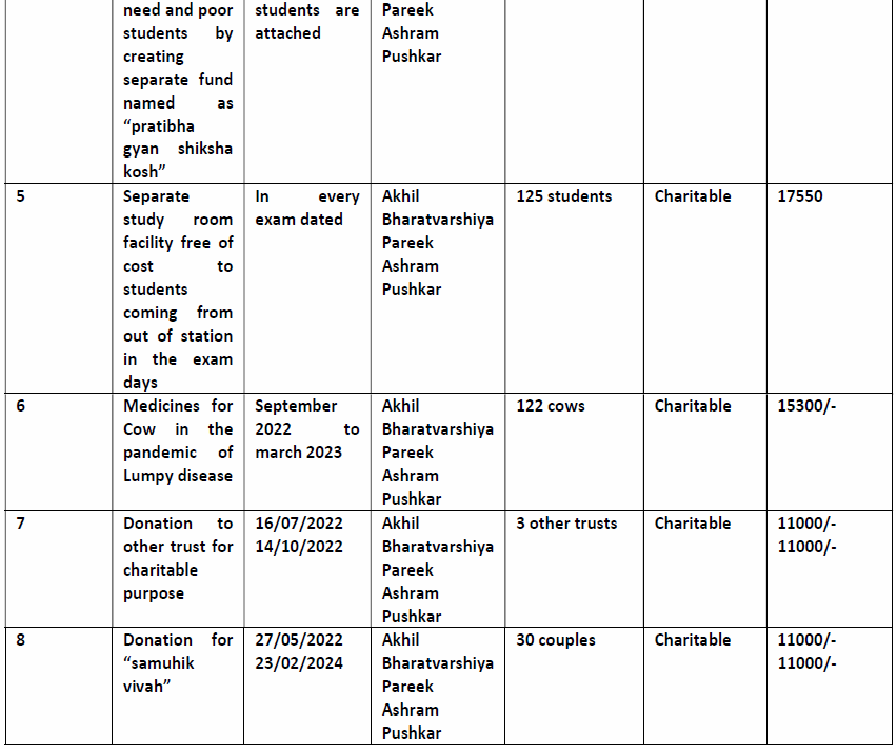
The assessee-applicant, a registered charitable trust, faced rejection for registration under the Income Tax Act citing discrepancies in its dissolution clause, non-genuine activities, and benefits to a specific community, combating which the trust provided evidence of its wide-ranging charitable work for society.
Findings of Court:
The appeal for registration under section 12AB is restored for reconsideration allowing additional opportunity for submission. The appeal under section 80G is similarly restored for fresh determination.
Issues: The principal issue concerning the rejection of registration for being non-genuine and providing benefits to a specific community, while arguing against the need for prior applications to dictate outcomes.
Ratio Decidendi: The court established that the past registration and activities of the trust showcase its genuine charitable intent and that the objections raised for rejections are rectifiable. The timestamp of establishment and prior registrations negates the claim of non-genuineness.
Result: Appeals restored for fresh adjudication.
| Table of Content |
|---|
| 1. introduction to appeals and grounds raised. (Para 4 , 5) |
| 2. court's findings and the necessity for further opportunities to the assessee. (Para 9 , 10) |
ORDER
These two appeals are filed by assessee and are arising out of the order of the Learned Commissioner of Income Tax (Exemption), Jaipur [for short ‘CIT(E)] passed under section 12AB and 80G of the Income Tax Act, 1961 [ for short Act ] both dated 19.07.2024 respectively.
2.1 In ITA No. 1184/JP/2024 the assessee has raised the following grounds: -
1. The order passed by Id. CIT Exemption in form no. 10AD is bad in law as well as on the facts of the present case and hence the same is liable to be quashed
2. The Id. CIT Exemption, Jaipur erred in law as well as on the facts of the present case in rejecting registration application made by the assessee u/s 12AB of the Act and accordingly it may be directed to grant exemption sought by the assesseee
3. The Id. CIT Exemption erred in law as well as on the facts of the present case in not giving full opportunity to the assessee before rejecting of application made by the assessee and hence the rejection of application is bad in law and on facts of the present case
4. The Id. CIT Exemption erred in law as well as on the facts of the present case in holding the objects of the assessee for the benefit of a particular community which is incorrect on facts and hence such findings may be quashed
5. The Id. CIT Exemption erred in law as well as on the 0 facts of the present case in holding the activities of the assessee as non-genuine which is incorrect on facts and hence such findings may be quashed
6. The Id. CIT Exemption erred in law as well as on the facts of the present case in holding the dissolution clause of the assessee as not being charitable which is based on misinterpretation of facts on record and hence such findings are prayed to be quashed
7. The assessee prays your goodself indulgence to add, amend, modify or delete all or any ground of appeal on or before the date of hearing
2.2 In ITA No. 1185/JP/2024 the assessee has raised the following grounds: -
“1. The order passed by ld. CIT Exemption in form no. 10AD is bad in law as well as on the facts of the present case and hence the same is liable to be quashed
2. The Id. CIT Exemption, Jaipur erred in law as well as 0 on the facts of the present case in rejecting registration application made by the assessee u/s 80G of the Act and accordingly it may be directed to grant exemption sought by the assessee
3. The Id. CIT Exemption erred in law as well as on the 0 facts of the present case in not giving full opportunity to the assessee before rejecting of application made by the assessee and hence the rejection of application is bad in law and on facts of the present case.
4. The Id. CIT Exemption erred in law as well as on the facts of the present case in holding that the assessee violated conditions for granting of registration u/s 80G which is contrary to the law and facts on record and consequently rejection of application is also bad in law
5. The assessee prays your goodself indulgence to add, amend, modify or delete all or any ground of appeal on or before the date of hearing.
3. The assessee-applicant vide application in form no. 10AB sought registration u/s.12AB of the Act. In that proceeding ld. CIT(E) gave four opportunity to the assessee to substantiate their claim of registration. Vide letter dated 29.06.2024 the assessee was asked to resolve various queries raised by the ld. CIT(E) but the assessee – applicant did not file the complete details and therefore, the application for registration of the applicant-trust as was rejected for registration u/s 12AB of the Act was rejected on the following grounds recording the reasons thereof : -
• Discrepancies in dissolution clause
• Object for the benefit of particular community
• Non Genuineness of Activities.
4. Aggrieved from that order of rejection u/s 12AB of the Act, assessee preferred the present appeal before