
 Back


INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
Pawan Singh, Judicial Member, Arun Khodpia, Accountant Member
Nirmala Pennechand Sarda – Appellant
Versus
ITO, Ward – 42(2)(4), Mumbai – Respondent
ITA No. 7291/MUM/2025 (AY: 2023-24)
| Table of Content |
|---|
| 1. appeal against cit(a) upholding ao's on-money addition. (Para 1 , 2) |
| 2. assessee challenges addition based on third-party loose papers. (Para 3 , 4) |
| 3. cit(a) upholds addition relying on search evidence. (Para 5) |
| 4. tribunal hears assessee's arguments against presumptive addition. (Para 6 , 7 , 9) |
| 5. revenue defends addition via coded seized materials. (Para 8) |
| 6. no addition without corroborative evidence linking assessee. (Para 10 , 11 , 12) |
| 7. appeal allowed; addition deleted. (Para 13) |
Order under section 254(1) of Income Tax Act
PER PAWAN SINGH, JUDICIAL MEMBER;
1. This appeal by assessee is directed against the order of ld. CIT(A)/NFAC dated 23.09.2025 for Assessment Year (AY) 2023-24. The assessee has raised following grounds of appeal:
“1. That on the facts and circumstances of the case as well as in law, the Id CIT (A), NFAC, Delhi [CIT (A)) has erred in upholding the validity of the assessment order u/s 143(3) of the Act passed by the Income Tax Officer, Ward-42(2) (4). Mumbai (JAO), whereas the assessment order so passed is clearly invalid, bad-in-law and contrary to the provisions of law. Appellant prays for quashing the assessment order so passed.
2. That on the facts and circumstances of the case as well as in law, the id CIT (A) has erred in upholding the addition made by the A.O. of Rs. 54,10,800/-u/s 69 of the Act in the name of on-money payment for purchase of shop. whereas neither any such on-money was paid by appellant nor there has been any finding of any such on-money paid by the appellant. Addition so made and sustained is wrong, unjustified and contrary to the settled law. Appellant prays for deleting this wrong and unjustified addition.
3. Without prejudice to generality of ground no '2' above, that the Id. CIT (A) has erred in not considering the case laws relied upon by the appellant (assessee) in the written appeal submission filed before Id. CIT (A) and in upholding the addition by taking the view contrary to the law laid down in the case laws so relied upon.
4. Without prejudice to generality of ground no '2' above, that the Id. CIT (A) has erred in upholding the addition made by the A.O of Rs. 54,10,800/- on the basis of seized material of third party, whereas said seized materials pertain to earlier years and there is nothing in the impugned seized material to infer on-money payment by the appellant and that too in the year under appeal.
(5) Appellant craves leave to add, alter, delete or modify any ground of appeal.”
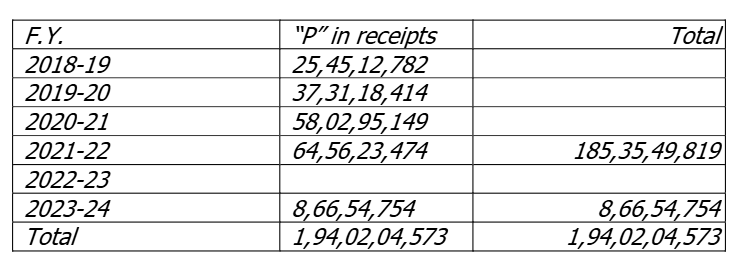
2. Brief facts of the case are that assessee is individual and filed her return of income for A.Y. 2023-24 declaring income of Rs. 54,10,800/-. Case was selected for scrutiny. During assessment, the assessing officer (AO) recorded that a search action under section 132 was carried out in Surana Group in Surat on 08.12.2023. In the said search action, certain incriminating material of unaccounted transaction pertaining to real estate business of Surana Group was found and seized from the residential premises of Pawankumar Rameshwarlal Lahoti. Out of such incriminating material, certain evidence pertains to project “IFC” that is international finance centre, which is commercial complex. As per the information available on GujRera website, it consists of one tower having 195 units. The project was developed in Vesu area of Surat. The AO also received information from DDIT, Unit-4, Surat that assessee purchase a unit in the project developed by Surana group and has paid on-money as. During the assessment, the assessing officer issued show cause notice which were complied by the assessee with relevant documentary evidence. The AO in para 5.1 of assessment order recorded that in the search action on Surana Group, various evidences were found wherein amounts were written in coded form with suppression ranging from one zero to seven zeros. In the search action, statement of Snehkumar Chhajer was recorded, who disclosed and decoded such zeros. The AO further recorded that financial year


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


