Back


2025 Supreme(Online)(ITAT) 11776
INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
SHAMIM YAHYA, Accountant Member, SUDHIR KUMAR, Judicial Member
Prashant Kansal – Appellant
Versus
DCIT – Respondent
ITA NO. 5577/Del/2019 A.YR. : 2015-16
For the Appellants/Petitioners: Shri Ved Jain, Adv. & Shri Aman Garg, CA
For the Respondents: Ms. Suman Malik, CIT(DR)
Deemed search date under S.153C is satisfaction recording date; assessment without S.153C notice for AY beyond six-year block is invalid.
Headnote:Under S.132 and S.153C of the Income Tax Act, 1961, search conducted on 11.11.2014 on Tirupati-Sunworld Group revealed incriminating documents relating to assessee. Assessment year 2015-16 framed u/s 143(3) adding Rs.3.70 crores as undisclosed income, confirmed by CIT(A). Court finds assessment invalid due to failure to issue notice u/s 153C after satisfaction recorded on 02.12.2016.
Issues: Whether assessment u/s 143(3) valid without S.153C notice post deemed search date. Ratio: Deemed search date is satisfaction recording date per Jasjit Singh (SC); AY 2015-16 falls outside six-year block from 02.12.2016, requiring S.153C notice; assessment void ab initio for jurisdictional error, following ITAT precedents like Akansha Gupta. Appeal allowed; assessment order dated 31.12.2016 quashed.
| Table of Content |
|---|
| 1. search revealed documents; assessment added undisclosed income. (Para 2 , 3) |
| 2. assessee contends no s.153c notice; dr defends lower orders. (Para 4 , 5 , 6) |
| 3. deemed search date is satisfaction date per supreme court. (Para 7) |
| 4. assessment u/s 143(3) invalid without s.153c notice. (Para 8) |
| 5. appeal allowed; assessment order quashed. (Para 9 , 10) |
ORDER PER SHAMIM YAHYA, AM:
The Assessee has filed the instant Appeal against the Order of the Ld. CIT(A)-IV, Kanpur dated 09.05.2019, relating to assessment year 2015-16.
2. Brief facts of the case are that a search and seizure operation u/s. 132 of the Income Tax Act, 1961 was conducted on 11.11.2014 in the case of Tirupati- Sunworld Group of companies where certain incriminating documents were found and seized relating to the assessee. Assessee e-filed return of income on 04.01.2016, disclosing total income of Rs. 90,75,560/-. Accordingly, notices u/s. 143(2) of the Act was issued on 13.12.2016. Further notices u/s. 143(2) & 142(1) were also issued and AO completed the assessment by making of addition of Rs. 3,70,00,000/- on account of undisclosed income.
3. Upon assessee’s appeal, Ld. CIT(A) confirmed the addition of Rs. 3,70,00,000/-.
4. Against the above order, assessee is in appeal before us and only argued the legal ground no. 2 & 3, which reads as under:-
“2. On the facts and circumstances of the case, the Ld.CIT(A) has erred both on facts and in law in rejecting the contention of the assessee that the assessment framed under section 153C/143(3) is bad and liable to be quashed as no valid notice under section 153C as required under the law has been issued and served on the assessee.
3. On the facts and circumstances of the case, the Ld. CIT(A) has erred both on facts and in law in rejecting the contention of the assessee that the proceedings initiated under section 153C and assumption of jurisdiction by AO are illegal and void ab initio.”
5. We have heard both the parties and perused the records. At the time of hearing, Ld. Counsel for the assessee submitted the following submissions :-
“1. The present appeal is for assessment year 2015-16 is against CIT(A) order dated 09.05.2019, wherein CIT(A) confirmed the addition of Rs.3,70,00,000/- made by AO via order dated 31.12.2016. However, the assessment order passed by the AO was without issue of notice under section 153C of the Act is bad in law and liable to be quashed. Legal issue (Ground 2-3)
2. In the present case a search and seizure operation u/s 132 of the Act was conducted on Tirupati assessee under section 153C of the Act by recording satisfaction on 02.12.2016 for AY 2009-10 to AY 2014-15. Copy of satisfaction note recorded by the assessing officer of the assessee (PB Page 7-8) assuming the date of search as 11.11.2014.
3. However, the deemed date of search in the present case will be 02.12.2016 in view of apex court judgement in the case of COMM/ISSIONER OF INCOME TAX 14 VERSUS JASJIT SINGH, 2023 (10) TMI 572 - SUPREME COURT, Dated.- September 26, 2023 and hence the period of block assessment of six years immediately preceding assessment year relevant to previous year in which search was conducted has to be reckoned from 02.12.2016, as under:-
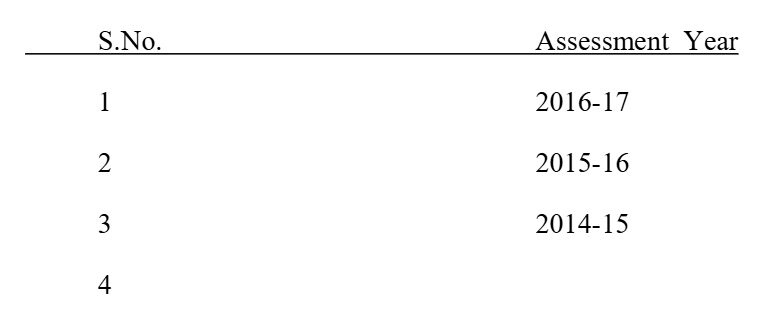
Hence, in the present case assessment proceedings for AY 2015-16, assessment should have been framed under section 153C of the Act after issuing notice under section 153C of the Act. However, proceedings in the case of the assessee were wrongly framed under section 143(3) of the Act without issue of notice under section 153C of the Act assuming the date of search as 11.11.2014 instead deemed date of search of 02.12.2016 and hence, the assessment order is bad in the eyes of the law on account of jurisdictional error and therefore liable to be quashed. The issue is squarely covered by Hon'ble ITAT Delhi judgement in the below mentioned cases-
> AKANSHA GUPTA VERSUS ACIT, CENTRAL CIRCLE-04, DELHI, 2024 (7) TMI 1133 - ITAT DELHI, Dated. - July 10, 2024-
"9. Therefore, in view o