
 Back


INCOME TAX APPELLATE TRIBUNAL (HYDERABAD BENCH)
Vijay Pal Rao, Vice-President, Manjunatha G., Accountant Member
Fayaz Mohammed – Appellant
Versus
Dy.CIT HYDERABAD Central Circle 2(4) – Respondent
ITA Nos 1671 & 1672/Hyd/2025
| Table of Content |
|---|
| 1. introductory details and grounds of appeal. (Para 1 , 2) |
| 2. factual background of search and cash payment addition. (Para 3 , 4 , 5 , 6) |
| 3. assessee argues section 153c notice time-barred. (Para 7 , 8) |
| 4. revenue defends timely section 153c satisfaction. (Para 9) |
| 5. court analyzes calcutta knitwears on satisfaction timing. (Para 10 , 11 , 12 , 13 , 14) |
| 6. section 153c notice invalid after 10 months. (Para 15) |
| 7. merits grounds infructuous; appeal allowed. (Para 16 , 17) |
| 8. identical relief for ay 2018-19. (Para 18 , 19 , 20) |
आदेश/ORDER
Per MANJUNATHA, G. A.M.
These two appeals are filed by the assessee are directed against the separate orders passed by the Learned Commissioner of Income Tax (Appeals)-12, Hyderabad, all dated 08/08/2025, for the Asst. Years 2017-18 and 2018-19. Since identical issues are raised by the assessee in these two appeals, for the sake of convenience, these appeals were heard together and are being disposed off, by this common consolidated order.
ITA No.1671/Hyd/2025 A.Y 2017-18
2. The assessee has raised the following grounds of appeal:
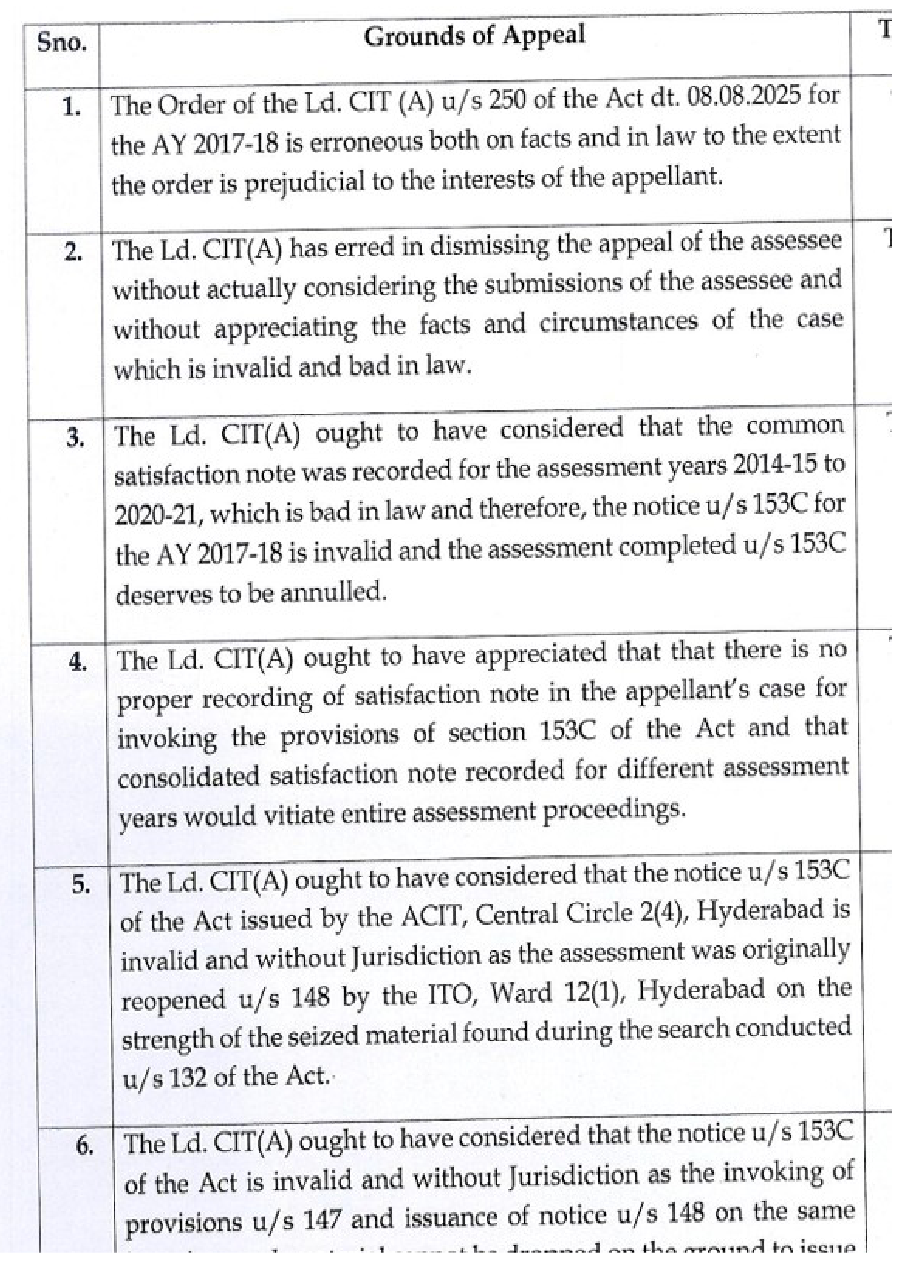
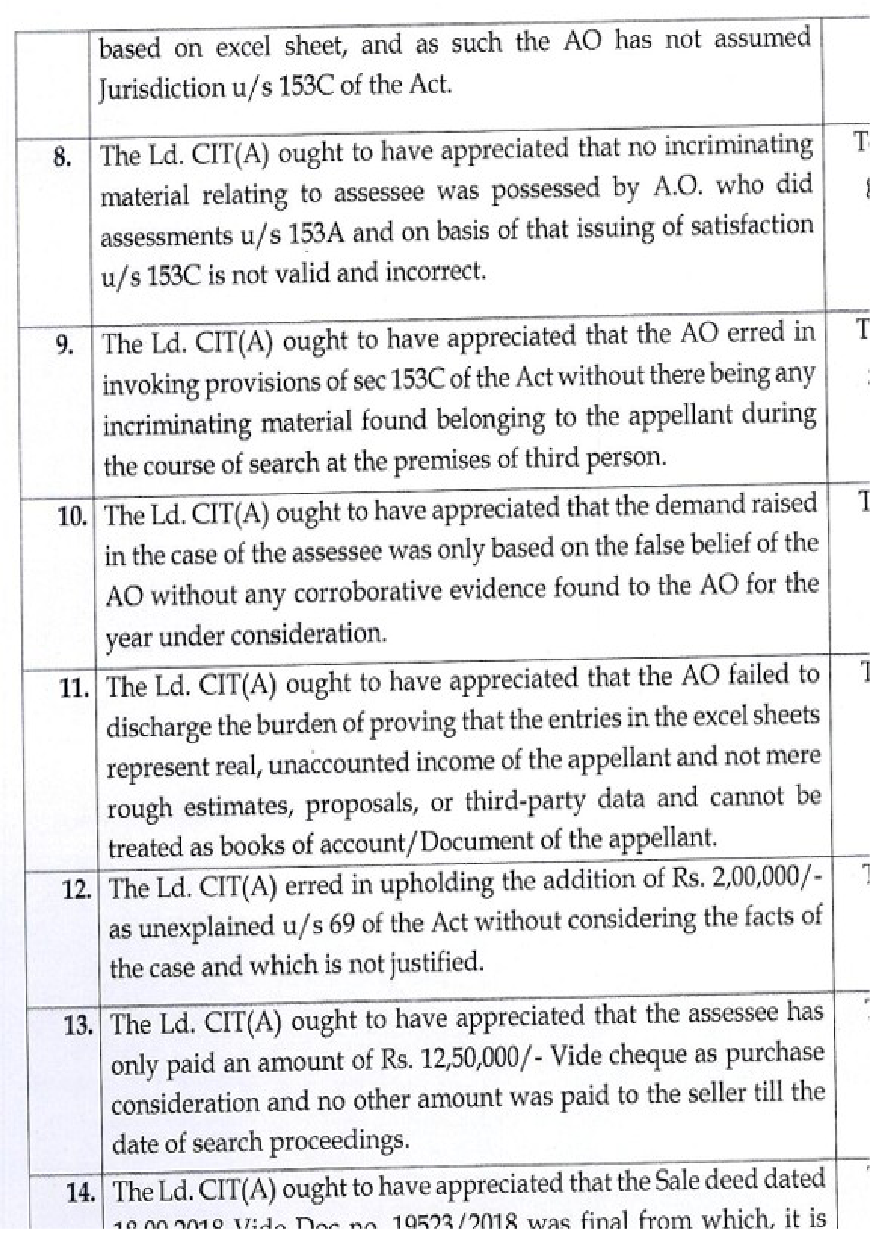
3. The brief facts of the case are that the assessee, an individual, filed his return of income for the A.Y 2017-18 declaring net income of Rs. Rs.27,07,060/-, after claiming deduction under Chapter VI-A of Rs.1,60,000/-. A search & seizure operation under section 132 of the Income Tax Act, 1961 is conducted in the case of M/s. Skill Promoters on 22/10/2019. During the course of assessment proceedings, in the case of the searched person, the A.O of the searched person, on analysis of seized material vide annexure No. A/SPPL/OFF/01 had satisfied that the information contained in the seized material pertains to the assessee and information contained therein, has a bearing on the determination of total income of the assessee for A.Ys from 2014-15 to 2020-21. Thereafter, the AO of the “other person” i.e., the assessee Mohammed Fayaz, has recorded Satisfaction Note for initiating proceedings u/s.153C of the Income-tax Act, 1961 with reference to the seized material and issued notice under section 153C of the Act on 3/8/2022. In response, the assessee filed return of income on 3/09/2022.
4. The case of the assessee was selected for scrutiny and during the course of assessment proceedings, the A.O, on the basis of material found during the course of search observed that the assessee has purchased a property from M/s. Skill Promoters (P) Ltd and paid consideration in cash for Rs. 21,50,000/-, out of which sum of Rs.2 lakhs has been paid for the A.Y 2017-18. Therefore, called upon the assessee to file its explanation, if any, as to why the addition should not be made towards consideration paid in cash for purchase of property as unexplained money. In response, the assessee vide letter dated 12/02/2024, submitted that, he had purchased the property and paid consideration of Rs.12,50,000/- by cheque and the same has been reported in the return of income filed for the year under consideration. The A.O after considering the relevant submissions of the assessee and also taking note of the relevant seized material made addition of Rs.2 lakhs paid for purchase property from M/s. Skill Promoters (P) Ltd under section 69 of the Act as unexplained money.
5. Aggrieved by the assessment order, the assessee preferred an appeal before the Ld. CIT (A). Before the Ld. CIT (A), the assessee challenged the addition made by the A.O towards cash payment made for purchase of property and argued that the assessee has not paid any cash, except the consideration paid through proper banking channel and therefore, the A.O is erred in making addition under section 69 of the Act. The Ld. CIT (A) after considering the relevant submission of the assessee and also taking note of the seized material found during the course of search observed that the material found during the course of search clearly shows details of the property along with the payments made in cheque and cash is exactly match with the pr


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


